



 Chat with AI
Exam 6: Variable Interest Entities, Intra-Entity Debt, Consolidated Cash Flows, and Other Issues

Exam 1: The Equity Method of Accounting for Investments119 Questions
Exam 2: Consolidation of Financial Information107 Questions
Exam 3: Consolidations - Subsequent to the Date of Acquisition122 Questions
Exam 4: Consolidated Financial Statements and Outside Ownership116 Questions
Exam 5: Consolidated Financial Statements Intra-Entity Asset Transactions127 Questions
Exam 6: Variable Interest Entities, Intra-Entity Debt, Consolidated Cash Flows, and Other Issues115 Questions
Exam 7: Consolidated Financial Statements - Ownership Patterns and Income Taxes115 Questions
Exam 8: Segment and Interim Reporting116 Questions
Exam 9: Foreign Currency Transactions and Hedging Foreign Exchange Risk93 Questions
Exam 10: Translation of Foreign Currency Financial Statements97 Questions
Exam 11: Worldwide Accounting Diversity and International Accounting Standards60 Questions
Exam 12: Financial Reporting and the Securities and Exchange Commission77 Questions
Exam 13: Accounting for Legal Reorganizations and Liquidations83 Questions
Exam 14: Partnerships: Formation and Operation88 Questions
Exam 15: Partnerships: Termination and Liquidation73 Questions
Exam 16: Accounting for State and Local Governments78 Questions
Exam 17: Accounting for State and Local Governments49 Questions
Exam 18: Accounting and Reporting for Private Not-For-Profit Organizations62 Questions
Exam 19: Accounting for Estates and Trusts80 Questions
Select questions type


Webb Company owns 90% of Jones Company. The original balances presented for Jones and Webb as of January 1, 2013, are as follows: 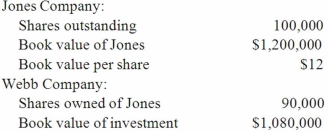 Jones sells 20,000 shares of previously unissued shares of its common stock to outside parties for $10 per share.
What is the new percent ownership of Webb in Jones after the stock issuance?
Jones sells 20,000 shares of previously unissued shares of its common stock to outside parties for $10 per share.
What is the new percent ownership of Webb in Jones after the stock issuance? (Multiple Choice)
4.7/5  (68)
(68) Johnson, Inc. owns control over Kaspar Inc, Johnson reports sales of $400,000 during 2013 while Kaspar reports $250,000. Kaspar transferred inventory during 2013 to Johnson at a price of $50,000. On December 31, 2013, 30% of the transferred goods are still in Johnson's inventory. Consolidated accounts receivable on January 1, 2013 was $120,000, and on December 31, 2013 is $130,000. Johnson uses the direct approach in preparing the statement of cash flows. How much is cash collected from customers in the consolidated statement of cash flows?
(Multiple Choice)
4.9/5 (75)
(75) Anderson, Inc. has owned 70% of its subsidiary, Arthur Corp., for several years. The consolidated balance sheets of Anderson, Inc. and Arthur Corp. are presented below:  Additional information for 2013:
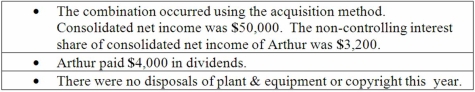 Net cash flow from financing activities was:
Additional information for 2013:
Net cash flow from financing activities was: (Multiple Choice)
4.8/5 (92)
(92) Fargus Corporation owned 51% of the voting common stock of Sanatee, Inc. The parent's interest was acquired several years ago on the date that the subsidiary was formed. Consequently, no goodwill or other allocation was recorded in connection with the acquisition price.
On January 1, 2012, Sanatee sold $1,400,000 in ten-year bonds to the public at 108. The bonds pay a 10% interest rate every December 31. Fargus acquired 40% of these bonds on January 1, 2014, for 95% of the face value. Both companies utilized the straight-line method of amortization.
What consolidation entry would be recorded in connection with these intra-entity bonds on December 31, 2014?
(Essay)
4.8/5 (93)
(93) How would consolidated earnings per share be calculated if the subsidiary has no convertible securities or warrants?
(Multiple Choice)
4.7/5 (92)
(92) The following information has been taken from the consolidation worksheet of Graham Company and its 80% owned subsidiary, Stage Company.
(1)) Graham reports a loss on sale of land of $5,000. The land cost Graham $20,000.
(2)) Non-controlling interest in Stage's net income was $30,000.
(3)) Graham paid dividends of $15,000.
(4)) Stage paid dividends of $10,000.
(5)) Excess acquisition-date fair value over book value was expensed by $6,000.
(6)) Consolidated accounts receivable decreased by $8,000.
(7)) Consolidated accounts payable decreased by $7,000.
How is the loss on sale of land reported on the consolidated statement of cash flows?
(Multiple Choice)
4.7/5 (87)
(87) The balance sheets of Butler, Inc. and its 70 percent-owned subsidiary, Cassie Corp., are presented below:  Additional information for 2013:
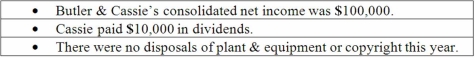 Net cash flow from operating activities was:
Additional information for 2013:
Net cash flow from operating activities was: (Multiple Choice)
4.8/5 (82)
(82) Which of the following is not an indicator that requires a sponsoring firm to consolidate a variable interest entity (VIE) with its own financial statements?
(Multiple Choice)
4.9/5 (77)
(77) Regency Corp. recently acquired $500,000 of the bonds of Safire Co., one of its subsidiaries, paying more than the carrying value of the bonds. According to the most practical view of this intra-entity transaction, to whom would the loss be attributed?
(Multiple Choice)
4.8/5 (69)
(69) Tray Co. reported current earnings of $560,000 while paying $56,000 in cash dividends. Sparrish Co. earned $140,000 in net income and distributed $14,000 in dividends. Tray held a 70% interest in Sparrish for several years, an investment that it originally acquired by transferring consideration equal to the book value of the underlying net assets. Tray used the initial value method to account for these shares.
On January 1, 2013, Sparrish acquired in the open market $70,000 of Tray's 8% bonds. The bonds had originally been issued several years ago at 92, reflecting a 10% effective interest rate. On the date of the bond purchase, the book value of the bonds payable was $67,600. Sparrish paid $65,200 based on a 12% effective interest rate over the remaining life of the bonds.
What is the non-controlling interest's share of the subsidiary's net income?
(Multiple Choice)
4.8/5 (64)
(64) Panton, Inc. acquired 18,000 shares of Glotfelty Corp. several years ago. At the present time, Glotfelty is reporting the following stockholders' equity:  Glotfelty issues 5,000 shares of previously unissued stock to the public for $27 per share. None of this stock is purchased by Panton.
Prepare Panton's journal entry to recognize the impact of this transaction.
Glotfelty issues 5,000 shares of previously unissued stock to the public for $27 per share. None of this stock is purchased by Panton.
Prepare Panton's journal entry to recognize the impact of this transaction. (Essay)
4.8/5 (76)
(76) On January 1, 2013, Riney Co. owned 80% of the common stock of Garvin Co. On that date, Garvin's stockholders' equity accounts had the following balances: 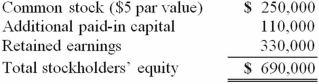 The balance in Riney's Investment in Garvin Co. account was $552,000, and the non-controlling interest was $138,000. On January 1, 2013, Garvin Co. sold 10,000 shares of previously unissued common stock for $15 per share. Riney did not acquire any of these shares.
What is the balance in Investment in Garvin Co. after the sale of the 10,000 shares of common stock?
The balance in Riney's Investment in Garvin Co. account was $552,000, and the non-controlling interest was $138,000. On January 1, 2013, Garvin Co. sold 10,000 shares of previously unissued common stock for $15 per share. Riney did not acquire any of these shares.
What is the balance in Investment in Garvin Co. after the sale of the 10,000 shares of common stock? (Multiple Choice)
4.8/5 (78)
(78) Cadion Co. owned a controlling interest in Knieval Inc. Cadion reported sales of $420,000 during 2013 while Knieval reported $280,000. Inventory costing $28,000 was transferred from Knieval to Cadion (upstream) during the year for $56,000. Of this amount, twenty-five percent was still in ending inventory at year's end. Total receivables on the consolidated balance sheet were $112,000 at the first of the year and $154,000 at year-end. No intra-entity debt existed at the beginning or ending of the year. Using the direct approach, what is the consolidated amount of cash collected by the business combination from its customers?
(Multiple Choice)
4.9/5 (76)
(76) These questions are based on the following information and should be viewed as independent situations.
Popper Co. acquired 80% of the common stock of Cocker Co. on January 1, 2011, when Cocker had the following stockholders' equity accounts.  To acquire this interest in Cocker, Popper paid a total of $682,000 with any excess acquisition date fair value over book value being allocated to goodwill, which has been measured for impairment annually and has not been determined to be impaired as of January 1, 2014.
On January 1, 2014, Cocker reported a net book value of $1,113,000 before the following transactions were conducted. Popper uses the equity method to account for its investment in Cocker, thereby reflecting the change in book value of Cocker.
On January 1, 2014, Cocker issued 10,000 additional shares of common stock for $21 per share. Popper did not acquire any of this newly issued stock. How would this transaction affect the additional paid-in capital of the parent company?
To acquire this interest in Cocker, Popper paid a total of $682,000 with any excess acquisition date fair value over book value being allocated to goodwill, which has been measured for impairment annually and has not been determined to be impaired as of January 1, 2014.
On January 1, 2014, Cocker reported a net book value of $1,113,000 before the following transactions were conducted. Popper uses the equity method to account for its investment in Cocker, thereby reflecting the change in book value of Cocker.
On January 1, 2014, Cocker issued 10,000 additional shares of common stock for $21 per share. Popper did not acquire any of this newly issued stock. How would this transaction affect the additional paid-in capital of the parent company? (Multiple Choice)
4.8/5 (76)
(76) Davidson, Inc. owns 70 percent of the outstanding voting stock of Ernest Company. On January 2, 2011, Davidson sold 8 percent bonds payable with a $5,000,000 face value maturing January 2, 2031 at a premium of $400,000. On January 1, 2013, Ernest acquired 30 percent of these same bonds on the open market at 97.6. Both companies use the straight-line method of amortization. What adjustment should be made to Davidson's 2014 beginning Retained Earnings as a result of this bond acquisition?
(Multiple Choice)
4.8/5 (76)
(76) On January 1, 2013, Nichols Company acquired 80% of Smith Company's common stock and 40% of its non-voting, cumulative preferred stock. The consideration transferred by Nichols was $1,200,000 for the common and $124,000 for the preferred. Any excess acquisition-date fair value over book value is considered goodwill. The capital structure of Smith immediately prior to the acquisition is: 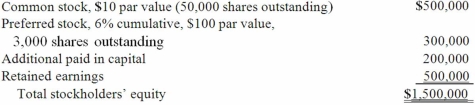 The consolidation entry at date of acquisition will include (referring to Smith):
 (Multiple Choice)
4.9/5 (81)
(81) Parent Corporation had just purchased some of its subsidiary's outstanding bonds on the open market. What items related to these bonds will have to be accounted for in the consolidation process?
(Essay)
4.9/5 (69)
(69) Which one of the following characteristics of preferred stock would make the stock a dilutive security for earnings per share?
(Multiple Choice)
5.0/5 (71)
(71) Ryan Company owns 80% of Chase Company. The original balances presented for Ryan and Chase as of January 1, 2013 are as follows:  Assume Chase reacquired 8,000 shares of its common stock from outsiders at $10 per share.
What should the adjusted book value of Chase be after the treasury shares were purchased?
Assume Chase reacquired 8,000 shares of its common stock from outsiders at $10 per share.
What should the adjusted book value of Chase be after the treasury shares were purchased? (Multiple Choice)
4.8/5 (84)
(84) Keenan Company has had bonds payable of $20,000 outstanding for several years. On January 1, 2013, there was an unamortized premium of $2,000 with a remaining life of 10 years, Keenan's parent, Ross, Inc. purchased the bonds in the open market for $19,000. Keenan is a 90% owned subsidiary of Ross. The bonds pay 8% interest annually on December 31. The companies use the straight-line method to amortize interest revenue and expense. Compute the consolidated gain or loss on a consolidated income statement for 2013.
(Multiple Choice)
4.8/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)