



 Chat with AI
Exam 6: Inventories

Exam 1: Introduction to Accounting and Business188 Questions
Exam 2: Analyzing Transactions216 Questions
Exam 3: The Adjusting Process179 Questions
Exam 4: Completing the Accounting Cycle198 Questions
Exam 5: Accounting for Merchandising Businesses220 Questions
Exam 6: Inventories170 Questions
Exam 7: Sarbanes-Oxley, Internal Control, and Cash178 Questions
Exam 8: Receivables148 Questions
Exam 9: Fixed Assets and Intangible Assets177 Questions
Exam 10: Current Liabilities and Payroll174 Questions
Exam 11: Corporations: Organization, Stock Transactions, and Dividends172 Questions
Exam 12: Long-Term Liabilities: Bonds and Notes186 Questions
Exam 13: Investments and Fair Value Accounting133 Questions
Exam 14: Statement of Cash Flows161 Questions
Exam 15: Financial Statement Analysis184 Questions
Exam 16: Managerial Accounting Concepts and Principles175 Questions
Exam 17: Job Order Costing176 Questions
Exam 18: Process Cost Systems177 Questions
Exam 19: Cost Behavior and Cost-Volume-Profit Analysis215 Questions
Exam 20: Variable Costing for Management Analysis154 Questions
Exam 21: Budgeting185 Questions
Exam 22: Performance Evaluation Using Variances From Standard Costs160 Questions
Exam 23: Performance Evaluation for Decentralized Operations198 Questions
Exam 24: Differential Analysis and Product Pricing161 Questions
Exam 25: Capital Investment Analysis179 Questions
Exam 26: Cost Allocation and Activity-Based Costing111 Questions
Exam 27: Cost Management for Just-In-Time Environments122 Questions
Select questions type


The following information was extracted from the Stone Company's records.
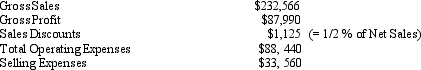 Complete the following:
Gross Sales Sales Discounts Sales Returns \& Allowances Net Sales Cost of Goods Sold Gross Profit Operating Expenses: Gen. \& Admin Expenses Selling Expenses Total Operating Expenses Net Income (Loss)
Complete the following:
Gross Sales Sales Discounts Sales Returns \& Allowances Net Sales Cost of Goods Sold Gross Profit Operating Expenses: Gen. \& Admin Expenses Selling Expenses Total Operating Expenses Net Income (Loss) (Essay)
4.8/5  (70)
(70) During the taking of its physical inventory on December 31, 2011, Gentry Supplies Company incorrectly counted its inventory as $245,000 instead of the correct amount of $254,000. Indicate the affect of the misstatement on Gentry Supplies Company's balance sheet and income statement for the year ended December 31, 2011.
(Essay)
4.8/5 (90)
(90) During August, the first month of the fiscal year, sales totaled $875,000 and the cost of merchandise available for sale totaled $700,000. Estimate the cost of the merchandise inventory as of August 31, based on an estimated gross profit rate of 45%.
(Essay)
4.8/5 (79)
(79) Inventory errors, if not discovered, will self-correct in two years.
(True/False)
4.8/5 (81)
(81) When using the FIFO inventory costing method, the most recent costs are assigned to the cost of goods sold.
(True/False)
5.0/5 (80)
(80) The use of the lower-of-cost-or-market method of inventory valuation increases net income for the period in which the inventory replacement price declined.
(True/False)
4.9/5 (88)
(88) Of the three widely used inventory costing methods (FIFO, LIFO, and average cost), the LIFO method of costing inventory assumes costs are charged based on the most recent purchases first.
(True/False)
4.7/5 (87)
(87) Hampton Co. took a physical count of its inventory on December 31. In addition, it had to decide whether or not the following items should be added to this count.
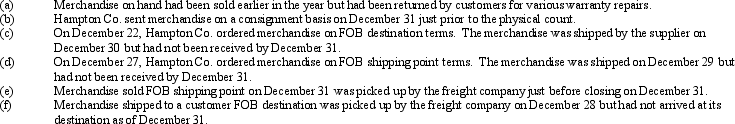 Indicate which items should be added to (answer: yes) and which items should not be added to (answer: no) the December 31 inventory count.
 (Essay)
4.7/5 (83)
(83) Control of inventory should begin as soon as the inventory is received. Which of the following internal control steps is not done to meet this goal?
(Multiple Choice)
4.7/5 (72)
(72) Most large companies will use only one inventory costing methods for all of its different segments.
(True/False)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)