



 Chat with AI
Exam 6: Firms,the Stock Market,and Corporate Governance

Exam 1: Economics: Foundations and Models160 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System191 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply241 Questions
Exam 4: Market Efficiency and Market Failure226 Questions
Exam 5: The Economics of Healthcare169 Questions
Exam 6: Firms,the Stock Market,and Corporate Governance255 Questions
Exam 7: Consumer Choice and Elasticity270 Questions
Exam 8: Technology, production, and Costs277 Questions
Exam 9: Firms in Perfectly Competitive Markets351 Questions
Exam 10: Monopoly and Antitrust253 Questions
Exam 11: Monopolistic Competition and Oligopoly304 Questions
Exam 12: GDP: Measuring Total Production and Income200 Questions
Exam 13: Unemployment and Inflation207 Questions
Exam 14: Economic Growth, the Financial System and Business Cycles172 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis120 Questions
Exam 16: Money, banks, and the Federal Reserve System139 Questions
Exam 17: Monetary Policy180 Questions
Exam 18: Fiscal Policy131 Questions
Exam 19: Comparative Advantage, international Trade, and Exchange Rates247 Questions
Select questions type


Table 6-1
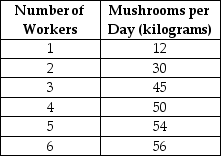 Table 6-1 shows the technology of production at the Matsuko's Mushroom Farm for the month of May.
-Refer to Table 6-1.Diminishing marginal returns sets in when the ________ worker is hired.
Table 6-1 shows the technology of production at the Matsuko's Mushroom Farm for the month of May.
-Refer to Table 6-1.Diminishing marginal returns sets in when the ________ worker is hired. (Multiple Choice)
4.9/5  (71)
(71) When a firm experiences negative technological change,it can produce the same output with fewer inputs.
(True/False)
4.9/5 (73)
(73) The process a firm uses to turn inputs into outputs of goods and services is called technology.
(True/False)
4.9/5 (86)
(86) The total output produced by a firm divided by the quantity of workers employed by the firm is the definition of
(Multiple Choice)
4.7/5 (76)
(76) Figure 6-7  Figure 6-7 shows the cost structure for a firm.
-Refer to Figure 6-7.When the output level is 100,what is the total cost of production?
Figure 6-7 shows the cost structure for a firm.
-Refer to Figure 6-7.When the output level is 100,what is the total cost of production? (Multiple Choice)
4.9/5 (75)
(75) Minimum efficient scale is defined as the level of output at which the short-run average total cost stops decreasing.
(True/False)
4.8/5 (66)
(66) Marginal cost is calculated for a particular increase in output by
(Multiple Choice)
4.9/5 (75)
(75) The difference between technology and technological change is that
(Multiple Choice)
4.9/5 (72)
(72) Table 6-7
 Table 6-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 6-7.What is the marginal cost per unit of production when the firm produces 100 lanterns?
Table 6-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 6-7.What is the marginal cost per unit of production when the firm produces 100 lanterns? (Multiple Choice)
4.9/5 (83)
(83) When a firm produces more output using the same inputs or the same output using fewer inputs we say that the firm
(Multiple Choice)
4.8/5 (75)
(75) Figure 6-11  Figure 6-11 illustrates the long-run average cost curve for a firm that produces picture frames. The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 6-11.For output rates greater than 20 000 picture frames per month,
Figure 6-11 illustrates the long-run average cost curve for a firm that produces picture frames. The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 6-11.For output rates greater than 20 000 picture frames per month, (Multiple Choice)
5.0/5 (68)
(68) A firm's cost of production is determined by all of the following except
(Multiple Choice)
5.0/5 (69)
(69) Adam spent $10 000 on new equipment for his small business,'Adam's Fitness Studio.' Membership at his fitness centre is very low and,at this rate,Adam needs an additional $12 000 per year to keep his studio open.Which of the following is true?
(Multiple Choice)
4.8/5 (78)
(78) If production displays economies of scale,the long-run average cost curve is
(Multiple Choice)
4.7/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)