



 Chat with AI
Exam 23: Cost Behavior Analysis

Exam 1: Uses of Accounting Information and the Financial Statements167 Questions
Exam 2: Analyzing Business Transactions189 Questions
Exam 3: Measuring Business Income171 Questions
Exam 4: Completing the Accounting Cycle176 Questions
Exam 5: Financial Reporting and Analysis177 Questions
Exam 6: The Operating Cycle and Merchandising Operations145 Questions
Exam 7: Internal Control117 Questions
Exam 8: Inventories154 Questions
Exam 9: Cash and Receivables177 Questions
Exam 10: Current Liabilities and Fair Value Accounting180 Questions
Exam 11: Long Term Assets241 Questions
Exam 12: Contributed Capital189 Questions
Exam 13: Long Term Liabilities194 Questions
Exam 14: The Corporate Income Statement and the Statement of Stockholders Equity176 Questions
Exam 15: The Statement of Cash Flows149 Questions
Exam 16: Financial Performance Measurement163 Questions
Exam 17: Partnerships129 Questions
Exam 18: The Changing Business Environment-A Managers Pers130 Questions
Exam 19: Cost Concepts and Cost Allocation188 Questions
Exam 20: Costing Systems: Job Order Costing88 Questions
Exam 21: Costing Systems Process Costing136 Questions
Exam 22: Activity-Based Systems-Abm and Lean152 Questions
Exam 23: Cost Behavior Analysis166 Questions
Exam 24: The Budgeting Process116 Questions
Exam 25: Performance Management and Evaluation117 Questions
Exam 26: Standard Costing and Variance Analysis120 Questions
Exam 27: Short Run Decision Analysis90 Questions
Exam 28: Capital Investment Analysis123 Questions
Select questions type


A contribution margin income statement is formatted to emphasize cost behavior rather than organizational functions.
(True/False)
4.8/5  (86)
(86) Listed below are selected costs of a sports car manufacturer at a production level of 4,000 cars. (a) Identify three variable costs. (b) Support your answer by illustrating the cost behavior pattern per unit and in total as the annual volume of motorcycles produced increases from 4,000 cars to 8,000 cars for one variable cost.
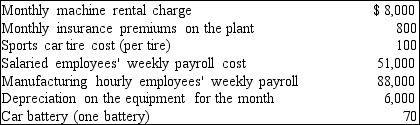
(Essay)
4.9/5 (63)
(63) Lakeside has gathered the following data in order to calculate the weighted-average contribution margin: Unit Sales Price Unit Variable Costs Unit Sales Product A \ 150 \ 100 8,000 Product B 100 60 2,000 The weighted-average contribution margin is
(Multiple Choice)
4.7/5 (83)
(83) If targeted sales are 12,000 units, the sales price per unit is $70, fixed costs are $130,000, and variable costs are $40 per unit, then planned profit must be $230,000.
(True/False)
4.9/5 (85)
(85) A product line's contribution margin represents its contribution to paying off variable costs and to generating a profit.
(True/False)
4.8/5 (79)
(79) How many units must BAC Company sell to break even if the selling price per unit is $8.50, variable costs are $4.00 per unit, and fixed costs are $9,000?
(Multiple Choice)
4.8/5 (72)
(72) The equation that will provide the breakeven point in units (SP = selling price) is
(Multiple Choice)
5.0/5 (89)
(89) Martin, Inc., has two products: a pocket metronome (unit sales price, $25; unit variable cost, $15) and a pocket tuner (unit sales price, $14; unit variable cost, $9). The company's sales mix of the pocket metronome to the pocket tuner is 4:1 and fixed costs are $32,850.
a. Determine the weighted-average contribution margin.
b. Calculate the weighted-average breakeven point.
c. Compute the breakeven point for each product.
(Essay)
4.8/5 (79)
(79) Using the high-low method and the information below, compute the monthly variable cost per telephone hour for SKP Corporation. Month Telephone Hours Used Telephone Expenses April 100 \ 4,500 May 110 4,800 June 150 5,400
(Multiple Choice)
5.0/5 (87)
(87) The contribution margin equals total fixed costs at the breakeven point.
(True/False)
4.8/5 (69)
(69) For every unit that a company produces and sells above the breakeven point, its profitability is improved (ignoring taxes) by the unit's
(Multiple Choice)
4.7/5 (74)
(74) Within the relevant range, fixed and variable costs behave differently.
(True/False)
4.9/5 (83)
(83) Lakeside has gathered the following data in order to calculate the weighted-average contribution margin: Unit Sales Price Unit Variable Costs Unit Sales Product A \ 150 \ 100 8,000 Product B 100 60 2,000 The weighted-average breakeven point is
(Multiple Choice)
4.9/5 (89)
(89) The equation for finding the breakeven point may be written as
(Multiple Choice)
4.8/5 (89)
(89) In terms of cost behavior, telephone expense and direct materials are classified as
(Multiple Choice)
4.9/5 (70)
(70) Cost-volume-profit analysis is not appropriate for service businesses.
(True/False)
4.8/5 (73)
(73) Tigor Enterprises has sales revenue of $340,000 for 20xx. Its product sells for $12 and has a 20 percent contribution margin. Fixed costs are $21,000. What is Tigor Enterprises' operating income for 20xx?
(Multiple Choice)
4.9/5 (81)
(81) The weighted-average breakeven point is the breakeven point for the entire company.
(True/False)
4.8/5 (75)
(75) Linear approximation is a method of converting nonlinear variable costs into linear fixed costs.
(True/False)
4.9/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)