



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law195 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Computing the Tax187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: in General146 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses95 Questions
Exam 8: Depreciation, cost Recovery, amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses181 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions105 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Tax Credits and Payments118 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, basis Considerations, and Nontaxable Exchanges280 Questions
Exam 14: Property Transactions, capital Gains and Losses, sec1231, and Recapture Provisions145 Questions
Exam 15: Alternative Minimum Tax132 Questions
Exam 16: Accounting Periods and Methods91 Questions
Exam 17: Corporations: Introduction and Operating Rules112 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation192 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganization72 Questions
Exam 21: Partnerships163 Questions
Exam 22: S Corporations145 Questions
Exam 23: Exempt Entities141 Questions
Exam 24: Multistate Corporate Taxation196 Questions
Exam 25: Taxation of International Transactions164 Questions
Exam 26: Tax Practice and Ethics183 Questions
Exam 27: The Federal Gift and Estate Taxes167 Questions
Exam 28: Income Taxation of Trusts and Estates167 Questions
Select questions type


Distributions of appreciated property by an S corporation are not taxable to the entity.
(True/False)
4.8/5  (77)
(77) The passive investment income of an S corporation includes net capital gains from the sale of stocks and securities.
(True/False)
4.8/5 (77)
(77) A corporation may alternate between S corporation and C corporation status each year,depending on which results in more tax savings.
(True/False)
5.0/5 (78)
(78) Shareholders owning a(n) ____________________ of shares (voting and nonvoting) may ____________________ revoke an S election.
(Short Answer)
4.9/5 (77)
(77) Oxen Corporation incurs the following transactions.
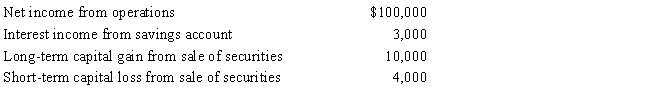 Oxen maintains a valid S election and does not distribute any assets (cash or property) to its sole shareholder,Megan.As a result,Megan must recognize:
 (Multiple Choice)
4.8/5 (75)
(75) A per-day,per-share allocation of flow-through S corporation items must be used,unless the shareholder disposes of the entire interest in the entity.
(True/False)
4.9/5 (87)
(87) The § 1202 exclusion of _________________ on the disposition of small business stock (is/is not) _________________ available for S stock.
(Short Answer)
4.7/5 (76)
(76) A two-or-more member ____________________ operates under ____________________ tax principles.
(Short Answer)
4.8/5 (82)
(82) Which statement is incorrect with respect to filing an S election?
(Multiple Choice)
4.8/5 (93)
(93) All tax preference items flow through the S corporation,to be included in the shareholders' AMT calculations.
(True/False)
4.9/5 (79)
(79) Voting common stock and voting preferred stock (with a preference on dividends) would be treated as ____________________ class(es) of stock.
(Short Answer)
4.8/5 (91)
(91) Depreciation recapture income is a ____________________ computed amount.
(Short Answer)
4.9/5 (84)
(84) An S corporation recognizes a ____________________ on any distribution of appreciated property.
(Short Answer)
5.0/5 (71)
(71) Separately stated items are listed on Schedule _________________________ of the Form 1120S.
(Short Answer)
4.9/5 (72)
(72) The choice of a flow-through entity for a closely-held corporation often is between a(n) ____________________ (a Federal tax entity) and a(n) ____________________ (a state tax entity).
(Short Answer)
4.9/5 (74)
(74) Alomar,a cash basis S corporation in Orlando,Florida,holds the following assets and liabilities on January 1,2016,the date the S election is made.
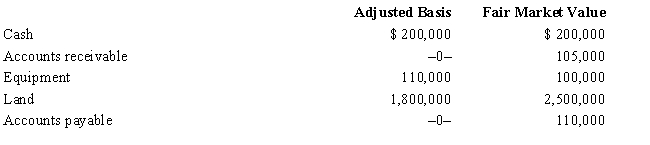 During the year,Alomar collects the accounts receivable and pays the accounts payable.The land is sold for $3 million,and the taxable income for the year is $590,000.Calculate any built-in gains tax.
 (Essay)
4.8/5 (89)
(89) If an S corporation's beginning balance in OAA is zero,and the following transactions occur,what is the ending OAA balance?
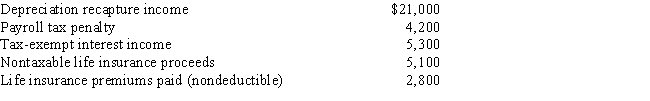
(Multiple Choice)
4.8/5 (77)
(77) Several individuals acquire assets on behalf of Skip Corporation on May 28,purchased assets on June 3 and began business on June 11.They subscribe to shares of stock,file articles of incorporation for Skip,and become shareholders on June 21.The S election must be filed no later than 2 1/2 months after:
(Multiple Choice)
4.9/5 (78)
(78) An S shareholder who dies during the S corporation tax year must report his or her share of the pro rata income (loss) items up to the date of death,on the final individual tax return.
(True/False)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)