



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law195 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Computing the Tax187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: in General146 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses95 Questions
Exam 8: Depreciation, cost Recovery, amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses181 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions105 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Tax Credits and Payments118 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, basis Considerations, and Nontaxable Exchanges280 Questions
Exam 14: Property Transactions, capital Gains and Losses, sec1231, and Recapture Provisions145 Questions
Exam 15: Alternative Minimum Tax132 Questions
Exam 16: Accounting Periods and Methods91 Questions
Exam 17: Corporations: Introduction and Operating Rules112 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation192 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganization72 Questions
Exam 21: Partnerships163 Questions
Exam 22: S Corporations145 Questions
Exam 23: Exempt Entities141 Questions
Exam 24: Multistate Corporate Taxation196 Questions
Exam 25: Taxation of International Transactions164 Questions
Exam 26: Tax Practice and Ethics183 Questions
Exam 27: The Federal Gift and Estate Taxes167 Questions
Exam 28: Income Taxation of Trusts and Estates167 Questions
Select questions type


Persons who were S shareholders during any part of the year before the election date,but were not shareholders when the election was made,also must consent to an S election.
(True/False)
4.9/5  (83)
(83) Which,if any,of the following can be eligible shareholders of an S corporation?
(Multiple Choice)
4.7/5 (89)
(89) Which statement is incorrect with respect to filing for an S election?
(Multiple Choice)
4.9/5 (65)
(65) The termination of an S election occurs on the day after a corporation ceases to be a qualifying S corporation.
(True/False)
4.8/5 (81)
(81) Advise your client how income,expenses,gain,and losses are allocated to shareholders of an S corporation.
(Essay)
4.8/5 (88)
(88) Post-termination distributions that are charged against OAA are received tax-free.
(True/False)
4.7/5 (88)
(88) You are given the following facts about a 40% owner of an S corporation,and you are asked to prepare her ending stock basis.
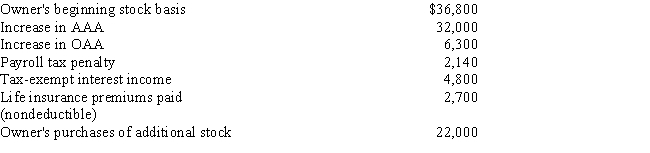
(Multiple Choice)
4.8/5 (72)
(72) Which,if any,of the following items has no effect on the stock basis of an S corporation shareholder?
(Multiple Choice)
5.0/5 (60)
(60) An S corporation cannot be a shareholder in another corporation.
(True/False)
5.0/5 (78)
(78) What method is used to allocate S corporation income or losses (unless an election to the contrary is made)?
(Multiple Choice)
4.9/5 (86)
(86) A termination occurs on the day that a corporation ____________________ to be an S corporation.
(Short Answer)
4.8/5 (69)
(69) Which statement is incorrect with respect to the number-of-shareholders test in filing an S election?
(Multiple Choice)
4.8/5 (83)
(83) The liquidation of C and S corporations is taxed in the same way.
(True/False)
4.9/5 (82)
(82) An S corporation shareholder's stock basis includes his or her direct investments plus a ratable share of any corporate liabilities.
(True/False)
4.8/5 (92)
(92) Compensation for services rendered to an S corporation is subject to FICA taxes.
(True/False)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)