



 Chat with AI
Exam 22: S Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law195 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Computing the Tax187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: in General146 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses95 Questions
Exam 8: Depreciation, cost Recovery, amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses181 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions105 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Tax Credits and Payments118 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, basis Considerations, and Nontaxable Exchanges280 Questions
Exam 14: Property Transactions, capital Gains and Losses, sec1231, and Recapture Provisions145 Questions
Exam 15: Alternative Minimum Tax132 Questions
Exam 16: Accounting Periods and Methods91 Questions
Exam 17: Corporations: Introduction and Operating Rules112 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation192 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganization72 Questions
Exam 21: Partnerships163 Questions
Exam 22: S Corporations145 Questions
Exam 23: Exempt Entities141 Questions
Exam 24: Multistate Corporate Taxation196 Questions
Exam 25: Taxation of International Transactions164 Questions
Exam 26: Tax Practice and Ethics183 Questions
Exam 27: The Federal Gift and Estate Taxes167 Questions
Exam 28: Income Taxation of Trusts and Estates167 Questions
Select questions type


Which,if any,of the following items has no effect on the stock basis of an S corporation shareholder?
(Multiple Choice)
4.7/5  (79)
(79) Pepper,Inc.,an S corporation in Norfolk,Virginia,has revenues of $400,000,taxable interest of $380,000,operating expenses of $250,000,and deductions attributable to the interest income of $140,000.Calculate any passive investment income penalty tax payable by this corporation.
(Essay)
4.8/5 (67)
(67) The carryover period for the NOLs of a C corporation does not continue to run during S corporation years.
(True/False)
4.8/5 (73)
(73) Mock Corporation converts to S corporation status in 2018.Mock used the LIFO inventory method in 2017 and had a LIFO inventory of $435,000 (FIFO value of $550,000) on the date of the S election.How much tax must be added to Mock's 2017 corporate tax liability,assuming that Mock is subject to a 35% tax rate.
(Multiple Choice)
4.8/5 (75)
(75) Form 1120S provides an S shareholder's computation of his or her stock basis.
(True/False)
4.9/5 (75)
(75) Which,if any,of the following can be eligible shareholders of an S corporation?
(Multiple Choice)
4.7/5 (81)
(81) An S corporation is limited to a theoretical maximum of ____________________ shareholders.
(Short Answer)
4.7/5 (74)
(74) Samantha owned 1,000 shares in Evita,Inc.,an S corporation,that uses the calendar year.On October 11,Samantha sells all of her Evita stock.Her stock basis at the beginning of the tax year was $60,000.Evita's ordinary income for the year was $22,000,and she receives a distribution of $35,000 on May 3rd.Her stock basis at the time of the sale is:
(Multiple Choice)
4.8/5 (85)
(85) The LIFO recapture tax is a variation of the passive investment income penalty tax.
(True/False)
4.9/5 (75)
(75) S corporations are treated as partnerships under state property laws.
(True/False)
4.9/5 (74)
(74) You are a 60% owner of an S corporation.Calculate your ending stock basis,based upon these facts.
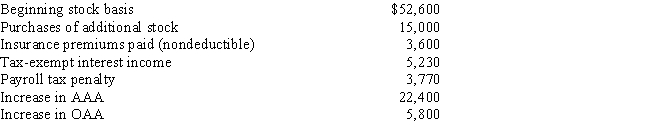
(Essay)
4.9/5 (79)
(79) The AAA begins with a zero balance on the first day of an S corporation's first tax year.
(True/False)
4.7/5 (67)
(67) You are given the following facts about a 50% owner of an S corporation.Compute her ending stock basis.
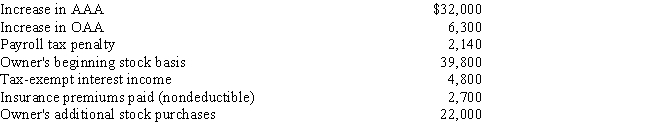
(Multiple Choice)
4.9/5 (76)
(76) On January 2,2016,David loans his S corporation $10,000.By the end of 2016 David's stock basis is zero and the basis in his note has been reduced to $8,000.During 2017,the company's operating income is $10,000.The company makes 2017 distributions to David of $11,000.David reports a(n):
(Multiple Choice)
4.8/5 (71)
(71) Tax-exempt income is not separately stated on Schedule K of Form 1120S.
(True/False)
4.7/5 (81)
(81) A former spouse is treated as being in the same family as the individual to whom he or she was married,for purposes of determining the number of S corporation shareholders.
(True/False)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)