



 Chat with AI
Exam 18: Evaluation of Portfolio Performance

Exam 1: The Investment Setting72 Questions
Exam 1: The Investment Setting: Part A6 Questions
Exam 2: Asset Allocation and Security Selection77 Questions
Exam 2: Asset Allocation and Security Selection: Part A3 Questions
Exam 3: Organization and Functioning of Securities Markets87 Questions
Exam 4: Security Market Indexes and Index Funds89 Questions
Exam 5: Efficient Capital Markets, Behavioral Finance, and Technical Analysis162 Questions
Exam 6: An Introduction to Portfolio Management114 Questions
Exam 6: An Introduction to Portfolio Management: Part A2 Questions
Exam 6: An Introduction to Portfolio Management: Part B2 Questions
Exam 7: Asset Pricing Models152 Questions
Exam 8: Equity Valuation83 Questions
Exam 9: The Top-Down Approach to Market, Industry, and Company Analysis216 Questions
Exam 10: The Practice of Fundamental Investing60 Questions
Exam 11: Equity Portfolio Management Strategies65 Questions
Exam 12: Bond Fundamentals and Valuation138 Questions
Exam 13: Bond Analysis and Portfolio Management Strategies125 Questions
Exam 14: An Introduction to Derivative Markets and Securities102 Questions
Exam 15: Forward, Futures, and Swap Contracts148 Questions
Exam 16: Option Contracts122 Questions
Exam 17: Professional Money Management, Alternative Assets, and Industry Ethics109 Questions
Exam 18: Evaluation of Portfolio Performance111 Questions
Select questions type


According to Global Investment Performance Standards (GIPS), time-weighted rates of return must be used.
(True/False)
4.9/5  (69)
(69) The information ratio permits only relative assessments of performance for different portfolios in a style class.
(True/False)
4.9/5 (76)
(76) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Consider the following information for four portfolios, the market, and the risk-free rate (RFR):
 -Refer to Exhibit 18.6. Calculate the Sharpe Measure for each portfolio.
 (Multiple Choice)
4.8/5 (83)
(83) The portfolio performance measure that can be most affected by a benchmark error is the Sharpe measure.
(True/False)
4.8/5 (84)
(84) Global Investment Performance Standards (GIPS), were intended to accomplish which of the following goals?
(Multiple Choice)
4.9/5 (82)
(82) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
The last year's performance for four mutual funds is presented below. The market return was 10.70 percent, the standard deviation was 13.1 percent last year, and the risk-free rate of return was 5%.
 -Refer to Exhibit 18.7. Based on the Treynor Measure, which portfolio preformed best?
 (Multiple Choice)
4.8/5 (78)
(78) The two questions when assessing the performance measurement of an investment manager include:
(Multiple Choice)
4.7/5 (66)
(66) When applying the Jensen's alpha measure, the alpha level and significance can vary greatly depending on the specification of the return-generating model.
(True/False)
4.8/5 (80)
(80) Which of the following statements concerning performance measures is false?
(Multiple Choice)
4.8/5 (92)
(92) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Consider the data presented below on three mutual funds and the market.
 -Refer to Exhibit 18.3. Compute the Treynor Measure for the CCC fund.
 (Multiple Choice)
4.8/5 (77)
(77) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
The data presented below has been collected at this point in time.
 -Refer to Exhibit 18.4. Compute the Jensen Measure for the BBB fund.
 (Multiple Choice)
4.7/5 (68)
(68) In the evaluation of bond portfolio performance, the analysis effect refers to
(Multiple Choice)
4.9/5 (81)
(81) The ranking differences between the Sharpe, Treynor, and Jensen performance measures occur because of the differences in diversification.
(True/False)
4.8/5 (78)
(78) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
The last year's performance for four mutual funds is presented below. The market return was 10.70 percent, the standard deviation was 13.1 percent last year, and the risk-free rate of return was 5%.
-Refer to Exhibit 18.7. Compute the Jensen Measure for the B fund.
-Refer to Exhibit 18.7. Compute the Jensen Measure for the B fund. (Multiple Choice)
4.9/5 (77)
(77) Overall performance is the total return above the risk-free rate.
(True/False)
4.9/5 (83)
(83) A portfolio manager has the following sequence of cash flows over a two-year period: 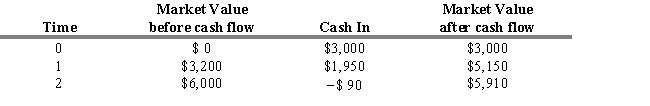 Calculate the portfolio manager's time weighted return.
 (Multiple Choice)
4.9/5 (78)
(78) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Given the following information evaluate the performance of Cloud Incorporated (CI).
 -Refer to Exhibit 18.9. Calculate CI's selectivity.
 (Multiple Choice)
4.8/5 (67)
(67) Under the performance attribution analysis method, the ____ measures the manager's ability to form specific market segment portfolios that generate superior returns relative to the way in which the comparable market segment is defined in the benchmark portfolio weighted by the manager's actual market segment investment proportions.
(Multiple Choice)
4.8/5 (81)
(81) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
An analyst is considering investing in funds A, B, C, and D. The market portfolio, M, is expected to be 11 percent next period, and the risk-free rate of return is 3 percent. The market portfolio had a standard deviation over the past ten years of 0.20. The analyst gathered the following information on the four funds.
 -Refer to Exhibit 18.8. Rank the four funds and market portfolio in order from highest to lowest based on their Treynor performance measures.
 (Multiple Choice)
4.7/5 (83)
(83) The advantage of evaluating a fund's alpha using a multifactor approach is that it is designed to control for market style (SMB and HML) and momentum (MOM) risk.
(True/False)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)