Multiple Choice
USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Consider the following information for four portfolios, the market, and the risk-free rate (RFR) :
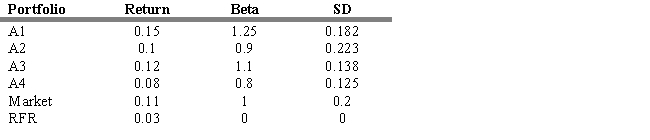
-Refer to Exhibit 18.6. Calculate the Sharpe Measure for each portfolio.
A) A1 = 0.40, A2 = 0.31, A3 = 0.65, A4 = 0.66
B) A1 = 0.31, A2 = 0.66, A3 = 0.65, A4 = 0.40
C) A1 = 0.66, A2 = 0.65, A3 = 0.31, A4 = 0.40
D) A1 = 0.66, A2 = 0.31, A3 = 0.65, A4 = 0.40
E) A1 = 0.54, A2 = 0.68, A3 = 0.65, A4 = 0.40
Correct Answer:

Verified
Correct Answer:
Verified
Q58: Normal portfolios, which are customized benchmarks that
Q59: The typical proxy for the market portfolio
Q60: The policy effect is a difference in
Q61: According to Global Investment Performance Standards (GIPS),
Q62: The information ratio permits only relative assessments
Q64: The portfolio performance measure that can be
Q65: Global Investment Performance Standards (GIPS), were intended
Q66: USE THE INFORMATION BELOW FOR THE FOLLOWING
Q67: The two questions when assessing the performance
Q68: When applying the Jensen's alpha measure, the