



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


Flint Corporation is subject to a corporate income tax only in State X.The starting point in computing X taxable income is Federal taxable income.Flint's Federal taxable income is $750,000,which includes a $50,000 deduction for state income taxes.During the year,Flint received $10,000 interest on Federal obligations.X tax law does not allow a deduction for state income tax payments. Flint's taxable income for X purposes is:
(Multiple Choice)
4.8/5  (90)
(90) A typical state taxable income addition modification is for the Federal income tax paid for the period.
(True/False)
5.0/5 (81)
(81) Typically,corporate income taxes constitute about 20 percent of a state's tax collections.
(True/False)
5.0/5 (80)
(80) Bert Corporation,a calendar-year taxpayer,owns property in States M and O.Both M and O require that the average value of assets be included in the property factor.M requires that the property be valued at its historical cost,and O requires that the property be included in the property factor at its net depreciated book value. 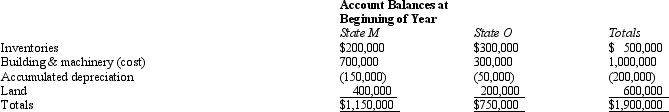
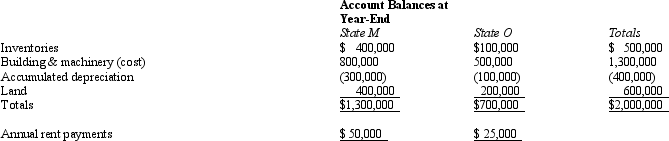 Bert's M property factor is:
 (Multiple Choice)
4.8/5 (83)
(83) Which of the following is not immune from state income taxation,even if P.L.86-272 is in effect?
(Multiple Choice)
4.8/5 (80)
(80) Norman Corporation owns and operates two manufacturing facilities,one in State X and the other in State Y.Due to a temporary decline in the corporation's sales,Norman has rented 20% of its Y facility to an unaffiliated corporation.Norman generated $1,000,000 net rental income and $2,000,000 income from manufacturing. Norman is incorporated in Y.For X and Y purposes,rental income is classified as allocable nonbusiness income.By applying the statutes of each state,Norman determined that its apportionment factors are .65 for X and .35 for Y.
Norman's income attributed to X is:
(Multiple Choice)
4.8/5 (84)
(84) Double weighting the sales factor effectively increases the tax burden on taxpayers based in the state,such as corporations with in-state headquarters.
(True/False)
4.9/5 (75)
(75) State Q has adopted sales-factor-only apportionment for its corporate income tax.As a result,a ____________________ (larger/smaller)percentage of an out-of-state corporation's income is assigned to tax in the state.
(Short Answer)
4.9/5 (77)
(77) Hermann Corporation is based in State A (corporate income tax rate 10%).It sells its goods to customers in both A and State B (corporate income tax rate 4%).Hermann's state taxable income for the year is $1 million,30% of which relates to B customers.Hermann's level of activities in B is insufficient to create nexus there,but A has adopted a throwback rule as to multistate sales.Would Hermann reduce its total state income tax liability by creating nexus with B,say by allowing its sales force to make credit decisions? Elaborate.
(Essay)
4.9/5 (84)
(84) In determining a corporation's taxable income for state income tax purposes,which of the following does not constitute a subtraction from Federal income?
(Multiple Choice)
4.9/5 (67)
(67) José Corporation realized $600,000 taxable income from the sales of its products in States X and Z.José's activities in both states establish nexus for income tax purposes.José's sales,payroll,and property among the states include the following.  Z utilizes a double-weighted sales factor in its three-factor apportionment formula.How much of José's taxable income is apportioned to Z?
 (Multiple Choice)
4.8/5 (76)
(76) Hambone Corporation is subject to the State E capital stock tax.The tax is levied at 2% of the entity's net worth that is apportioned to E.Hambone conducts 30% of its operations in E.Hambone's current book balance sheet is as follows,with amounts in millions.Compute Hambone's liability for the E capital stock tax.
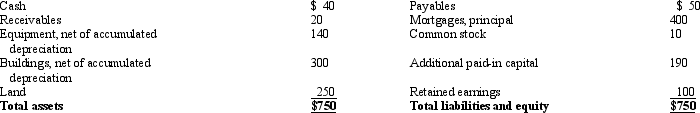
(Essay)
4.8/5 (85)
(85) Perez Corporation is subject to tax only in State A.Perez generated the following income and deductions.  Federal taxable income is the starting point in computing A taxable income.State income taxes are not deductible for A tax purposes.Perez's A taxable income is:
(Multiple Choice)
4.8/5 (89)
(89) Politicians frequently use tax credits and exemptions to create economic development incentives.
(True/False)
4.8/5 (74)
(74) Hopper Corporation's property holdings in State E are as follows. 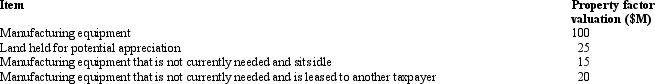 Compute the numerator of Hopper's E property factor.
 (Multiple Choice)
4.8/5 (93)
(93) A state sales/use tax is designed to be collected by the ____________________ (seller/purchaser)of the product and then remitted to the state.
(Short Answer)
4.9/5 (91)
(91) The sales/use tax that is employed by most U.S.states does not fall on all retail transactions.Identify at least five sales/use tax exemptions that states often allow,eliminating certain transactions from the tax base.
(Essay)
4.8/5 (97)
(97) For most taxpayers,which of the traditional apportionment factors yields the greatest opportunities for tax reduction?
(Multiple Choice)
5.0/5 (65)
(65) In most states,Federal S corporations must make a separate state-level election of the flow-through status.
(True/False)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)