



 Chat with AI
Exam 7: Corporations: Reorganizations

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


The acquiring corporation in a "Type G" reorganization must reduce the tax attributes carried over to it to the extent of the ____________________ relief.
(Short Answer)
4.8/5  (78)
(78) Liabilities generally are not considered boot in corporate reorganizations except in an acquisitive "Type D" when cash or other property is also used in the transaction.
(True/False)
4.7/5 (90)
(90) In corporate reorganizations,an acquiring corporation using property other than stock as consideration may recognize gains but not losses on the transaction.
(True/False)
4.9/5 (83)
(83) When a corporation has cancellation-of-debt relief in a "Type G" reorganization,the corporation reduces its benefits in tax attributes such as NOLs and business credits.
(True/False)
4.9/5 (91)
(91) Winner Corporation acquires all of Loser Corporation on January 1 of this year for $1 million when the Federal long-term tax-exempt rate was 4%.Two of the tax attributes that Winner found appealing are Loser's NOL of $100,000 and its negative E & P of $150,000.Before applying any of Loser's tax benefits,Winner has taxable income of $75,000 and E & P of $50,000.Winner pays a dividend of $100,000 to its shareholders.Assuming that taxable income is equal to the current year's E & P,how much of this dividend is taxable?
(Multiple Choice)
4.7/5 (86)
(86) In a ____________________ divisive reorganization,some of the stock in the original entity is exchanged for stock in the new corporation.In a ____________________ divisive reorganization,the shareholders do not give up any of their original corporation stock to receive stock in the new corporation,whereas in a ____________________ divisive reorganization,the original distributing corporation disappears.
(Short Answer)
4.8/5 (79)
(79) On March 1,Cream Corporation transfers all of its assets to Coffee Corporation in exchange for 10% of its common voting stock.At the time of the reorganization,Cream has assets valued at $4 million (basis of $3 million)and its earnings and profits account shows a deficit of $650,000.Coffee's earnings and profits as of March 1 were $420,000.Due to the reorganization,Coffee has an NOL for the current year of $150,000.Coffee still declares its usual dividends of $100,000,paid on April 30,August 31,and December 31 ($300,000 of total dividends).
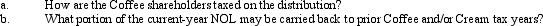
(Essay)
4.9/5 (80)
(80) Mars Corporation merges into Jupiter Corporation by exchanging all of its assets for 300,000 shares of Jupiter stock valued at $2 per share and $100,000 cash.Wanda,the sole shareholder of Mars,surrenders her Mars stock (basis $900,000)and receives all of the Jupiter stock transferred to Mars plus the $100,000.How does Wanda treat this transaction on her tax return?
(Multiple Choice)
4.8/5 (85)
(85) The amount of gain recognized by a shareholder in a corporate reorganization is based on the shareholder's proportionate share of E & P.
(True/False)
4.8/5 (88)
(88) Lyon has 100,000 shares outstanding that are worth $10 per share.It uses 32% of its stock plus $80,000 to acquire Zebra Corporation in a "Type A" reorganization.Zebra's assets are valued at $400,000 and its accumulated earnings and profits are $25,000 at the time of the reorganization.The Lyon shares and cash are distributed to the Zebra shareholders as follows.Jake (owning 62.5% of Zebra)receives 18,000 shares (value $180,000)and $70,000.Kara (owning 37.5% of Zebra)receives 14,000 shares (value $140,000)and $10,000.Jake and Kara each recognize gains to the extent of the cash they received.What is the character of Jake's and Kara's gains?
(Essay)
4.8/5 (78)
(78) The sound business purpose doctrine and § 269 have the same purpose of disallowing restructurings that are primarily for tax avoidance motives.
(True/False)
4.9/5 (76)
(76) In which type of reorganization could bonds and other liabilities be exchanged for stock and not be treated as boot?
(Multiple Choice)
4.7/5 (79)
(79) An equity structure shift occurs when a(n)____________________ causes an ownership change of ____________________ percentage-points for any common shareholders owning at least 5%.A sale or issuance of stock can cause a(n)____________________ to take place.
(Short Answer)
5.0/5 (81)
(81) Burmese Corporation is interested in acquiring Javanese Corporation by transferring 30% of its stock for all of Javanese's assets valued at $500,000 (basis of $150,000)and its $200,000 of liabilities.Javanese has created $50,000 in general business research credits which it cannot use.Javanese concentrates on pharmaceutical research whereas Burmese manufactures sun glasses.Burmese uses a discount factor of 8% and the Federal applicable rate is 4%.Javanese will terminate after the restructuring.How will this transaction be treated for tax purposes?
(Multiple Choice)
4.8/5 (77)
(77) Without evidence to the contrary,the IRS views transactions occurring within one year of a reorganization as part of the restructuring.
(True/False)
4.9/5 (81)
(81) The determination of whether a shareholder's gain qualifies for stock redemption treatment in a corporate reorganization is based on the reduction in the percentage of the stock held in the target corporation when compared to the percentage held in the acquiring corporation.
(True/False)
4.7/5 (96)
(96) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)