



 Chat with AI
Exam 9: Profit Maximization in Perfectly Competitive Markets

Exam 1: An Introduction to Microeconomics72 Questions
Exam 2: Supply and Demand97 Questions
Exam 3: The Theory of Consumer Choice97 Questions
Exam 4: Individual and Market Demand99 Questions
Exam 5: Using Consumer Choice Theory75 Questions
Exam 6: Exchange, Efficiency, and Prices82 Questions
Exam 7: Production112 Questions
Exam 8: The Cost of Production121 Questions
Exam 9: Profit Maximization in Perfectly Competitive Markets99 Questions
Exam 10: Using the Competitive Model82 Questions
Exam 11: Monopoly115 Questions
Exam 12: Product Pricing With Monopoly Power88 Questions
Exam 13: Monopolistic Competition and Oligopoly98 Questions
Exam 14: Game Theory and the Economics of Information88 Questions
Exam 15: Using Noncompetitive Market Models77 Questions
Exam 16: Employment and Pricing of Inputs100 Questions
Exam 17: Wages, Rent, Interest, and Profit92 Questions
Exam 18: Using Input Market Analysis83 Questions
Exam 19: General Equilibrium Analysis and Economic Efficiency93 Questions
Exam 20: Public Goods and Externalities101 Questions
Select questions type


Answer the following:
a)Assume that the gold-mining industry is perfectly competitive.On the diagrams below,illustrate the long-run equilibrium in the overall gold market and for a representative gold mine.Draw the industry supply and demand curves as well as the firm's marginal cost curve.Indicate the equilibrium prices and quantities in both markets (at the industry-level and at the firm-level).
b)Assume an increase in the demand for jewelry causes a surge in the demand for gold.Using your diagrams,show what happens in the short-run to the gold market and to each existing gold mine.Specifically,are individual firms earning positive,negative,or zero economic profits? Indicate their profit on your graph.
c)If the demand for gold remains high,what would happen to the price over time? Specifically,would the new long-run equilibrium price be above,below,or equal to the short-run equilibrium price in part (b)? What causes this change in price,if any?
d)Would the new long-run equilibrium price be above,below,or equal to the original long-run equilibrium price? That is,as you've drawn it,is the long-run supply curve in the gold industry upward-sloping,horizontal,or downward-sloping? Explain why it would have this shape.
(Essay)
4.8/5  (68)
(68) The perfectly competitive firm's demand curve is horizontal because:
(Multiple Choice)
4.8/5 (81)
(81) Use the following figure to answer the question : Figure 9-1 : shows the total cost and total revenue for a firm when it prices its products at $8 and $10.
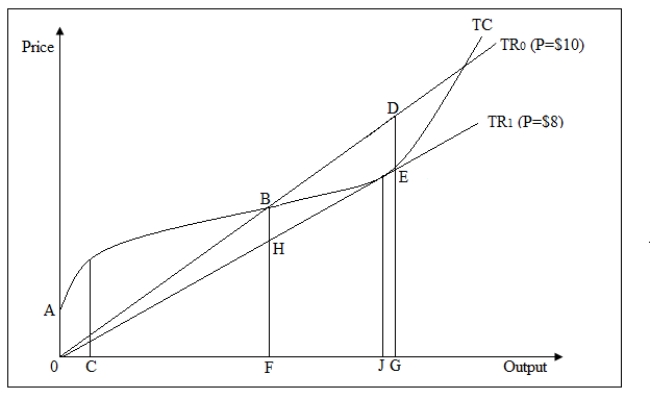 -Refer to Figure 9-1.At a price of $10,the profit maximizing level of output for the firm is _____.
 (Multiple Choice)
4.8/5 (68)
(68) Resources are not free to move into and out of an industry when:
(Multiple Choice)
4.7/5 (89)
(89) In the long-run,firms in a competitive industry earn only a normal rate of return because:
(Multiple Choice)
4.8/5 (89)
(89) A competitive firm maximizes profit at the output level where:
(Multiple Choice)
4.8/5 (83)
(83) A perfectly competitive firm is a price taker.This implies that:
(Multiple Choice)
4.8/5 (77)
(77) The demand for corn has increased over the past few decades to satisfy the increasing demand from the food and ethanol industries.The primary beneficiaries of an expansion in the output of corn are owners of farmland suitable for corn production.What can you conclude about the nature of the corn industry?
(Multiple Choice)
4.8/5 (79)
(79) The competitive firm maximizes its profit by operating at the point where _____ and price is greater than average variable cost.
(Multiple Choice)
4.8/5 (86)
(86) The demand curve of a perfectly competitive firm is determined by:
(Multiple Choice)
4.8/5 (81)
(81) Which of the following will reduce the competitive nature of the agricultural industry?
(Multiple Choice)
4.9/5 (65)
(65) Use the following figure to answer the question : Figure 9-3 : shows the marginal cost curve,average total cost curve,average variable cost curve,and marginal revenue curve for a firm for different levels of output. 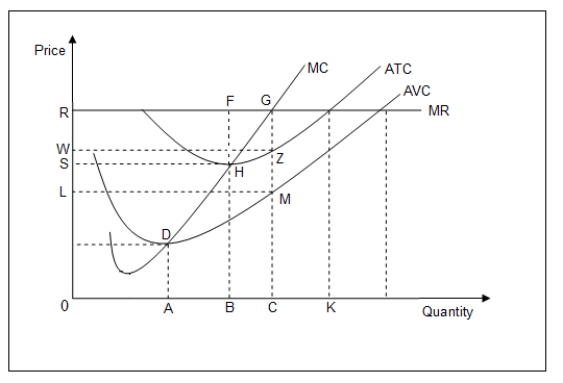 -Refer to Figure 9-3.At the output level OC,average fixed cost is equal to _____.
 (Multiple Choice)
4.9/5 (74)
(74) Which of the following will occur in response to an unexpected increase in demand in a constant-cost,competitive industry?
(Multiple Choice)
4.8/5 (80)
(80) Assume that labor is the variable input for a firm.Which of the following will occur if the wage rate increases?
(Multiple Choice)
4.8/5 (71)
(71) A profit-maximizing firm expands output until marginal revenue equals the _____ of producing the last unit.
(Multiple Choice)
4.9/5 (88)
(88) The short-run supply curve for a competitive industry is upward-sloping because:
(Multiple Choice)
4.9/5 (80)
(80) Firms in an industry are unlikely to have pricing power if:
(Multiple Choice)
4.8/5 (83)
(83) Use the following figure to answer the question : Figure 9-3 : shows the marginal cost curve,average total cost curve,average variable cost curve,and marginal revenue curve for a firm for different levels of output.
-At the output level of OC in Figure 9-3,average profit per unit of output is equal to _____.
-At the output level of OC in Figure 9-3,average profit per unit of output is equal to _____. (Multiple Choice)
4.8/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)