



 Chat with AI
Exam 9: Profit Maximization in Perfectly Competitive Markets

Exam 1: An Introduction to Microeconomics72 Questions
Exam 2: Supply and Demand97 Questions
Exam 3: The Theory of Consumer Choice97 Questions
Exam 4: Individual and Market Demand99 Questions
Exam 5: Using Consumer Choice Theory75 Questions
Exam 6: Exchange, Efficiency, and Prices82 Questions
Exam 7: Production112 Questions
Exam 8: The Cost of Production121 Questions
Exam 9: Profit Maximization in Perfectly Competitive Markets99 Questions
Exam 10: Using the Competitive Model82 Questions
Exam 11: Monopoly115 Questions
Exam 12: Product Pricing With Monopoly Power88 Questions
Exam 13: Monopolistic Competition and Oligopoly98 Questions
Exam 14: Game Theory and the Economics of Information88 Questions
Exam 15: Using Noncompetitive Market Models77 Questions
Exam 16: Employment and Pricing of Inputs100 Questions
Exam 17: Wages, Rent, Interest, and Profit92 Questions
Exam 18: Using Input Market Analysis83 Questions
Exam 19: General Equilibrium Analysis and Economic Efficiency93 Questions
Exam 20: Public Goods and Externalities101 Questions
Select questions type


Which of the following is an assumption in the model of perfect competition?
(Multiple Choice)
4.9/5  (86)
(86) Use the following figure to answer the question : Figure 9-1 : shows the total cost and total revenue for a firm when it prices its products at $8 and $10.
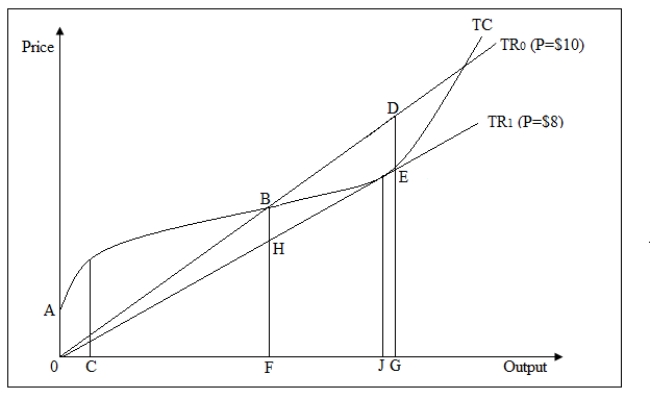 -In Figure 9-1,if the market price fell to $8 the firm would:
 (Multiple Choice)
5.0/5 (80)
(80) The long-run cost function faced by each producer in a perfectly competitive industry is given by: MC(Q)= 20 - 6Q + Q2.The corresponding long-run average cost function is AC(Q)= 20 - 3Q + Q2/3.The market demand curve for the product is D(P)= 1100 - 50P.
a)What is the long-run equilibrium price in this industry? At this price,how much would an individual firm produce?
(Essay)
4.9/5 (77)
(77) In the short-run,if the price falls,the firm will respond by:
(Multiple Choice)
4.9/5 (84)
(84) Use the following figure to answer the question : Figure 9-3 : shows the marginal cost curve,average total cost curve,average variable cost curve,and marginal revenue curve for a firm for different levels of output. 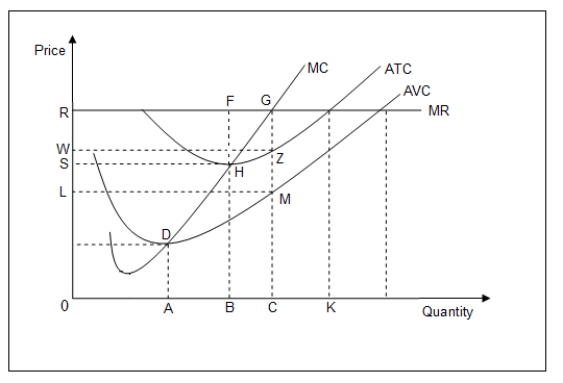 -Refer to Figure 9-3.If the market price is $10,average revenue _____.
 (Multiple Choice)
5.0/5 (70)
(70) The supply curve of a competitive firm in the short-run is:
(Multiple Choice)
4.9/5 (90)
(90) Consider a perfectly competitive firm facing the following conditions: TR = 150Q and
TC = 500 + 3Q + Q2.What is the firm's profit maximizing output?
(Multiple Choice)
4.7/5 (83)
(83) Which one of the following is not an assumption of the competitive model?
(Multiple Choice)
4.8/5 (84)
(84) Use the following figure to answer the question : Figure 9-3 : shows the marginal cost curve,average total cost curve,average variable cost curve,and marginal revenue curve for a firm for different levels of output.
-Refer to Figure 9-3.At the profit-maximizing level of output:
-Refer to Figure 9-3.At the profit-maximizing level of output: (Multiple Choice)
5.0/5 (86)
(86) Use the following figure to answer the question : Figure 9-4 : shows the marginal cost curve,the average cost curve,the average variable cost curve,and the demand curve for a firm over different levels of output.The market price is $P. 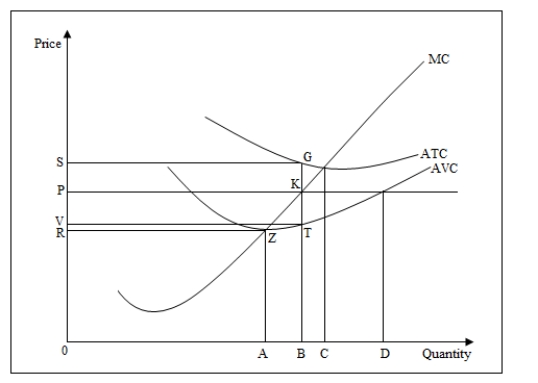 -Refer to Figure 9-4.If the firm chooses to shut down when the market price is $P,what is the loss it would incur?
 (Multiple Choice)
4.8/5 (78)
(78) Abe's Taxi Company operates in a perfectly competitive market.Gasoline is a variable input in the taxi services industry.As the price of gasoline decreases,the short-run marginal cost curve for Abe's Taxi Company:
(Multiple Choice)
4.9/5 (78)
(78) Consider a perfectly competitive firm facing the following conditions: TR = 150Q and
TC = 500 + 3Q + Q2.What is the firm's marginal cost when Q = 50?
(Multiple Choice)
4.8/5 (75)
(75) The short-run supply curve for a perfectly competitive industry:
(Multiple Choice)
4.7/5 (74)
(74) A significant decrease in the price of a variable input causes the:
(Multiple Choice)
4.9/5 (73)
(73) Use the following figure to answer the question : Figure 9-4 : shows the marginal cost curve,the average cost curve,the average variable cost curve,and the demand curve for a firm over different levels of output.The market price is $P.
-Refer to Figure 9-4.At a price of $P,the firm will produce the output level _____.
-Refer to Figure 9-4.At a price of $P,the firm will produce the output level _____. (Multiple Choice)
4.8/5 (86)
(86) Assume that coffee shops operate in a perfectly competitive industry.A single coffee shop,Brick & Mortar,decides to charge an entrance fee in addition to charges for its coffee and pastry.Which of the following is most likely to happen?
(Multiple Choice)
4.9/5 (71)
(71) At the profit maximizing level of output in a competitive industry,the firm is:
(Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)