



 Chat with AI
Exam 22: Capital Budgeting: a Closer Look

Exam 1: The Accountants Vital Role in Decision Making141 Questions
Exam 2: An Introduction to Cost Terms and Purposes165 Questions
Exam 3: Cost-Volume-Profit Analysis139 Questions
Exam 4: Job Costing138 Questions
Exam 5: Activity-Based Costing and Management133 Questions
Exam 6: Master Budget and Responsibility Accounting150 Questions
Exam 7: Flexible Budgets, Variances, and Management Control: I146 Questions
Exam 8: Flexible Budgets, Variances, and Management Control: II137 Questions
Exam 9: Income Effects of Denominator Level on Inventory Valuation154 Questions
Exam 10: Quantitative Analyses of Cost Functions114 Questions
Exam 11: Decision Making and Relevant Information146 Questions
Exam 12: Pricing Decisions, Product Profitability Decisions, and Cost Management135 Questions
Exam 13: Strategy, Balanced Scorecard, and Profitability Analysis140 Questions
Exam 14: Period Cost Allocation153 Questions
Exam 15: Cost Allocation: Joint Products and Byproducts149 Questions
Exam 16: Revenue and Customer Profitability Analysis137 Questions
Exam 17: Process Costing128 Questions
Exam 18: Spoilage, Rework, and Scrap121 Questions
Exam 19: Cost Management: Quality, Time, and the Theory of Constraints158 Questions
Exam 20: Inventory Cost Management Strategies136 Questions
Exam 21: Capital Budgeting: Methods of Investment Analysis128 Questions
Exam 22: Capital Budgeting: a Closer Look120 Questions
Exam 23: Transfer Pricing and Multinational Management Control Systems141 Questions
Exam 24: Multinational Performance Measurement and Compensation139 Questions
Select questions type


For Years 1 through 6 Better Products Ltd. had annual net income of $20,000, CCA of $40,000 each year, a 40 percent tax rate, a discount rate of 10 percent and annual cash sales of $200,000. The depreciable assets of Better Products belong in several different classes under the Income tax Act, have a salvage value of zero at the end of six years, and were all bought new at the beginning of Year 1. The present value factors, in simplified form, for 10 percent are:
 -Biermann Equipment is a publicly held corporation required to pay income taxes. For the current year it had revenues of $5,000,000 and cash expenses of $3,000,000, and claimed CCA of $200,000. The company has a 30 percent tax rate. What would be the net cash flow for the current year if all revenues were received in cash?
 (Multiple Choice)
4.9/5  (88)
(88) Use the information below to answer the following question(s).
Barry operates a shop in a resort in an area known for its high inflation rate. The inflation rate for the last few years has been averaging 3 percent a month. His long-term real rate of return is 12 percent, or 1 percent a month. On April 1 he anticipates that real dollar sales during the summer will be as follows:
 -What will Barry's sales figures be for each month, respectively, assuming the owner uses the real rate approach?
 (Multiple Choice)
4.7/5 (82)
(82) Clock Manufacturing Company purchased a new piece of equipment at a cost of $60,000 at the beginning of the year. For tax purposes the machine is a Class 8 asset (20% declining balance). The company has a 34 percent income tax rate. Assume that the company has no other Class 8 assets during the period.
Required:
a. Compute the amount of tax savings from CCA for the first three years.
b. Compute the amount of tax savings from CCA for the first three years using a required rate of return of 12 percent.
(Essay)
4.9/5 (83)
(83) Headwaters Ltd. is considering purchasing a new asset. It has a cost of $1,350,000, an expected 6 year life and a salvage value of $90,000. The equipment would qualify as a class 8 (20% CCA) asset and Headwaters has a required rate of return of 11% and an effective tax rate of 32%.
Required:
Calculate the tax shields that are generated from the purchase of this asset. Assume the asset will be placed in a pool and the pool will continue upon disposition. For tax purposes the disposition will occur on day 1 of Year 7. What is the net tax effect of the asset acquisition?
(Essay)
4.9/5 (91)
(91) Avilas Corp. has a marginal tax rate of 25%, and is considering the following two capital projects:
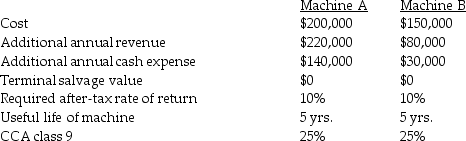 Additional data (for interest rate of 10%, 5 periods):
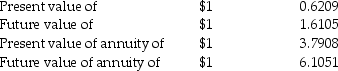 Required:
Which project has a higher net after-tax present value?
Additional data (for interest rate of 10%, 5 periods):
Required:
Which project has a higher net after-tax present value? (Essay)
5.0/5 (72)
(72) The real rate of return is the rate of return which deals with the inflation element.
(True/False)
4.9/5 (77)
(77) The NPV method always indicates the project or set of projects that maximizes the NPV of future cash flows.
(True/False)
4.9/5 (77)
(77) The acquisition cost of the assets in a class, minus the CCA claimed to date for that class, is referred to as the UCC of a particular class.
(True/False)
4.8/5 (77)
(77) For Years 1 through 6 Better Products Ltd. had annual net income of $20,000, CCA of $40,000 each year, a 40 percent tax rate, a discount rate of 10 percent and annual cash sales of $200,000. The depreciable assets of Better Products belong in several different classes under the Income tax Act, have a salvage value of zero at the end of six years, and were all bought new at the beginning of Year 1. The present value factors, in simplified form, for 10 percent are:
-What is the tax saving from CCA in each year?
-What is the tax saving from CCA in each year? (Multiple Choice)
4.8/5 (87)
(87) Good Bread Bakery installed an oven costing $100,000 on January 1 of the current year. Due to unexpected advances in technology, the equipment's value was reduced to $24,000 in only one week. The equipment is class 8 which has a CCA rate of 20% for tax purposes. The incremental costs of operating the oven over four years is $80,000 annually, excluding depreciation. A new replacement machine with all the new advances can be purchased now for $120,000. It also has a useful life of four years and can be operated for $30,000 a year, excluding depreciation. The company's tax rate is 40 percent. Neither oven has a salvage value at the end of the four years. Assume that the company will replace the oven (whichever one it chooses) after the four years.
Required:
a. Calculate the relevant cash flows using both a total project approach and a differential approach if the company's required rate of return is 10 percent.
b. What is the difference between the two methods?
(Essay)
4.9/5 (81)
(81) CCA reduces taxable income, and therefore reduces tax payments and increases the firm's cash flow.
(True/False)
4.9/5 (86)
(86) Which of the following are not considered in capital-budgeting?
(Multiple Choice)
4.9/5 (80)
(80) Wilf Company acquired an additional Class 10 (30% declining balance) asset for $60,000. The UCC at the beginning of the year was $100,000. CCA in the current year is
(Multiple Choice)
4.8/5 (89)
(89) The differential approach calculates the present value of all cash inflows and outflows under each alternative.
(True/False)
4.9/5 (93)
(93) Depreciation tax deductions result in tax savings that partially offset the cost of acquiring the capital asset.
(True/False)
4.8/5 (77)
(77) The total project approach calculates the future value of cash outflows and inflows that differ between the alternatives of using the old machine and replacing the old machine.
(True/False)
4.9/5 (74)
(74) A company purchased computer equipment that is Class 10 for Income Tax purposes (Class 10 is declining balance, but with a 30% rate). The company made the following two journal entries: 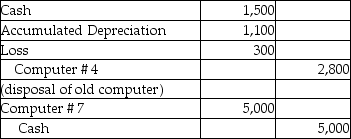 How is the $300 loss treated in discounted cash flow analysis?
 (Multiple Choice)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)