



 Chat with AI
Exam 18: Accounting Periods and Methods

Exam 1: An Introduction to Taxation and Understanding Federal Tax Law194 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Tax Formula and Tax Determination; an Overview of Property Transactions187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions114 Questions
Exam 6: Deductions and Losses: in General155 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses124 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses178 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Alternative Minimum Tax134 Questions
Exam 13: Tax Credits and Payment Procedures120 Questions
Exam 14: Property Transactions: Determination of Gain or Loss and Basis Considerations148 Questions
Exam 15: Property Transactions: Nontaxable Exchanges138 Questions
Exam 16: Property Transactions: Capital Gains and Losses78 Questions
Exam 17: Property Transactions: 1231 and Recapture Provisions74 Questions
Exam 18: Accounting Periods and Methods110 Questions
Exam 19: Deferred Compensation101 Questions
Exam 20: Corporations and Partnerships198 Questions
Select questions type


Robin Construction Company began a long-term contract in 2017. The contract price was $800,000. The estimated cost of the contract at the time it was begun was $500,000. The actual cost incurred in 2017 was $350,000. The contract was completed in 2018 and the cost incurred that year was $125,000. Under the percentage of completion method:

Free
(Multiple Choice)
4.9/5  (87)
(87) Correct Answer: Verified
E
Which of the following statements regarding the matching principle is correct?
Free
(Multiple Choice)
4.9/5 (94)
(94) Correct Answer:Verified
VerifiedC
The installment method can be used for which of the following sales with payments being made in the year following the year of sale?
Free
(Multiple Choice)
4.8/5 (85)
(85) Correct Answer:Verified
VerifiedB
The accrual method generally is required for the following types of businesses:
(Multiple Choice)
4.8/5 (80)
(80) Gold Corporation, Silver Corporation, and Copper Corporation are equal partners in the GSC Partnership. The partners' tax year-ends are as follows: 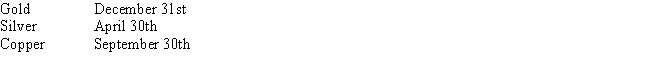
(Multiple Choice)
4.7/5 (73)
(73) A CPA practice that is incorporated earns 40% of its annual revenues in the months of March and April. Although the CPA practice is a professional services corporation (PSC), it may use a fiscal year ending April 30th.
(True/False)
4.8/5 (87)
(87) The lower of cost or market can be used in conjunction with both the FIFO and LIFO method.
(True/False)
5.0/5 (79)
(79) Alice, Inc., is an S corporation that has been in business for five years. Its annual gross receipts have never exceeded $1 million. The corporation operates a retail store and also owns rental property. The sales from the retail store and the rental income may be reported by the cash method, unless Alice previously elected the accrual method.
(True/False)
4.9/5 (73)
(73) Wendy sold property on the installment basis in 2015 for more than her basis in the property. Wendy was to receive installment payments at the end of each year for the next five years. In 2017, Wendy was killed in a car accident and the note was transferred to her estate.
(Multiple Choice)
4.7/5 (70)
(70) Kathy was a shareholder in Matrix, Inc., when she sold the corporation a commercial building. The building cost $500,000 and the balance in the accumulated depreciation account was $400,000. Matrix, Inc., paid $100,000 in the year of sale and gave Kathy a note for $400,000 plus adequate interest due in 2019.
(Multiple Choice)
5.0/5 (78)
(78) The taxpayer had consistently used the cash method of accounting even though inventories were a material income-producing factor to its business. The taxpayer decided to voluntarily change to the accrual method of accounting. The adjustment to income due to the change was that the correct beginning balances for the year of the change as follows: $60,000 for inventories, $30,000 for accounts receivable, and $12,000 for accounts payable. The adjustment due to the change in accounting method is:
(Multiple Choice)
4.9/5 (67)
(67) Andrew owns 100% of the stock of Crow's Farm Inc., an S corporation, that raises cattle and corn. The farm's annual gross receipts have never exceeded $3 million and the farm is not considered a tax shelter.
(Multiple Choice)
4.9/5 (77)
(77) The ability of the CPA to timely prepare a tax return is a justification for the partnership's use of a particular tax year.
(True/False)
5.0/5 (77)
(77) Computer Consultants Inc., began business as an adviser to chains of retail stores. The company assisted the stores in the selection of hardware and the development of software used by retail chain stores. Later the company developed software and sold it to its customers. The company also began selling some of the equipment to the customers. That is, the company would bid on a job to purchase and install equipment and the software. The company has consistently reported its income by the cash method. At the end of the year, the company has substantial accounts receivables from clients and a small amount of inventory on hand. What advice can you offer the company regarding its accounting method?
(Essay)
4.9/5 (78)
(78) In 2017, Father sold land to Son for $50,000 cash and an installment note for $150,000 due in 2021. Father's basis was $100,000. In 2018, after paying $8,000 interest but nothing on the principal, Son sold the land for $300,000 cash. What gain, if any, must Father recognize in 2018?
(Multiple Choice)
5.0/5 (75)
(75) Karen, an accrual basis taxpayer, sold goods in December 2017 for $20,000. The customer was unable to pay cash. So the customer gave Karen a note for $20,000 that was payable in April 2018. The note bore interest at the Federal rate. The fair market value of the note at the end of 2017 was $18,000. Karen collected $20,500 from the customer in April 2018, $20,000 principal plus $500 interest. Under the accrual method, Karen must recognize income of:
(Multiple Choice)
5.0/5 (77)
(77) Which of the following taxpayers is required to use the accrual method of accounting?
(Multiple Choice)
4.9/5 (72)
(72) Terry, Inc., makes gasoline storage tanks. All production is done under contract. The company makes three basic models, but each model must be adapted to customer specifications for the location of outlets, insulation, and paint. It takes from three to six months to complete a tank. How should Terry account for the income for the business?
(Essay)
4.8/5 (86)
(86) A calendar year, cash basis corporation began business on April 1, 2016, and paid $2,400 for a 24-month liability insurance policy. An accrual basis, calendar year taxpayer also began business on April 1, 2016, and purchased a 24-month liability insurance policy. The accrual basis taxpayer must amortize the premiums over 24 months but the cash basis taxpayer may deduct the total premiums in 2016.
(True/False)
4.9/5 (79)
(79) Ivory Fast Delivery Company, an accrual basis taxpayer, frequently has claims for damages to property the company delivered. Often the claim is not filed until a month after the delivery. In the past, approximately 80% of the claims are paid by Ivory. In 2017, claims for $80,000 were filed. The company refused to pay $20,000 of the claims (because they were not valid), and paid $50,000. The remaining $10,000 in claims were processed and paid in January 2018. Also, in January 2018, claims for $8,000 were filed for deliveries made in 2017, and $6,000 was paid on these claims by March 15, 2018. Ivory has not elected to use the recurring item exception to economic performance. Under the all-events and economic performance tests, Ivory can accrue as an expense for 2017:
(Multiple Choice)
4.8/5 (65)
(65) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)