



 Chat with AI
Exam 18: Accounting Periods and Methods

Exam 1: An Introduction to Taxation and Understanding Federal Tax Law194 Questions
Exam 2: Working With the Tax Law86 Questions
Exam 3: Tax Formula and Tax Determination; an Overview of Property Transactions187 Questions
Exam 4: Gross Income: Concepts and Inclusions124 Questions
Exam 5: Gross Income: Exclusions114 Questions
Exam 6: Deductions and Losses: in General155 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses124 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion103 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses178 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses111 Questions
Exam 12: Alternative Minimum Tax134 Questions
Exam 13: Tax Credits and Payment Procedures120 Questions
Exam 14: Property Transactions: Determination of Gain or Loss and Basis Considerations148 Questions
Exam 15: Property Transactions: Nontaxable Exchanges138 Questions
Exam 16: Property Transactions: Capital Gains and Losses78 Questions
Exam 17: Property Transactions: 1231 and Recapture Provisions74 Questions
Exam 18: Accounting Periods and Methods110 Questions
Exam 19: Deferred Compensation101 Questions
Exam 20: Corporations and Partnerships198 Questions
Select questions type


Charlotte sold her unincorporated business for $600,000 in 2017. The sales contract allocated $120,000 to equipment, $300,000 to land, and $180,000 to goodwill. Charlotte had a $0 basis in the goodwill, the land cost $150,000, and the equipment originally cost $250,000 but it was fully depreciated. What is the amount of the gain eligible for installment sales treatment?
(Multiple Choice)
4.9/5  (75)
(75) In 2016, Godfrey received a $50,000 sales commission on a long-term contract. But in 2017, the customer filed bankruptcy and Godfrey's employer was not able to collect from the customer. Under the bonus agreement, Godfrey was required to repay the employer $20,000 of the bonus. Godfrey was in the 35% marginal tax bracket in 2016 but he is in the 25% marginal tax bracket in 2017.
(Multiple Choice)
4.9/5 (78)
(78) Gray Company, a calendar year taxpayer, allows customers to return defective merchandise for a full refund within 30 days of the purchase. In 2017, the company refunded $400,000 for claims involving sales. The $400,000 consisted of $350,000 in refunds from 2017 sales and $50,000 in refunds from 2016 sales. All of the refunds from 2016 sales were for claims filed in 2016 and were paid in January and February 2017. At the end of 2017, the company had $12,000 in refund claims for sales in 2017 for which payment had been approved. These claims were paid in January 2017. Also in January 2017, the company received an additional $30,000 in claims for sales in 2017. This $30,000 was paid by Gray in February 2018. With respect to the above, Gray can deduct:
(Multiple Choice)
4.8/5 (83)
(83) Laura Corporation changed its tax year-end from July 31st to December 31st in 2016. The income for the period August 1, 2016 through December 31, 2016 was $35,000. The corporate tax rate is 15% on the first $50,000 of income, 25% on income from $50,001 to $75,000, and 34% on income from $75,001 to $100,000. A portion of Laura's June - December 2016 income will be taxed at 34%.
(True/False)
4.9/5 (96)
(96) For a taxpayer who is required to use the percentage of completion method, the taxpayer can elect to defer the recognition of income and the related costs until the taxable year in which cumulative contract costs are at least 10 percent of the estimated contract costs.
(True/False)
4.8/5 (89)
(89) Father sold land to Son for $500,000 in 2017. Father's basis in the land was $100,000. Son paid Father $50,000 and gave Father a note for $450,000 due in 2020. In 2018, Son sold the land for $600,000 cash. The note bore interest at the appropriate Federal rate and both Father and Son held the land as an investment.
(Multiple Choice)
4.9/5 (78)
(78) The accrual basis taxpayer sold land for $100,000 on December 31, 2017. He did not collect the $100,000 until January 2, 2018. The land was held as an investment.
(Multiple Choice)
4.8/5 (74)
(74) Ted, a cash basis taxpayer, received a $150,000 bonus in 2017 when he was in the 35% marginal tax bracket. In 2018, when Ted was in the 28% marginal tax bracket, it was discovered that the bonus was incorrectly computed, and Ted was required to refund $40,000 to his employer. As a result of the refund, Ted can reduce his 2018 tax liability by $14,000 (.35 × $40,000).
(True/False)
4.8/5 (81)
(81) Aspen stores is a large retail chain. The company has four warehouses that are located in various parts of the country. The goods are stored at the warehouses and then moved to the retail stores for sale.
(Multiple Choice)
4.8/5 (82)
(82) Pedro, not a dealer, sold real property that he owned with an adjusted basis of $120,000 and encumbered by a mortgage for $56,000 to Pat in 2015. The terms of the sale required Pat to pay $28,000 cash, assume the $56,000 mortgage, and give Pedro eleven notes for $12,000 each (plus interest at the Federal rate). The first note was payable two years from the date of sale and each succeeding note became due at two-year intervals. Pedro did not "elect out" of the installment method for reporting the transaction. If Pat pays the 2017 note as promised, what is the recognized gain to Pedro in 2017 (exclusive of interest)?
(Multiple Choice)
4.8/5 (80)
(80) The taxpayer has consistently, but incorrectly, used an allowance for bad debts. At the beginning of the year, the balance in the allowance account is $90,000.
(Multiple Choice)
4.9/5 (81)
(81) Ramon sold land in 2017 with a cost of $80,000 for $200,000. The sales agreement called for a $50,000 down payment and a $50,000 payment plus 8% interest to be received on the first day of each year for the next three years. What would be the consequences of the following (treat each part independently and assume Ramon uses the installment method whenever possible):
a.In 2017, Ramon gave one of the $50,000 installment obligations to a close relative.
b.In 2017, Ramon transferred the installment obligations ($50,000) to his 100% owned corporation.
c.Ramon collected the $50,000 plus $12,000 interest on January 1, 2018, and died on January 2, 2018.
(Essay)
4.8/5 (70)
(70) A cash basis taxpayer sold investment land in 2016 for $200,000. He received $40,000 in the year of sale and $160,000 in 2017. The cost of the land was $80,000. Under the installment method, the taxpayer would report a $24,000 gain in 2016.
(True/False)
4.9/5 (73)
(73) Brown Corporation had consistently reported its income by the cash method. The corporation should have used the accrual method because inventories are material to the business. In 2017, Brown timely filed a request to change to the accrual method. At the beginning of 2017, Brown had accounts receivable of $75,000. Also, Brown had merchandise on hand with a cost of $150,000 and accounts payable for merchandise of $45,000. The accounts receivable, inventory, and accounts payable balance per books were zero. Determine the adjustment to income due to the change in accounting method and the amount that is allocated to 2017.
(Essay)
4.8/5 (76)
(76) In 2017, Norma sold Zinc, Inc., common stock for $100,000 cash and a note receivable for $900,000. The note was due in 2018 with accrued interest at the Federal rate. Norma's basis in the stock was $250,000. This was Norma's only installment sale transaction. Which of the following statements is correct?
(Multiple Choice)
4.9/5 (73)
(73) Purple Corporation, a personal service corporation (PSC), adopted a fiscal year ending September 30th. The sole shareholder of the corporation is a calendar year taxpayer. During the fiscal year ending September 30, 2017, the shareholder-employee received $120,000 salary. The corporation paid the shareholder-employee a salary of $15,000 during the period beginning October 1, 2017 through December 31, 2017.
(Multiple Choice)
4.9/5 (77)
(77) The Seagull Partnership has three equal partners. Partner A's tax year ends June 30th, and Partners B and C use a calendar year. If the partnership uses the calendar year to report its income, Partner A is permitted to defer partnership income earned from July through December 2016 until he files his tax return for his year ending June 30, 2017.
(True/False)
4.8/5 (78)
(78) A doctor's incorporated medical practice may end the last day of any month of the year.
(True/False)
4.9/5 (78)
(78) The DEF Partnership had three equal partners when it was formed. Partners D and E were calendar year taxpayers and Partner F's tax year ended on June 30th before he joined the partnership. The partnership may use a calendar year and partner F may continue to use the tax year ending June 30th.
(True/False)
4.9/5 (68)
(68) Brown Corporation elected dollar-value LIFO in 2012. Its ending inventory at base year cost and its LIFO indexes are as follows:
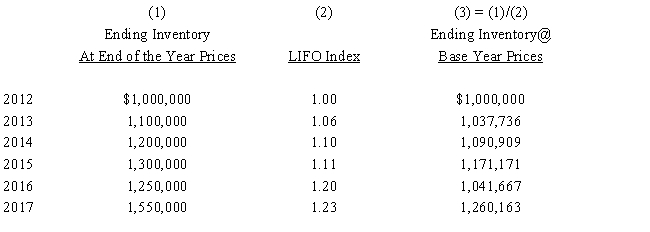 Compute the LIFO inventory at the end of 2017.
 (Essay)
4.8/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)