



 Chat with AI
Exam 11: Credit Risk II: Loan Portfolio and Concentration Risk

Exam 1: Why Are Financial Institutions Special68 Questions
Exam 2: The Financial Service Industry: Depository Institutions78 Questions
Exam 3: The Financial Service Industry: Other Financial Institutions68 Questions
Exam 4: Risks of Financial Institutions76 Questions
Exam 5: Interest Rate Risk Measurement: The Repricing Model78 Questions
Exam 6: Interest Rate Risk Measurement: the Duration Model73 Questions
Exam 7: Managing Interest Rate Risk Using Off-Balance-Sheet Instruments75 Questions
Exam 8: Managing Interest Rate Risk Using Securitisation75 Questions
Exam 9: Market Risk61 Questions
Exam 10: Credit Risk I: Individual Loan Risk75 Questions
Exam 11: Credit Risk II: Loan Portfolio and Concentration Risk76 Questions
Exam 12: Sovereign Risk76 Questions
Exam 13: Foreign Exchange Risk77 Questions
Exam 14: Liquidity Risk76 Questions
Exam 15: Liability and Liquidity Management77 Questions
Exam 16: Off-Balance-Sheet Activities75 Questions
Exam 17: Technology and Other Operational Risks77 Questions
Exam 18: Capital Management and Adequacy76 Questions
Select questions type


Consider the following hypothetical transition matrix: 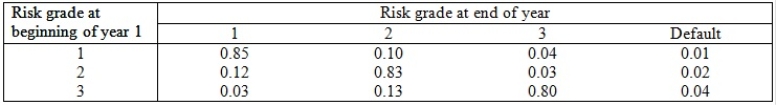 Which of the following statements is true?
 (Multiple Choice)
4.9/5  (69)
(69) Consider the following portfolio of assets: Loan i Weight i Expected return i \sigma/ 1 0.30 13\% 9.06\% 82.0\% =-0.87 2 0.70 11\% 8.72\% 76.0\% =-75.0\% What is the standard deviation of the portfolio (round to two decimals)?
(Multiple Choice)
4.9/5 (87)
(87) Consistent with actual insurance policies, the CDS buyer must own the underlying reference securities.
(True/False)
4.9/5 (76)
(76) Consider the following data for a two-asset portfolio: Loan i Weight i Annual spread between loan rate and Fl's cost of funds Annual fees Loss to FI given default Expected default frequency 1 0.35 4.5\% 2.0\% 35\% 5\% =-0.28 2 0.65 5\% 2.5\% 30\% 4\% Using the Moody's Analytics model:
a.calculate the returns for loans 1 and 2.
b.calculate the risk for loans 1 and 2.
c.calculate the return for the loan portfolio.
d.calculate the risk for the loan portfolio.
e.explain your findings in (a) to (d).
(Essay)
4.8/5 (78)
(78) Loan loss ratio based models estimate systematic loan losses by running a time-series regression of quarterly losses of the ith sector's loss rate on the quarterly loss rate of an FI's total loans.
(True/False)
4.9/5 (77)
(77) Which of the following is not a reason for the credit risk on a swap to be less than the credit risk on a loan?
(Multiple Choice)
4.9/5 (78)
(78) Loan sales and securitisation are increasingly seen as valuable tools in the management of credit risk.Which of the following are not advantageous to FIs?
(Multiple Choice)
4.8/5 (78)
(78) Consider the following portfolio of assets: Loan i Weight i Expected return i \sigma1 \sigma 1 0.30 13\% 9.06\% 82.0\% =-0.87 2 0.70 11\% 8.72\% 76.0\% =-75.0\% What is the variance of the portfolio (round to two decimals)?
(Multiple Choice)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)