



 Chat with AI
Exam 17: Futures Markets and Risk Management

Exam 1: Investments: Background and Issues75 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets90 Questions
Exam 4: Mutual Funds and Other Investment Companies85 Questions
Exam 5: Risk and Return: Past and Prologue83 Questions
Exam 6: Efficient Diversification84 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory85 Questions
Exam 8: The Efficient Market Hypothesis86 Questions
Exam 9: Behavioral Finance and Technical Analysis87 Questions
Exam 10: Bond Prices and Yields93 Questions
Exam 11: Managing Bond Portfolios85 Questions
Exam 12: Macroeconomic and Industry Analysis89 Questions
Exam 13: Equity Valuation88 Questions
Exam 14: Financial Statement Analysis84 Questions
Exam 15: Options Markets88 Questions
Exam 16: Option Valuation85 Questions
Exam 17: Futures Markets and Risk Management87 Questions
Exam 18: Portfolio Performance Evaluation87 Questions
Exam 19: Globalization and International Investing70 Questions
Exam 20: Hedge Funds60 Questions
Exam 21: Taxes,inflation,and Investment Strategy73 Questions
Exam 22: Investors and the Investment Process81 Questions
Select questions type


On Monday morning you sell one June T-bond futures contract at 97:27 or for $97,843.75. The contract's face value is $100,000. The initial margin requirement is $2,700 and the maintenance margin requirement is $2,000 per contract. Use the following price data to answer questions 67 through 70. 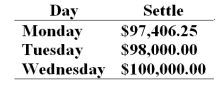 -On which of the given days do you get a margin call?
 (Multiple Choice)
4.9/5  (75)
(75) The price of a corn futures contract is $2.65 per bushel when the contract is issued and the commodity spot price is $2.55.When the contract expires,the two prices are identical.What principle is represented by this price behavior?
(Multiple Choice)
4.9/5 (86)
(86) If an asset price declines,the investor with a _______ is exposed to the largest potential loss.
(Multiple Choice)
4.7/5 (70)
(70) If you expect a stock market downturn,one potential defensive strategy would be to __________.
(Multiple Choice)
5.0/5 (80)
(80) The use of leverage is practiced in the futures markets due to the existence of _________.
(Multiple Choice)
4.8/5 (79)
(79) Interest rate swaps involve the exchange of ________________.
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)