



 Chat with AI
Exam 17: Futures Markets and Risk Management

Exam 1: Investments: Background and Issues75 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets90 Questions
Exam 4: Mutual Funds and Other Investment Companies85 Questions
Exam 5: Risk and Return: Past and Prologue83 Questions
Exam 6: Efficient Diversification84 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory85 Questions
Exam 8: The Efficient Market Hypothesis86 Questions
Exam 9: Behavioral Finance and Technical Analysis87 Questions
Exam 10: Bond Prices and Yields93 Questions
Exam 11: Managing Bond Portfolios85 Questions
Exam 12: Macroeconomic and Industry Analysis89 Questions
Exam 13: Equity Valuation88 Questions
Exam 14: Financial Statement Analysis84 Questions
Exam 15: Options Markets88 Questions
Exam 16: Option Valuation85 Questions
Exam 17: Futures Markets and Risk Management87 Questions
Exam 18: Portfolio Performance Evaluation87 Questions
Exam 19: Globalization and International Investing70 Questions
Exam 20: Hedge Funds60 Questions
Exam 21: Taxes,inflation,and Investment Strategy73 Questions
Exam 22: Investors and the Investment Process81 Questions
Select questions type


A long hedge is a simultaneous __________ position in the spot market and a __________ position in the futures market.
(Multiple Choice)
4.7/5  (84)
(84) Which of the following provides the profit to a long position at contract maturity?
(Multiple Choice)
4.8/5 (79)
(79) On February 25,2008 you could have purchased a futures contract from Intrade that would pay you $1 if Barack Obama wins the 2008 Democratic Party nomination.At a price of $0.81,the contract for Obama carried the highest price of any Democratic candidate.This tells you _______________.
(Multiple Choice)
4.9/5 (86)
(86) The spot price for is $650.The dividend yield on the S&P 500 is 2.5%.The risk-free interest rate is 5%.The futures price for gold for a one year contract should be __________.
(Multiple Choice)
4.9/5 (72)
(72) Initial margin is usually set in the region of ________ of the total value of a futures contract.
(Multiple Choice)
4.7/5 (78)
(78) On Monday morning you sell one June T-bond futures contract at 97:27 or for $97,843.75. The contract's face value is $100,000. The initial margin requirement is $2,700 and the maintenance margin requirement is $2,000 per contract. Use the following price data to answer questions 67 through 70. 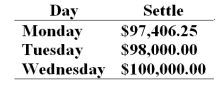 -The volume of interest rate swaps increased from almost zero in 1980 to over __________ today.
 (Multiple Choice)
4.8/5 (81)
(81) On Monday morning you sell one June T-bond futures contract at 97:27 or for $97,843.75. The contract's face value is $100,000. The initial margin requirement is $2,700 and the maintenance margin requirement is $2,000 per contract. Use the following price data to answer questions 67 through 70.
-After Monday's close the balance on your margin account will be ________.
-After Monday's close the balance on your margin account will be ________. (Multiple Choice)
4.9/5 (66)
(66) Forward contracts _________ traded on an organized exchange and futures contracts __________ traded on an organized exchange.
(Multiple Choice)
4.8/5 (85)
(85) A company which mines bauxite decides to short aluminum futures.This is an example of __________ to limit its risk.
(Multiple Choice)
4.9/5 (68)
(68) A person with a long position in a commodity futures contract wants the price of the commodity to ______.
(Multiple Choice)
4.9/5 (90)
(90) An investor who goes short in a futures contract will _____ any increase in value of the underlying asset and will _____ any decrease in value in the underlying asset.
(Multiple Choice)
4.8/5 (66)
(66) The S&P500 index futures contract is an example of a(n)______ delivery contract.The pork bellies contract is an example of a(n)______ delivery contract.
(Multiple Choice)
4.8/5 (88)
(88) Sahali Trading Company has issued $100 million worth of long-term bonds at a fixed rate of 9%.Sahali Trading Company then enters into an interest rate swap where they will pay LIBOR and receive a fixed 8.00% on a notional principal of $100 million.After all these transactions are considered,Sahali's cost of funds is __________.
(Multiple Choice)
4.7/5 (78)
(78) A long hedger will __________ from an increase in the basis a short hedger will __________.
(Multiple Choice)
4.7/5 (87)
(87) A hog farmer decides to sell hog futures.This is an example of __________ to limit its risk.
(Multiple Choice)
4.9/5 (76)
(76) An investor would want to __________ to exploit an expected fall in interest rates.
(Multiple Choice)
4.8/5 (98)
(98) A bank has made long term fixed rate mortgages and has financed them with short term deposits.To hedge out the bank's interest rate risk they could ________.
(Multiple Choice)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)