



 Chat with AI
Exam 17: Futures Markets and Risk Management

Exam 1: Investments: Background and Issues75 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets90 Questions
Exam 4: Mutual Funds and Other Investment Companies85 Questions
Exam 5: Risk and Return: Past and Prologue83 Questions
Exam 6: Efficient Diversification84 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory85 Questions
Exam 8: The Efficient Market Hypothesis86 Questions
Exam 9: Behavioral Finance and Technical Analysis87 Questions
Exam 10: Bond Prices and Yields93 Questions
Exam 11: Managing Bond Portfolios85 Questions
Exam 12: Macroeconomic and Industry Analysis89 Questions
Exam 13: Equity Valuation88 Questions
Exam 14: Financial Statement Analysis84 Questions
Exam 15: Options Markets88 Questions
Exam 16: Option Valuation85 Questions
Exam 17: Futures Markets and Risk Management87 Questions
Exam 18: Portfolio Performance Evaluation87 Questions
Exam 19: Globalization and International Investing70 Questions
Exam 20: Hedge Funds60 Questions
Exam 21: Taxes,inflation,and Investment Strategy73 Questions
Exam 22: Investors and the Investment Process81 Questions
Select questions type


A one year gold futures contract is selling for $641. Spot gold prices are $600 and the one year risk free rate is 6%.
-Based on the above data,which of the following set of transactions will yield positive riskless arbitrage profits?

Free
(Multiple Choice)
4.8/5  (70)
(70) Correct Answer: Verified
A
Single stock futures,as opposed to stock index futures,are _______________.
Free
(Multiple Choice)
4.8/5 (82)
(82) Correct Answer:Verified
VerifiedC
An investor would want to __________ to hedge a long position in treasury bonds.
Free
(Multiple Choice)
4.8/5 (83)
(83) Correct Answer:Verified
VerifiedC
The fact that the exchange is the counter-party to every futures contract issued is important because it eliminates _________ risk.
(Multiple Choice)
4.9/5 (79)
(79) On January 1,you sold one April S&P 500 index futures contract at a futures price of 1300.If the April futures price is 1250 on February 1,your profit would be __________ if you close your position.(The contract multiplier is 250.)
(Multiple Choice)
4.8/5 (72)
(72) A speculator will often prefer to buy a futures contract rather than the underlying asset because ____________.
I.gains in futures contracts can be larger due to leverage
II.transaction costs in futures are typically lower than in spot markets
III.futures markets are often more liquid than the markets of the underlying commodities
(Multiple Choice)
5.0/5 (79)
(79) You believe that the spread between the September T-bond contract and the June T-bond futures contract is too large and will soon correct.This market exhibits positive cost of carry for all contracts.To take advantage of this you should ______________.
(Multiple Choice)
4.9/5 (72)
(72) A market timer now believes that the economy will soften over the rest of the year as the housing market slump continues and he also believes that foreign investors will stop buying U.S.fixed income securities in such large quantities as they have in the past.One way the timer could take advantage of this forecast is to ________________.
(Multiple Choice)
4.8/5 (69)
(69) Recently most of the growth in the number of contracts traded on the Chicago Board of Trade has come in the _______ contracts.
(Multiple Choice)
4.8/5 (78)
(78) On Monday morning you sell one June T-bond futures contract at 97:27 or for $97,843.75. The contract's face value is $100,000. The initial margin requirement is $2,700 and the maintenance margin requirement is $2,000 per contract. Use the following price data to answer questions 67 through 70. 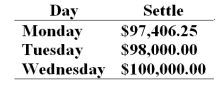 -If rf is greater than d then we know that _______________.
 (Multiple Choice)
4.8/5 (93)
(93) The CME weather futures contract is an example of ______________.
(Multiple Choice)
4.8/5 (77)
(77) Margin requirements for futures contracts can be met by ______________.
(Multiple Choice)
4.8/5 (78)
(78) An investor who goes long in a futures contract will _____ any increase in value of the underlying asset and will _____ any decrease in value in the underlying asset.
(Multiple Choice)
4.8/5 (70)
(70) An investor who is hedging a corporate bond portfolio using a T-bond futures contract is said to have a(n)_______.
(Multiple Choice)
4.9/5 (92)
(92) A one year gold futures contract is selling for $641. Spot gold prices are $600 and the one year risk free rate is 6%.
-A hypothetical futures contract on a non-dividend-paying stock with current spot price of $100 has a maturity of one year.If the T-bill rate is 5% what should the futures price be?
(Multiple Choice)
4.8/5 (79)
(79) A short hedge is a simultaneous __________ position in the spot market and a __________ position in the futures market.
(Multiple Choice)
4.8/5 (93)
(93) On Monday morning you sell one June T-bond futures contract at 97:27 or for $97,843.75. The contract's face value is $100,000. The initial margin requirement is $2,700 and the maintenance margin requirement is $2,000 per contract. Use the following price data to answer questions 67 through 70.
-At the close of day Tuesday your cumulative rate of return on your investment is
-At the close of day Tuesday your cumulative rate of return on your investment is (Multiple Choice)
4.8/5 (79)
(79) You purchase an interest rate futures contract that has an initial margin requirement of 15% and a futures price of $115,098.The contract has a $100,000 underlying par value bond.If the futures price falls to $108,000 you will experience a ______ percent loss on your money invested.
(Multiple Choice)
4.9/5 (73)
(73) Investors who take short positions in futures contract agree to ___________ delivery of the commodity on the delivery date,and those who take long positions agree to __________ delivery of the commodity.
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)