



 Chat with AI
Exam 18: Family Tax Planning

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


One way to dispute the existence of large goodwill is to argue that the decedent was not a key person in the operation of the business.
(True/False)
4.9/5  (91)
(91) Four years prior to death,a decedent makes a gift of an insurance policy on his life.In testing for the percentage requirements of the special use valuation method (i.e.,§ 2032A),the life insurance policy is considered.
(True/False)
4.8/5 (75)
(75) Which of the following procedures carried out will reduce both Mary's future gross estate and her probate estate?
(Multiple Choice)
4.9/5 (86)
(86) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Living trusts
b.Income in respect of a decedent (IRD)
c.Conservation easement
d.Discretionary extension of time to pay estate tax (§ 6161)
e.Estate freeze-corporations
f.Extension of time involving interest in closely held business (§ 6166)
g.Special use valuation as to certain realty (§ 2032A)
h.Recapture potential under §§ 1245 and 1250 eliminated
i.Alternate valuation date (§ 2032)
j.Election to split gifts (§ 2513)
k.No correct choice is given
-Can produce income tax,ad valorem property tax,and estate tax savings.
(Short Answer)
4.9/5 (80)
(80) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Increases the probate estate
b.Decreases the probate estate
c.Has no effect on the probate estate
-Created a living trust.
(Short Answer)
4.7/5 (91)
(91) Under Cindy's will,her share of their community property passes to Van,her surviving spouse.Cindy's property is subject to probate.
(True/False)
4.9/5 (69)
(69) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Increases the probate estate
b.Decreases the probate estate
c.Has no effect on the probate estate
-Made life insurance payable to estate.
(Short Answer)
4.8/5 (75)
(75) Which,if any,of the following factors should reduce the value of a note receivable included in the gross estate of the holder?
(Multiple Choice)
4.8/5 (77)
(77) Which,if any,of the items listed below are valid factors utilized in valuing the stock in a closely held corporation?
(Multiple Choice)
4.8/5 (75)
(75) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Step-up in basis
b.Step-down in basis
c.Gift of U.S. savings bonds
d.Gift of depreciable property that has § 1245 or § 1250 recapture of depreciation potential
e.Donor's basis on date of gift (appreciated property given)*
f.The amount of the deceased spouse's gross estate does not change
g.Fair market value on date of gift (depreciated property given)*
h.Expected surviving spouse is already wealthy
i.Income in respect of a decedent (IRD)
j.Expected surviving spouse is in good health
k.No correct choice is given
*No gift tax involved
-A gift will not cause income tax consequences to the donor.
(Short Answer)
4.7/5 (86)
(86) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Use IRS valuation tables
b.Exclusion amount (exemption equivalent)
c.Current use value
d.Best or most suitable use value
e.Cost of going public
f.Replacement cost of a comparable contact
g.Portion of a deceased spouse's estate that passes to a surviving spouse
h.Entity buy and sell agreement
i.Cross-purchase buy and sell agreement
j.Discount for minority interest
k.No correct choice is given
-Martial deduction.
(Short Answer)
4.8/5 (83)
(83) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Use IRS valuation tables
b.Exclusion amount (exemption equivalent)
c.Current use value
d.Best or most suitable use value
e.Cost of going public
f.Replacement cost of a comparable contact
g.Portion of a deceased spouse's estate that passes to a surviving spouse
h.Entity buy and sell agreement
i.Cross-purchase buy and sell agreement
j.Discount for minority interest
k.No correct choice is given
-Special use valuation as to certain realty (§ 2032A).
(Short Answer)
4.8/5 (76)
(76) Eric,age 80,has accumulated about $3 million in net assets.Among his assets are the following marketable securities held as investments.
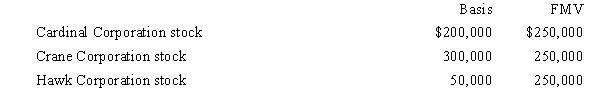 Eric would like to donate (either by lifetime or testamentary transfer)$250,000 in value to his church.In addition,to consummate a land deal,he needs $250,000 in cash.Looking solely to tax considerations and using only the assets described above,Eric's best choice is to:
 (Multiple Choice)
4.8/5 (77)
(77) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Living trusts
b.Income in respect of a decedent (IRD)
c.Conservation easement
d.Discretionary extension of time to pay estate tax (§ 6161)
e.Estate freeze-corporations
f.Extension of time involving interest in closely held business (§ 6166)
g.Special use valuation as to certain realty (§ 2032A)
h.Recapture potential under §§ 1245 and 1250 eliminated
i.Alternate valuation date (§ 2032)
j.Election to split gifts (§ 2513)
k.No correct choice is given
-Transfer by death of depreciable property.
(Short Answer)
5.0/5 (78)
(78) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Use IRS valuation tables
b.Exclusion amount (exemption equivalent)
c.Current use value
d.Best or most suitable use value
e.Cost of going public
f.Replacement cost of a comparable contact
g.Portion of a deceased spouse's estate that passes to a surviving spouse
h.Entity buy and sell agreement
i.Cross-purchase buy and sell agreement
j.Discount for minority interest
k.No correct choice is given
-Corporation agrees to redeem withdrawing shareholder's stock.
(Short Answer)
4.7/5 (85)
(85) Match each statement with a correct choice. Choices may be used more than once.
a.Increases the probate estate
b.Decreases the probate estate
c.Has no effect on the probate estate
-After death,vacation home is destroyed by fire.
(Short Answer)
4.9/5 (80)
(80) Noncommercial annuity contracts must be valued using the tables issued by the IRS.
(True/False)
4.7/5 (73)
(73) At the time of his death,Fred held some notes receivable for loans he made to his two daughters and the payment of which he forgives in his will.The amount to be included in Fred's gross estate as to these notes is affected by his forgiveness.
(True/False)
4.7/5 (84)
(84) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Living trusts
b.Income in respect of a decedent (IRD)
c.Conservation easement
d.Discretionary extension of time to pay estate tax (§ 6161)
e.Estate freeze-corporations
f.Extension of time involving interest in closely held business (§ 6166)
g.Special use valuation as to certain realty (§ 2032A)
h.Recapture potential under §§ 1245 and 1250 eliminated
i.Alternate valuation date (§ 2032)
j.Election to split gifts (§ 2513)
k.No correct choice is given
-Eliminates common stock from donor's gross estate.
(Short Answer)
5.0/5 (83)
(83) Troy and Myrna are husband and wife and have several adult children.Myrna has a net worth in excess of several million dollars,while Troy's assets are negligible.Suggest several planning procedures that will maximize the use of estate exemption equivalents (i.e.,bypass amounts)in transferring Myrna's wealth to the children under the following assumptions.
a.Myrna dies first.
b.Troy dies first.
(Essay)
4.7/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)