



 Chat with AI
Exam 18: Family Tax Planning

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Increases the probate estate
b.Decreases the probate estate
c.Has no effect on the probate estate
-Created during life an irrevocable trust naming others as beneficiaries.
(Short Answer)
4.8/5  (88)
(88) If a stock redemption is to be carried out,a cross-purchase type of buy and sell agreement must be involved.
(True/False)
4.8/5 (76)
(76) The deferral approach to the estate tax marital deduction (as opposed to the equalization approach)is advisable if the surviving spouse is in good health and has few assets.
(True/False)
5.0/5 (80)
(80) Match each statement with a correct choice. Choices may be used more than once.
a.Increases the probate estate
b.Decreases the probate estate
c.Has no effect on the probate estate
-Prior to death filed for a refund of overpaid income taxes.
(Short Answer)
4.9/5 (82)
(82) What are the advantages of § 6166 (extension of time when the estate consists largely of an interest in a closely held business)?
(Essay)
4.9/5 (81)
(81) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Increases the probate estate
b.Decreases the probate estate
c.Has no effect on the probate estate
-Purchase out-of-state realty.
(Short Answer)
5.0/5 (82)
(82) The election by an estate of § 2032A (special use valuation as to real estate)or § 2032 (the alternate valuation date)will have no effect on the income tax basis of the property received by the heirs.
(True/False)
4.8/5 (81)
(81) Match each statement with a correct choice. Choices may be used more than once.
a.Increases the probate estate
b.Decreases the probate estate
c.Has no effect on the probate estate
-Purchased insurance policy that pays all funeral expenses.
(Short Answer)
4.9/5 (92)
(92) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Use IRS valuation tables
b.Exclusion amount (exemption equivalent)
c.Current use value
d.Best or most suitable use value
e.Cost of going public
f.Replacement cost of a comparable contact
g.Portion of a deceased spouse's estate that passes to a surviving spouse
h.Entity buy and sell agreement
i.Cross-purchase buy and sell agreement
j.Discount for minority interest
k.No correct choice is given
-Surviving owners agree to purchase withdrawing owner's interest.
(Short Answer)
4.8/5 (78)
(78) In 2008,Valerie made a gift of stock (basis of $112,000; fair market value of $412,000)to her grandson,Ryan.As a result of the transfer,Valerie paid a gift tax of $20,000.Ryan's income tax basis in the stock is:
(Multiple Choice)
4.8/5 (88)
(88) Application of the blockage rule has not been limited to just the valuation of stocks and bonds.
(True/False)
4.9/5 (75)
(75) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Step-up in basis
b.Step-down in basis
c.Gift of U.S. savings bonds
d.Gift of depreciable property that has § 1245 or § 1250 recapture of depreciation potential
e.Donor's basis on date of gift (appreciated property given)*
f.The amount of the deceased spouse's gross estate does not change
g.Fair market value on date of gift (depreciated property given)*
h.Expected surviving spouse is already wealthy
i.Income in respect of a decedent (IRD)
j.Expected surviving spouse is in good health
k.No correct choice is given
*No gift tax involved
-Donee's basis for gain.
(Short Answer)
4.9/5 (78)
(78) At the time of her death,Lila owns 50% of the stock in Kingfisher Corporation,with the balance of the stock held by family members.Kingfisher Corporation's total profits for the past five years are $3,000,000,and the book value of its stock is $2,000,000.If 8% is an appropriate rate of return and goodwill exists,what is a possible value for the stock to be included in Lila's gross estate?
(Essay)
4.9/5 (79)
(79) Corey owns all of the stock of Blond Corporation which includes both common and preferred shares.The preferred stock is noncumulative,has no redemption date,and possesses no liquidation preference.In 1995,Corey makes a gift to his adult children of all of the common stock.He dies in 2008 still owning the preferred stock.The value of the Blond stock on the relevant dates is:
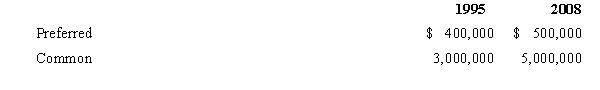 One of the tax consequences of this estate freeze is:
 (Multiple Choice)
4.8/5 (81)
(81) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Living trusts
b.Income in respect of a decedent (IRD)
c.Conservation easement
d.Discretionary extension of time to pay estate tax (§ 6161)
e.Estate freeze-corporations
f.Extension of time involving interest in closely held business (§ 6166)
g.Special use valuation as to certain realty (§ 2032A)
h.Recapture potential under §§ 1245 and 1250 eliminated
i.Alternate valuation date (§ 2032)
j.Election to split gifts (§ 2513)
k.No correct choice is given
-Election by estate can affect income tax basis of surviving spouse's share of community property.
(Short Answer)
4.8/5 (83)
(83) How can a disclaimer by an heir increase the charitable deduction allowed a decedent? Is such a disclaimer always wise? Explain.
(Essay)
4.8/5 (72)
(72) Herbert leaves one-half of his estate to his wife,Ramona,and the remainder to a qualified charity.Herbert's estate taxes would not be reduced if Ramona disclaims her interest in favor of the charity.
(True/False)
4.8/5 (76)
(76) Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Increases the probate estate
b.Decreases the probate estate
c.Has no effect on the probate estate
-Made lifetime gifts.
(Short Answer)
4.9/5 (80)
(80) Which,if any,of the following statements correctly reflects the operational rules under § 2032A ("special use" valuation)?
(Multiple Choice)
4.8/5 (93)
(93) Harvey owns a certificate of deposit listed as: "Harvey,payable on proof of death to April." On Harvey's prior death,the CD is subject to probate.
(True/False)
5.0/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)