



 Chat with AI
Exam 18: Family Tax Planning


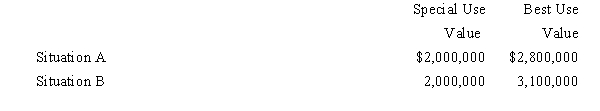
Presuming the § 2032A election is properly made,what value is included in the gross estate (in 2008)in each of the following independent situations?

 (83)
 Verified
Situation A is $2,000,000,as reduction cannot go below special use value.Situation B is $2,140,000 ($3,100,000 - $960,000).
Giselle,a widow,has an extensive investment portfolio that has appreciated in value. Starting in 2008,she initiates a policy of making annual gifts of securities to her grandchildren who are attending college.Evaluate Giselle's policy in terms of the:
a.Federal gift and estate taxes.
b.Federal income tax.
(85) Verifieda.Although the number of annual exclusions is being maximized,gift taxes or some of the amount could be avoided by making direct transfers to the educational institution-see the discussion of § 2503(e)in Chapter 17 .However,the use of § 2503(e)covers only tuition costs and would require Giselle to use cash (rather than securities). By making these gifts,Giselle is reducing her wealth,thereby cutting down on future estate taxes.
b.Giselle's major objective probably is to shift income tax consequences to lower bracket donees. If the grandchildren are below the 25% tax bracket (i.e.,they are in the 15% or 10% brackets),capital gains are taxed at a 0% rate (rather than Giselle's 15% rate). However,this result is successful only if the kiddie tax is avoided. By waiting until the grandchildren finish college,or,if earlier,age 24 has been reached,the kiddie tax no longer applies.
Paul dies and leaves his traditional IRA to Evelyn.Which statement is correct?
(84) VerifiedD
Match each statement with the correct choice. Some choices may be used more than once or not used at all.
a.Living trusts
b.Income in respect of a decedent (IRD)
c.Conservation easement
d.Discretionary extension of time to pay estate tax (§ 6161)
e.Estate freeze-corporations
f.Extension of time involving interest in closely held business (§ 6166)
g.Special use valuation as to certain realty (§ 2032A)
h.Recapture potential under §§ 1245 and 1250 eliminated
i.Alternate valuation date (§ 2032)
j.Election to split gifts (§ 2513)
k.No correct choice is given
-Reasonable cause will justify election.
(71) Spencer makes a gift of stock in Swallow Corporation,which is not closely held but is traded in an over-the-counter market.The transactions involving this stock that occurred closest to the date of gift took place seven trading days before (mean selling price of $90)and five days after (mean selling price of $70).Determine the fair market value of the Swallow stock on the date of the gift.
(88) Paula creates a trust,income payable to John (age 18)for 6 years,remainder to Elizabeth (age 39).In determining the value of Elizabeth's interest,use the multiple provided in the tables for a person age 45 (age 39 plus the 6-year intervening interest).
(87) In arriving at the valuation of assets for estate tax purposes,the geographic location of the property is to be disregarded.
(72) The sole objective of family tax planning is to minimize gift and estate taxes on transfers of property within the family unit.
(74) Under proper circumstances,a disclaimer by an heir may increase the charitable deduction allowed a decedent.
(74) When carrying out an estate freeze with family limited partnerships,the donors make gifts of the general partnership interests but retain the limited partnership interests.
(77) In connection with a traditional IRA that is transferred at death,comment on the tax implications of each of the following.
a.The beneficiary does nothing, and a distribution occurs.
b.The beneficiary retitles the IRA as a "retirement IRA."
c.The additional tax advantages enjoyed when the beneficiary is the surviving spouse.
d.The consequences of the IRA constituting income in respect of a decedent (IRD).
(93) In February 2007,Michelle sold real estate (adjusted basis of $300,000)for $800,000.Under the terms of the sale,the purchaser issued two notes of $400,000 each,payable annually.In January 2008 and when the notes are worth $760,000,Michelle gives the notes to her son.What,if any,are Michelle's tax consequences?
(86) Match each statement with a correct choice. Choices may be used more than once.
a.Increases the probate estate
b.Decreases the probate estate
c.Has no effect on the probate estate
-Brother purchased land listing ownership with decedent as tenants in common.
(71) A decedent owned 15% of the voting stock of Falcon Corporation.Falcon has 43 shareholders.The decedent's estate can qualify for the § 6166 election.
(77) Which,if any,of the following items characterizes § 6166 (i.e.,extension of estate tax payments relative to an interest in a closely held business)?
(67) A discount for valuation purposes is allowed when the stock involved represents a minority interest.
(70) In April 2007,Austin makes a gift of real estate (basis of $200,000; fair market value $600,000)to his aunt.After the gift,the aunt makes $55,000 worth of capital improvements to the property.The aunt dies in March 2008,when the property is worth $640,000.Under the aunt's will,the realty passes to Kinsey (Austin's wife).Kinsey's income tax basis in the property is:
(96) Derrick dies,and under the terms of his will,all of his property passes outright to Dion (Derrick's surviving wife).Under these circumstances,there is no need for Derrick's executor to make a QTIP election.
(84) In June 2007,Becky makes a gift of securities (basis $412,000; fair market value $812,000)to her uncle,upon which a gift tax of $40,000 is paid.The uncle dies in July 2008,when the securities are worth $900,000.Under the terms of the uncle's will,the securities return to Becky.Becky's income tax basis in the securities is:
(79) William and Madison are husband and wife.Fifteen years ago,they purchased real estate for $200,000.Madison dies first in 2008 when the property is worth $1,000,000.Assuming the property passes to William,what is his income tax basis under the following ownership assumptions?
a.A tenancy by the entirety is involved.
b.Community property is involved.
c.Why are the results different?
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)