



 Chat with AI
Exam 15: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a.Taxable
b.Not taxable
-Textbook purchased by a State University student
(Short Answer)
4.9/5  (73)
(73) Roughly one-fifth of all taxes paid by businesses in the U.S.are to state,local,and municipal jurisdictions.
(True/False)
4.8/5 (81)
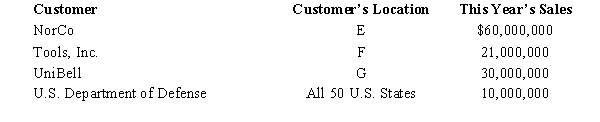
(81) State E applies a throwback rule to sales,while State F does not.State G has not adopted an income tax to date.Mercy Corporation,headquartered in F,reported the following sales for the year.All of the goods were shipped from Mercy's F manufacturing facilities.Mercy's degree of operations is sufficient to establish nexus only in E and F.Determine its sales factor in those states.
(Essay)
4.9/5 (80)
(80) Match each of the following items with the appropriate description, in applying the P.L. 86-272 definition of solicitation.
a.More than solicitation, creates nexus
b.Solicitation only, no nexus created
-Investigating the creditworthiness of customers
(Short Answer)
4.8/5 (79)
(79) Why does the advent of telecommuting present a critical tax planning issue with respect to the mobile employee?
(Essay)
4.9/5 (70)
(70) Match each of the following terms with the appropriate description, in the state income tax formula.
a.Addition modification
b.Subtraction modification
c.No modification
-Deduction for Federal communications tax
(Short Answer)
4.8/5 (90)
(90) A unitary business is treated as a single entity for state tax purposes,with a combined apportionment formula including data from all of the operations of the business.
(True/False)
4.8/5 (77)
(77) A service engineer spends 30% of her time maintaining the employer's productive business property and 70% maintaining the employer's nonbusiness rental properties.This year,her compensation totaled $90,000.The payroll factor assigns $90,000 among the states in which the employer conducts business,using a "time spent" formula.
(True/False)
4.9/5 (78)
(78) The property factor includes assets that the taxpayer owns,but not those merely used under a lease agreement.
(True/False)
4.8/5 (84)
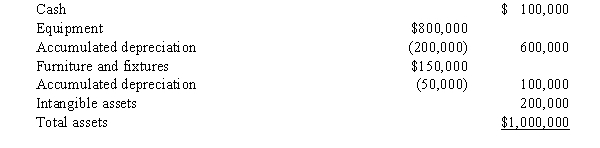
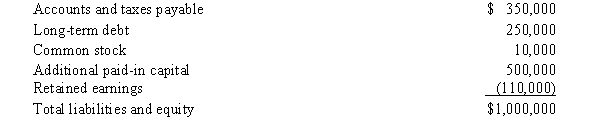
(84) Peete Corporation is subject to franchise tax in State Z.The tax is imposed at a rate of 2% of the taxpayer's net worth that is apportioned to the state by use of a two factor (sales and property equally weighted)formula.The property factor includes real and tangible personal property,valued at historical cost at the end of the taxable year.
Sixty percent of Peete's sales are attributable to Z,and $200,000 of the cost of Peete's tangible personal property is located in Z.
Determine the Z franchise tax payable by Peete this year,given the following end-of-the year balance sheet.
(Multiple Choice)
4.7/5 (78)
(78) All but a few states have not adopted a tax based on net taxable income.
(True/False)
4.9/5 (85)
(85) Perez Corporation is subject to tax only in State A.Perez generated the following income and deductions.
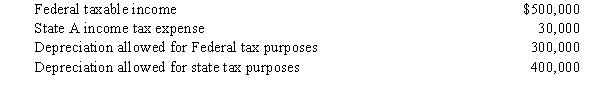 Federal taxable income is the starting point in computing A taxable income.State income taxes are not deductible for A tax purposes.Perez's A taxable income is:
 (Multiple Choice)
4.9/5 (72)
(72) Typical indicators of nexus include the presence of employees based in the state,and the ownership or lease of realty there.
(True/False)
5.0/5 (74)
(74) Match each of the following terms with the appropriate description, in the state income tax formula.
a.Addition modification
b.Subtraction modification
c.No modification
-State income tax expense
(Short Answer)
5.0/5 (77)
(77) Some states enforce their tax laws more aggressively than do others.
(True/False)
5.0/5 (78)
(78) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a.Taxable
b.Not taxable
-A garment purchased for resale
(Short Answer)
4.7/5 (73)
(73) ____________________ is a method under which specific components of a corporation's income are directly assigned to a specific state.
(Short Answer)
5.0/5 (84)
(84) Why is a knowledge of Federal income tax law important in computing state taxable income?
(Essay)
4.9/5 (80)
(80) Out-of-state sales that are not subject to tax in the destination state are pulled back into the origination state if that state has adopted a(n)____________________ ____________________.
(Short Answer)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)