



 Chat with AI
Exam 15: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


A taxpayer wishing to reduce the negative tax effects of the application of the unitary theory might:
(Multiple Choice)
4.8/5  (73)
(73) Almost all of the states tax a limited liability company as a ____________________ entity for income tax purposes.
(Short Answer)
4.9/5 (80)
(80) In determining taxable income for state income tax purposes,state income tax refunds typically constitute a(n)____________________ modification.
(Short Answer)
4.8/5 (79)
(79) A few states recognize an entity's S corporation status,such that taxable income flows through directly to shareholders,but they still assess a state-level tax on the entity.
(True/False)
4.7/5 (90)
(90) Double weighting the property factor effectively increases the tax burden on taxpayers based in the state,such as corporations with in-state headquarters.
(True/False)
4.9/5 (74)
(74) Match each of the following terms with the appropriate description, in the state income tax formula.
a.Addition modification
b.Subtraction modification
c.No modification
-Treasury Bond interest income
(Short Answer)
4.7/5 (72)
(72) The model law relating to the assignment of income among the states for corporations is:
(Multiple Choice)
4.9/5 (87)
(87) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a.Taxable
b.Not taxable
-Prescription drugs
(Short Answer)
4.9/5 (73)
(73) State B applies a throwback rule,but State A does not.General Corporation is taxable in a number of states and made a $100,000 sale from its A headquarters to a customer in B.This activity is not sufficient for General to create nexus with B.In which state(s)will the sale be included in the sales factor numerator?
(Multiple Choice)
4.9/5 (82)
(82) In computing the property factor,property owned by the corporation typically is valued at its ____________________,plus the cost of additions and improvements,but without adjusting for ____________________.
(Short Answer)
5.0/5 (70)
(70) Typically exempt from the sales/use tax base is the purchase of seed and feed by a farmer.
(True/False)
4.8/5 (83)
(83) Node Corporation is subject to tax only in State X.Node generated the following income and deductions.State income taxes are not deductible for X income tax purposes.
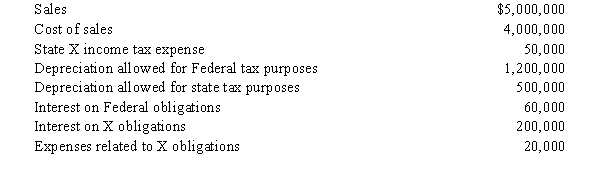 a.The starting point in computing the X income tax base is Federal taxable income. Derive this amount.
b.Determine Node's X taxable income, assuming that interest on X obligations is exempt from X income tax.
c.Determine Node's taxable income, assuming that interest on X obligations is subject to X income tax.
a.The starting point in computing the X income tax base is Federal taxable income. Derive this amount.
b.Determine Node's X taxable income, assuming that interest on X obligations is exempt from X income tax.
c.Determine Node's taxable income, assuming that interest on X obligations is subject to X income tax. (Essay)
4.7/5 (81)
(81) Net Corporation's sales office and manufacturing plant are located in State X.Net also maintains a manufacturing plant and sales office in State W.For purposes of apportionment,X defines payroll as all compensation paid to employees,including contributions to § 401(k)deferred compensation plans.Under the statutes of W,neither compensation paid to officers nor contributions to § 401(k)plans are included in the payroll factor.Net incurred the following personnel costs.
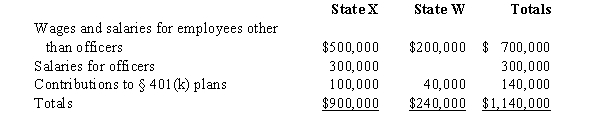 Net's payroll factor for State W is:
 (Multiple Choice)
4.9/5 (87)
(87) State A applies a throwback rule,but State B does not.General Corporation is taxable in a number of states and made a $100,000 sale from its A headquarters to a customer in B.This activity is not sufficient for General to create nexus with B.In which state(s)will the sale be included in the sales factor numerator?
(Multiple Choice)
4.7/5 (84)
(84) Helene Corporation owns manufacturing facilities in States A,B,and C.A uses a three-factor apportionment formula under which the sales,property and payroll factors are equally weighted.B uses a three-factor apportionment formula under which sales are double-weighted.C employs a single-factor apportionment factor,based solely on sales.
Helene's operations generated $1,000,000 of apportionable income,and its sales and payroll activity and average property owned in each of the three states is as follows.
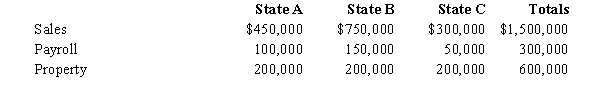 Helene's apportionable income assigned to A is:
 (Multiple Choice)
4.9/5 (59)
(59) Identify several transactions by business taxpayers where state and local tax issues are important.
(Essay)
4.8/5 (81)
(81) 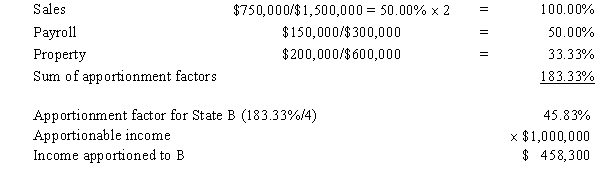 -Tripp Corporation owns manufacturing facilities in States A,B,and C.A uses a three-factor apportionment formula under which the sales,property and payroll factors are equally weighted.B uses a three-factor apportionment formula under which sales are double-weighted.C employs a single-factor apportionment factor,based solely on sales.
Tripp's operations generated $1,000,000 of apportionable income,and its sales and payroll activity and average property owned in each of the three states is as follows.
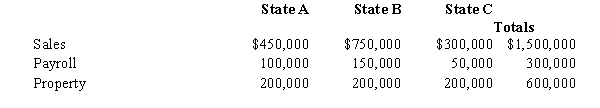 Tripp's apportionable income assigned to C is:
-Tripp Corporation owns manufacturing facilities in States A,B,and C.A uses a three-factor apportionment formula under which the sales,property and payroll factors are equally weighted.B uses a three-factor apportionment formula under which sales are double-weighted.C employs a single-factor apportionment factor,based solely on sales.
Tripp's operations generated $1,000,000 of apportionable income,and its sales and payroll activity and average property owned in each of the three states is as follows.
Tripp's apportionable income assigned to C is: (Multiple Choice)
4.8/5 (88)
(88) The benefits of a passive investment company typically include:
(Multiple Choice)
4.9/5 (81)
(81) Leased property,when included in the property factor,usually is valued at ____________________ times its annual rental,less any subrentals.
(Short Answer)
4.8/5 (79)
(79) Match each of the following terms with the appropriate description, in the state income tax formula.
a.Addition modification
b.Subtraction modification
c.No modification
-Federal ACE adjustment
(Short Answer)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)