



 Chat with AI
Exam 10: Partnerships: Formation, operation, and Basis

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


Joel and Desmond are forming the JD Partnership.Joel contributes $300,000 cash and Desmond contributes nondepreciable property with an adjusted basis of $80,000 and a fair market value of $330,000.The property is subject to a $30,000 liability,which is also transferred into the partnership and is shared equally by the partners for basis purposes.Joel and Desmond share in all partnership profits equally except for any precontribution gain,which must be allocated according to the statutory rules for built-in gain allocations.
a.What is Desmond's adjusted tax basis for his partnership interest immediately after the partnership is formed?
b.What is the partnership's adjusted basis for the property contributed by Desmond?
c.If the partnership sells the property contributed by Desmond for $360,000, how is the tax gain allocated between the partners?
(Essay)
5.0/5  (80)
(80) Julie is a real estate developer and owns property that is treated as inventory (not a capital asset)in her business.She contributed a parcel of this land (basis $60,000; fair market value $58,000)to a partnership,which will also hold it as inventory.After three years,the partnership sells the land for $56,000.The partnership will recognize a $4,000 ordinary loss on sale of the property.
(True/False)
4.8/5 (90)
(90) Maria owns a 60% interest in the KLM Partnership.Four years ago her father gave her a parcel of land.The gift basis of the land to Maria is $60,000.In the current year,Maria had still not figured out how to use the land for her own personal or business use; consequently,she sold the land to the partnership for $75,000.The partnership immediately started using the land as a parking lot for its employees.Maria recognizes a capital gain of $15,000 on the sale.
(True/False)
4.8/5 (80)
(80) Susan and Sarah form a partnership by each making contributions of $30,000 cash to partnership capital.The partnership purchases an asset for $200,000,using the cash and financing the rest with a $140,000 recourse note.Susan is allocated 75% of partnership profits and losses until the date when the total partnership profits exceed total partnership losses.After that date,the profits and losses are shared equally between the two partners.The partners expect the partnership to have losses for the first three years of operations and profits thereafter.How will the recourse debt be shared between the partners for basis purposes immediately after the property is acquired?
(Essay)
4.8/5 (65)
(65) Meagan purchased her partnership interest from Lisa on the first day of the current year for $30,000 cash.She received a $15,000 cash distribution from the partnership during the year,and her share of partnership income is $12,000.If her share of partnership liabilities on the last day of the partnership year is $10,000,her outside basis for her partnership interest at the end of the year is $27,000.
(True/False)
5.0/5 (92)
(92) Match each of the following statements with the terms below that provide the best definition.
a.Organizational choice of many large accounting firms.
b.Partner's percentage allocation of current operating results.
c.Might affect any two partners' tax liabilities in different ways.
d.Brokerage and registration fees incurred for promoting and marketing partnership interests.
e.Transfer of asset to partnership followed by immediate distribution of cash to partner.
f.Must have at least one general partner.
g.Theory treating the partner and partnership as separate economic units.
h.Partner's basis in partnership interest after tax-free contribution of asset to partnership.
i.Partnership's basis in asset after tax-free contribution of asset to partnership.
j.Owners are "members."
k.Theory treating the partnership as a collection of taxpayers joined in an agency relationship.
l.Allows many unincorporated entities to select their Federal tax status.
m.No correct match provided.
-Carryover
(Short Answer)
4.9/5 (60)
(60) An examination of the RB Partnership's tax books provides the following information for the current year:
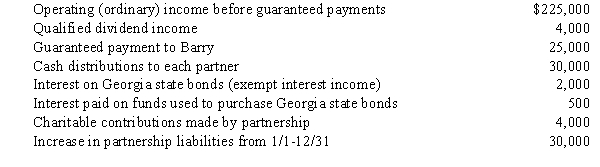 Barry is a 30% partner in partnership capital,profits,and losses.Assume the adjusted basis of his partnership interest is $50,000 at the beginning of the year,and he shares in 30% of the partnership liabilities for basis purposes.
a.What is Barry's adjusted basis for the partnership interest at the end of the year?
b.How much income must Barry report on his tax return for the current year? What is the character of income?
Barry is a 30% partner in partnership capital,profits,and losses.Assume the adjusted basis of his partnership interest is $50,000 at the beginning of the year,and he shares in 30% of the partnership liabilities for basis purposes.
a.What is Barry's adjusted basis for the partnership interest at the end of the year?
b.How much income must Barry report on his tax return for the current year? What is the character of income? (Essay)
4.9/5 (90)
(90) Match each of the following statements with the terms below that provide the best definition.
a.Operating expenses incurred after entity is formed but before it begins doing business.
b.Each partner's basis in the partnership.
c.Tax accounting election made by partnership.
d.Tax accounting calculation made by partner
e.Tax accounting election made by partner.
f.Designed to prevent excessive deferral of taxation of partnership income.
g.Amount that may be received by partner for performance of services for the partnership.
h.Adjusted basis of each partnership asset.
i.Computation that determines the way recourse debt is shared.
j.Will eventually be allocated to partner making tax-free property contribution to partnership.
k.Must be satisfied if a loss item is to be specially allocated to a partner.
l.Justification for a tax year other than the required taxable year.
m.No correct match is provided.
-Cost versus percentage depletion decision
(Short Answer)
5.0/5 (76)
(76) Match each of the following statements with the terms below that provide the best definition.
a.Operating expenses incurred after entity is formed but before it begins doing business.
b.Each partner's basis in the partnership.
c.Tax accounting election made by partnership.
d.Tax accounting calculation made by partner
e.Tax accounting election made by partner.
f.Designed to prevent excessive deferral of taxation of partnership income.
g.Amount that may be received by partner for performance of services for the partnership.
h.Adjusted basis of each partnership asset.
i.Computation that determines the way recourse debt is shared.
j.Will eventually be allocated to partner making tax-free property contribution to partnership.
k.Must be satisfied if a loss item is to be specially allocated to a partner.
l.Justification for a tax year other than the required taxable year.
m.No correct match is provided.
-§ 179 deduction
(Short Answer)
4.7/5 (86)
(86) Jim and Marta created the JM Partnership by contributing $60,000 each.The $120,000 cash was used by the partnership to acquire a depreciable asset.The partnership agreement provides that the partners' capital accounts will be maintained in accordance with Reg.§ 1.704-1(b)(the "economic effect" Regulations)and that any partner with a deficit capital account will be required to restore that capital account when the partner's interest is liquidated.The partnership agreement provides that MACRS will be allocated 10% to Jim and 90% to Marta.All other items of partnership income,gain,loss,deduction,and credit will be allocated equally between the partners.If the first year MACRS is $20,000 and no other operating transactions occur,which of the following statements satisfies the economic effect test of the Regulations?
(Multiple Choice)
4.8/5 (77)
(77) René is a partner in the RST Partnership,which is not publicly traded.Her allocable share of RST's passive ordinary losses from a nonrealty activity for the current year is ($60,000).René has a $40,000 adjusted basis (outside basis)for her interest in RST (before deduction of any of the passive losses).Her amount "at risk" under § 465 is $30,000 (before deduction of any of the passive losses).She also has $25,000 of passive income from other sources.How much of her ($60,000)allocable loss can René deduct on her current year's tax return?
(Multiple Choice)
4.7/5 (81)
(81) In computing the ordinary income of a partnership,a deduction is generally allowed for:
(Multiple Choice)
4.8/5 (77)
(77) Match each of the following statements with the terms below that provide the best definition.
a.Organizational choice of many large accounting firms.
b.Partner's percentage allocation of current operating results.
c.Might affect any two partners' tax liabilities in different ways.
d.Brokerage and registration fees incurred for promoting and marketing partnership interests.
e.Transfer of asset to partnership followed by immediate distribution of cash to partner.
f.Must have at least one general partner.
g.Theory treating the partner and partnership as separate economic units.
h.Partner's basis in partnership interest after tax-free contribution of asset to partnership.
i.Partnership's basis in asset after tax-free contribution of asset to partnership.
j.Owners are "members."
k.Theory treating the partnership as a collection of taxpayers joined in an agency relationship.
l.Allows many unincorporated entities to select their Federal tax status.
m.No correct match provided.
-Limited liability partnership
(Short Answer)
4.9/5 (77)
(77) Match each of the following statements with the terms below that provide the best definition.
a.Operating expenses incurred after entity is formed but before it begins doing business.
b.Each partner's basis in the partnership.
c.Tax accounting election made by partnership.
d.Tax accounting calculation made by partner
e.Tax accounting election made by partner.
f.Designed to prevent excessive deferral of taxation of partnership income.
g.Amount that may be received by partner for performance of services for the partnership.
h.Adjusted basis of each partnership asset.
i.Computation that determines the way recourse debt is shared.
j.Will eventually be allocated to partner making tax-free property contribution to partnership.
k.Must be satisfied if a loss item is to be specially allocated to a partner.
l.Justification for a tax year other than the required taxable year.
m.No correct match is provided.
-Business purpose
(Short Answer)
4.8/5 (76)
(76) A partnership will take a carryover basis in an asset it acquires when:
(Multiple Choice)
4.9/5 (68)
(68) On January 1 of the current year,Sarah and Bart form an equal partnership.Sarah makes a cash contribution of $60,000 and a property contribution (adjusted basis of $160,000; fair market value of $140,000)in exchange for her interest in the partnership.Bart contributes property (adjusted basis of $120,000; fair market value of $200,000)in exchange for his partnership interest.Which of the following statements is true concerning the income tax results of this partnership formation?
(Multiple Choice)
4.7/5 (73)
(73) Alicia and Barry form the AB Partnership at the start of the current year with a land contribution by Barry and a cash contribution by Alicia.Barry's contributed property is subject to a recourse mortgage assumed by the partnership.Immediately after formation,Barry has an 80% interest in AB's profits and losses.The land has been held by Barry for the past 6 years as an investment.It will be used by AB as an operating asset in its parking lot business.Which of the following statements is correct?
(Multiple Choice)
4.9/5 (75)
(75) Match each of the following statements with the terms below that provide the best definition.
a.Organizational choice of many large accounting firms.
b.Partner's percentage allocation of current operating results.
c.Might affect any two partners' tax liabilities in different ways.
d.Brokerage and registration fees incurred for promoting and marketing partnership interests.
e.Transfer of asset to partnership followed by immediate distribution of cash to partner.
f.Must have at least one general partner.
g.Theory treating the partner and partnership as separate economic units.
h.Partner's basis in partnership interest after tax-free contribution of asset to partnership.
i.Partnership's basis in asset after tax-free contribution of asset to partnership.
j.Owners are "members."
k.Theory treating the partnership as a collection of taxpayers joined in an agency relationship.
l.Allows many unincorporated entities to select their Federal tax status.
m.No correct match provided.
-Check the box regulations
(Short Answer)
4.8/5 (84)
(84) Match each of the following statements with the terms below that provide the best definition.
a.Operating expenses incurred after entity is formed but before it begins doing business.
b.Each partner's basis in the partnership.
c.Tax accounting election made by partnership.
d.Tax accounting calculation made by partner
e.Tax accounting election made by partner.
f.Designed to prevent excessive deferral of taxation of partnership income.
g.Amount that may be received by partner for performance of services for the partnership.
h.Adjusted basis of each partnership asset.
i.Computation that determines the way recourse debt is shared.
j.Will eventually be allocated to partner making tax-free property contribution to partnership.
k.Must be satisfied if a loss item is to be specially allocated to a partner.
l.Justification for a tax year other than the required taxable year.
m.No correct match is provided.
-Domestic production activities deduction
(Short Answer)
4.9/5 (75)
(75) Match each of the following statements with the terms below that provide the best definition.
a.Operating expenses incurred after entity is formed but before it begins doing business.
b.Each partner's basis in the partnership.
c.Tax accounting election made by partnership.
d.Tax accounting calculation made by partner
e.Tax accounting election made by partner.
f.Designed to prevent excessive deferral of taxation of partnership income.
g.Amount that may be received by partner for performance of services for the partnership.
h.Adjusted basis of each partnership asset.
i.Computation that determines the way recourse debt is shared.
j.Will eventually be allocated to partner making tax-free property contribution to partnership.
k.Must be satisfied if a loss item is to be specially allocated to a partner.
l.Justification for a tax year other than the required taxable year.
m.No correct match is provided.
-Organization costs
(Short Answer)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)