



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


The right to file on a consolidated basis is available to a group of corporations when they constitute a parent-subsidiary controlled group.
(True/False)
4.8/5  (74)
(74) If one member sells an asset with a realized gain to another member of an affiliated group,the gain on the transaction is not recognized at that time; such a deferral applies the ____________________ rule.
(Short Answer)
4.9/5 (81)
(81) Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return.
a.Advantage of consolidating
b.Disadvantage of consolidating
-Binding nature of election over multiple tax years
(Short Answer)
4.9/5 (85)
(85) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
a.Group item
b.Not a group item
-Domestic production activities deduction (DPAD)
(Short Answer)
4.9/5 (84)
(84) When a member departs a consolidated group,it forfeits the use of any NOLs it generated while in the group.
(True/False)
4.9/5 (74)
(74) When a subsidiary sells to the parent some business-use property that has appreciated from its $20,000 basis to a $50,000 fair market value,the subsidiary immediately recognizes $30,000 ordinary income.
(True/False)
4.9/5 (77)
(77) Which of the following is eligible to join in a Federal consolidated return?
(Multiple Choice)
4.7/5 (71)
(71) If subsidiary stock is redeemed or sold outside the group when an excess loss account exists,the selling parent corporation recognizes ordinary income equal to the account balance.
(True/False)
4.8/5 (80)
(80) ParentCo's separate taxable income was $100,000,and SubCo's was $40,000.Consolidated taxable income before contributions was $125,000.Charitable contributions made by the affiliated group included $20,000 by ParentCo and $30,000 by SubCo.Compute the group's maximum charitable contribution deduction.
(Multiple Choice)
4.9/5 (82)
(82) ParentCo purchased all of the stock of SubCo on January 2,2008,and the two companies filed consolidated returns for 2008 and thereafter.Both entities were incorporated in 2007.Taxable income computations for the members include the following.Neither group member incurred any capital gain or loss transactions during these years,nor did they make any charitable contributions.No § 382 limit applies.
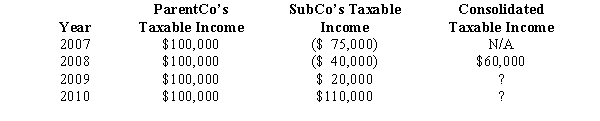 To what extent can SubCo's 2007 losses be used by the group in 2010?
 (Multiple Choice)
4.9/5 (71)
(71) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
a.Group item
b.Not a group item
-Compensation deductions
(Short Answer)
4.9/5 (74)
(74) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
a.Increases stock basis
b.Decreases stock basis
c.No effect on stock basis
-Member's operating loss
(Short Answer)
4.7/5 (82)
(82) A Federal consolidated group can claim a dividends received deduction for payments among the affiliates.
(True/False)
4.9/5 (80)
(80) Summarize how the SRLY rules limit the consolidated group's deduction of member NOLs.
(Essay)
4.9/5 (85)
(85) An example of an intercompany transaction is the use of the customer databases of the parent corporation by a subsidiary for an arm's length management fee.
(True/False)
4.9/5 (82)
(82) The consolidated return rules combine the members' transactions involving ____________________ items when computing consolidated taxable income.
(Short Answer)
4.8/5 (89)
(89) The group of Parent Corporation,SubOne,and SubTwo has filed a consolidated return since 2008.The first two entities were incorporated in 2007,and SubTwo came into existence in 2008 through an asset spin-off from Parent.Taxable income computations for the members are shown below.None of the group members incurred any capital gain or loss transactions during 2007-2010,nor did they make any charitable contributions.
Describe the treatment of the group's 2009 consolidated NOL.Hint: Apply the offspring rule.
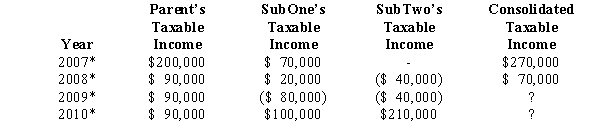 * Consolidated return year.
 (Essay)
4.8/5 (84)
(84) Keep Corporation joined an affiliated group by merger in 2005.The group generated a consolidated 2009 NOL,and Keep's share of the loss was $50,000.If the parent elects to forgo an NOL carryback,refunds or tax reductions resulting from the loss are received solely by the parent,and not by Keep separately.
(True/False)
4.9/5 (80)
(80) Affiliates must keep track of their shares of a consolidated NOL.
(True/False)
4.8/5 (67)
(67) Members of a consolidated group ____________________ (can/cannot)use different inventory methods.
(Short Answer)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)