



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law72 Questions
Exam 2: Corporations: Introduction and Operating Rules103 Questions
Exam 3: Corporations: Special Situations76 Questions
Exam 4: Corporations: Organization and Capital Structure91 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions82 Questions
Exam 6: Corporations: Redemptions and Liquidations107 Questions
Exam 7: Corporations: Reorganizations138 Questions
Exam 8: Consolidated Tax Returns143 Questions
Exam 9: Taxation of International Transactions142 Questions
Exam 10: Partnerships: Formation, operation, and Basis71 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations84 Questions
Exam 12: S Corporations161 Questions
Exam 13: Comparative Forms of Doing Business139 Questions
Exam 14: Exempt Entities159 Questions
Exam 15: Multistate Corporate Taxation169 Questions
Exam 16: Tax Practice and Ethics147 Questions
Exam 17: The Federal Gift and Estate Taxes199 Questions
Exam 18: Family Tax Planning168 Questions
Exam 19: Income Taxation of Trusts and Estates155 Questions
Select questions type


List the filing requirements that must be met by a Federal consolidated group.
(Essay)
4.9/5  (84)
(84) Outline the major advantages and disadvantages of filing Federal corporate income tax returns on a consolidated basis. Limit your comments to the income tax effects of the election.
(Essay)
4.7/5 (87)
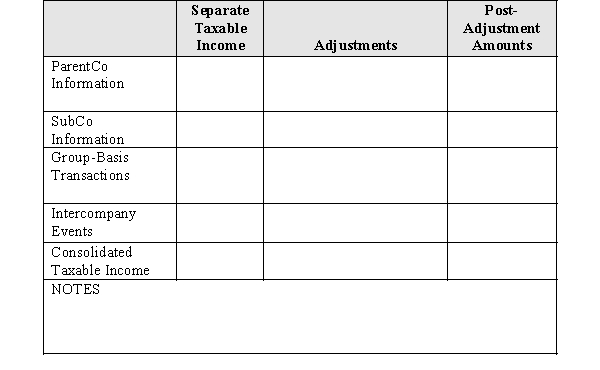
(87) Parent Corporation's current-year taxable income included $100,000 net income from operations and a $40,000 net long-term capital gain.Parent also made a $19,000 contribution to State University.SubCo produced $75,000 income from operations and incurred a $50,000 net short-term capital loss.
Use the computational worksheet of Figure 8-2 to derive the group members' separate taxable incomes and the group's consolidated taxable income.
(Essay)
4.8/5 (77)
(77) ParentCo and SubCo had the following items of income and deduction for the current year.
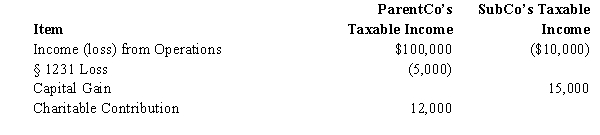 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.8/5 (74)
(74) How many consolidated tax returns are filed annually? What types of taxpayer do they represent?
(Essay)
4.7/5 (70)
(70) ParentCo owned 100% of SubCo for the entire year.ParentCo uses the accrual method of tax accounting,whereas SubCo uses the cash method.During the year,SubCo sold raw materials to ParentCo for $35,000 under a contract that requires no payment to SubCo until the following year.
Exclusive of this transaction,ParentCo had income for the year of $80,000,and SubCo had income of $50,000.The group's consolidated taxable income for the year was:
(Multiple Choice)
4.9/5 (74)
(74) All affiliates joining in a newly formed consolidated return must consent to the election on Form 1122,as attached to the tax return for the group.
(True/False)
4.8/5 (84)
(84) Which of the following tax items is not likely to be considered when a group of related corporations is evaluating the election to file on a consolidated basis?
(Multiple Choice)
4.7/5 (72)
(72) ParentCo and SubOne have filed consolidated returns since 2006.SubTwo was formed in 2009 through an asset spin-off from ParentCo.SubTwo has joined in the filing of consolidated returns since then.Taxable income computations for the members include the following.None of the group members incurred any capital gain or loss transactions during these years,nor did they make any charitable contributions.
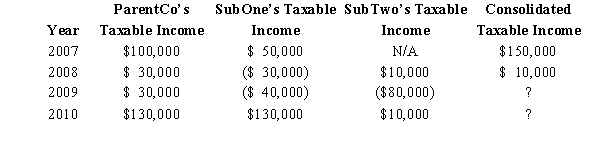 If ParentCo does not elect to forgo the carryback of the 2009 net operating loss,what portion of the 2009 consolidated net operating loss is carried back to offset prior years' income?
 (Multiple Choice)
4.8/5 (77)
(77) ParentCo,SubOne and SubTwo have filed consolidated returns since 2008.All of the entities were incorporated in 2007.Taxable income computations for the members include the following.None of the group members incurred any capital gain or loss transactions during these years,nor did they make any charitable contributions.
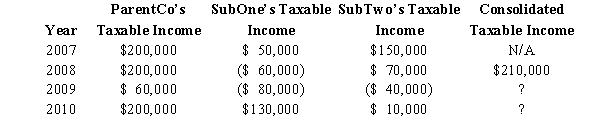 How should the 2009 consolidated net operating loss be apportioned among the group members?
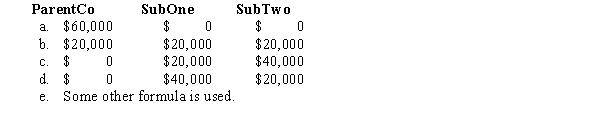
How should the 2009 consolidated net operating loss be apportioned among the group members?
(Short Answer)
4.9/5 (71)
(71) Most of the rules governing the use of consolidated returns are found in _________________________ regulations adopted since 1969.
(Short Answer)
4.8/5 (82)
(82) The starting point in computing consolidated taxable income is the separate Federal taxable income amounts of the affiliated group members.
(True/False)
4.9/5 (85)
(85) Conformity among the members of a consolidated group must be implemented for which of the following tax items?
(Multiple Choice)
4.8/5 (65)
(65) The § 1231 gain of a consolidated group can be less than the sum of the gains from asset sales of the group members when filing separately.
(True/False)
4.8/5 (80)
(80) In terms of the consolidated return rules,non-U.S.corporations,tax-exempt entities,limited liability companies,partnerships,and trusts are ____________________ corporations.
(Short Answer)
5.0/5 (77)
(77) ParentCo purchased all of SubCo's stock on January 1,2008,and the companies have filed consolidated returns since 2008.Taxable income computations for the members include the following.Neither group member incurred any capital gain or loss transactions during these years,nor did they make any charitable contributions.
The 2009 net operating loss:
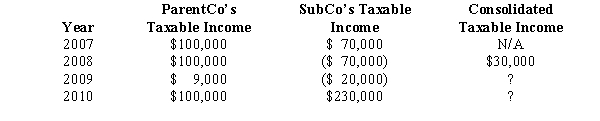
(Multiple Choice)
4.9/5 (89)
(89) Over time,the consolidated return rules have shifted from penalizing joint filing to an encouragement for conglomerates to elect to file on a consolidated basis.
(True/False)
4.8/5 (83)
(83) The domestic production activities deduction (DPAD)of a consolidated group can be greater than the sum of the deductions of the group members when filing separately.
(True/False)
4.8/5 (84)
(84) In computing consolidated taxable income,a distribution from Subsidiary to Parent is an example of a(n)_________________________ item.
(Short Answer)
4.8/5 (85)
(85) Which of the following is not generally a disadvantage of filing tax returns on a consolidated basis?
(Multiple Choice)
4.7/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)