



 Chat with AI
Exam 2: Corporate Formations and Capital Structure


Discuss the tax planning opportunities that are available in forming a corporation when one of the parties owns property that has a high basis and a low FMV.

 (85)
 Verified
The plan should be formulated to allow the contributor to avoid Sec.351 and be able to recognize the loss.This can be done by having the transferor sell the property to an unrelated party and then have the transferor contribute cash.The transferor must be careful to avoid the related party rules of Sec.267,which could prevent the loss from being recognized if the property is sold directly to the corporation.Several other suggestions are explored on pages C:2-34 and C:2-35.
Anton,Bettina,and Caleb form Cage Corporation.Each contributes appreciated property worth $10,000 for one-third of the Cage stock.Before the exchange,Anton arranges to sell his stock to Darma as soon as he receives it.Does Sec.351 apply?
(85) VerifiedNo,this prearranged plan means Anton,Bettina,and Caleb do not have control immediately after the exchange,so Sec.351 does not apply.
This year,John,Meg,and Karen form Frost Corporation.John contributes land purchased as an investment four years ago for $15,000 that has a $30,000 FMV in exchange for 30 shares of Frost stock.Meg contributes machinery purchased four years ago and used in her business having a $35,000 adjusted basis and a $30,000 FMV in exchange for 30 shares of Frost stock.Karen contributes services worth $20,000 in exchange for 20 shares of Frost stock.
a)What is the amount of John's recognized gain or loss?
b)What is John's basis in his Frost shares? When does his holding period begin?
c)What is the amount of Meg's recognized gain or loss?
d)What is Meg's basis in her Frost shares? When does her holding period begin?
e)How much income,if any,must Karen recognize?
f)What is Karen's basis in her Frost shares? When does her holding period begin?
g)What is Frost Corporation's basis in the land and the machinery? When does its holding period begin? How does Frost Corporation treat the amount paid to Karen for her services?
(77) Verifieda)Since Sec.351 does not apply because 25% (20 shares out of 80 total shares)of the stock is issued for services,John must recognize $15,000 of capital gain.
b)John's basis in his shares is $30,000 and his holding period begins on the day after the exchange date.
c)Meg recognizes a $5,000 Sec.1231 loss.
d)Meg's basis in her shares is $30,000 and her holding period begins on the day after the exchange date.
e)Karen must recognize $20,000 of ordinary income.
f)Karen's basis in her shares is $20,000.Her holding period begins on the day after the exchange date.
g)Frost Corporation has a $30,000 basis in the land and a $30,000 basis in the machinery.Its holding period for each asset begins on the day after the exchange date.The services,if capitalized,would have a $20,000 basis.The services may be amortizable if they are organizational or start-up expenditures.
Sarah transfers property with an $80,000 adjusted basis and a $100,000 FMV to Super Corporation in a Sec.351 transaction.Sarah receives stock with an $85,000 FMV and a short-term note with a $15,000 FMV.Sarah's basis in the stock is
(83) The City of Springfield donates land worth $250,000 to Deuce Corporation to induce it to locate in Springfield and provide 1,000 jobs for its citizens.How much gross income must Deuce Corporation recognize because of the land contribution,and what is the land's basis to Deuce Corporation?
(87) On May 1 of the current year,Kiara,Victor,Pam,and Joe form Newco Corporation with the following investments:
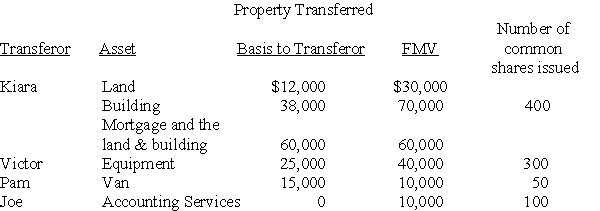 Kiara purchased the land and building several years ago for $12,000 and $50,000,respectively.Kiara has claimed straight-line depreciation on the building.Victor also received a Newco Corporation note for $10,000 due in three years.The note bears interest at a rate acceptable to the IRS.Victor purchased the equipment three years ago for $50,000.Pam also receives $5,000 cash.Pam purchased the van two years ago for $20,000.
a)Does the transaction satisfy the requirements of Sec.351?
b)What are the amounts and character of the reorganized gains or losses to Kiara,Victor,Pam,Joe,and Newco Corporation?
c)What is each shareholder's basis for his or her Newco stock? When does the holding period for the stock begin?
d)What is Newco Corporation's basis for its property and services? When does its holding period begin for each property?
Kiara purchased the land and building several years ago for $12,000 and $50,000,respectively.Kiara has claimed straight-line depreciation on the building.Victor also received a Newco Corporation note for $10,000 due in three years.The note bears interest at a rate acceptable to the IRS.Victor purchased the equipment three years ago for $50,000.Pam also receives $5,000 cash.Pam purchased the van two years ago for $20,000.
a)Does the transaction satisfy the requirements of Sec.351?
b)What are the amounts and character of the reorganized gains or losses to Kiara,Victor,Pam,Joe,and Newco Corporation?
c)What is each shareholder's basis for his or her Newco stock? When does the holding period for the stock begin?
d)What is Newco Corporation's basis for its property and services? When does its holding period begin for each property? (86) What is the impact on a transferor if a Sec.351 exchange involves the assumption of the shareholder's liabilities by the corporation?
(83) Rose and Wayne form a new corporation.Rose contributes cash for 85% of the stock and Wayne contributes services for 15% of the stock.The tax effect is
(85) In which of the following independent situations is the Sec.351 control requirement met?
a)Jane transfers property to Jet Corporation for 75% of Jet Corporation's stock,and Susan provides services to Jet Corporation for the remaining 25% of Jet Corporation stock.
b)Paul transfers property to Pride Corporation for 60% of Pride's stock,and Bob transfers property worth $15,000 and performs services worth $25,000 for the remaining 40% of Pride's stock.
c)Herb and his wife Carolyn each have owned 50% of the 100 outstanding shares of Wykert Corporation stock since it was formed three years ago.In the current year,their daughter,Cindy,transfers property to Wykert Corporation for 50 newly issued shares of Wykert stock.
d)John and Pam develop a plan to form PJ Corporation on May 2 of this year.John transfers property worth $50,000 for 50 shares of PJ Corporation stock.As part of the single plan to incorporate,Pam transfers $50,000 cash for 50 shares of PJ Corporation stock on July 1.
e)Assume the same facts as in Part (d),except that John has a prearranged plan to sell 30 of his shares to Steven on September 1.
(82) Michael contributes equipment with a $25,000 adjusted basis and a $40,000 FMV to Miller Corporation for 25 of its 50 shares of stock.His son,Michael Jr.,contributes $10,000 cash for the remaining 25 Miller shares.What tax issues should Michael and his son consider with respect to the stock acquisitions?
(79) Several years ago,John acquired 200 shares of Jersey Corporation stock directly from the corporation for $150,000 in cash.This year,he sold the stock to Bill for $85,000.What tax issues should John consider with respect to the stock sale?
(82) Ralph and Yolanda purchased 20% of the initial offering of Major Corporation common stock for $150,000.Major Corporation is a qualifying small business corporation and the stock qualifies as Sec.1244 stock.Ten months later,Major Corporation files for bankruptcy and the shareholders are notified that the stock is worthless.Ralph and Yolanda,who are married and file a joint return,have a
(78) Gene purchased land five years ago as an investment.The land cost him $200,000 and is now worth $530,000.Gene plans to transfer the land to Dee Corporation,which will subdivide the land and sell individual parcels.Dee Corporation's profits on the land will be ordinary income.What are the tax consequences of the asset transfer and land sales if Gene contributes the land to Dee Corporation in exchange for all of its stock? What alternative methods can be used to structure the transaction to achieve better tax consequences?
(89) Joan transfers land (a capital asset)having a $20,000 adjusted basis to Jet Corporation in a transaction qualifying under Sec.351.In exchange,she received 50 shares of Jet Corporation common stock valued at $50,000,a $15,000 Jet Corporation bond due in 10 years,and a $10,000 Jet Corporation note due in 3 years.What tax issues should Joan consider with respect to the transfer?
a)What is the amount of Joan's realized gain or loss? What is the amount of Joan's recognized gain or loss? What is the character of Joan's recognized gain or loss?
b)What is Joan's basis in her stock? What is Joan's basis in the bond? What is Joan's basis in the note?
c)What is Jet Corporation's basis in the land?
(77) Demarcus is a 50% partner in the DJ partnership.DJ has taxable income for the year of $200,000.Demarcus received a $75,000 distribution from the partnership.What amount of income related to DJ must Demarcus recognize?
(99) Silvia transfers to Leaf Corporation a machine she had purchased a year ago for $50,000.The machine has a $40,000 adjusted basis and a $55,000 FMV on the transfer date.$10,000 in depreciation was claimed by Silvia prior to the transfer.Silvia receives all 1,000 shares of Leaf Corporation stock worth $50,000 and a two-year note with a $5,000 FMV.What is the amount and character of the recognized gain or loss?
(98) Will,a shareholder in Wiley Corporation,lent money to the corporation.The corporation is unable to repay him.What tax issues should Will consider with respect to the loan?
(79) The City of Seattle gives Dotcom Corporation $120,000 cash and land worth $200,000 to induce it to relocate to Seattle.Dotcom Corporation did not spend the cash during the 12 months following the contribution.What are the tax consequences to Dotcom Corporation with respect to the contribution?
(93) Frans and Arie own 75 shares and 25 shares of Vogel Corporation stock,respectively.There are no other owners.Frans transfers property with a $30,000 adjusted basis and a $50,000 FMV to Vogel Corporation in exchange for an additional 25 shares of Vogel stock.Does this property-for-stock exchange qualify for Sec.351 treatment?
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)