



 Chat with AI
Exam 15: Option Valuation

Exam 1: The Corporation42 Questions
Exam 2: Introduction to Financial Statement Analysis74 Questions
Exam 3: Arbitrage and Financial Decision Making79 Questions
Exam 4: The Time Value of Money84 Questions
Exam 5: Interest Rates69 Questions
Exam 6: Valuing Bonds104 Questions
Exam 7: Valuing Stocks88 Questions
Exam 8: Investment Decision Rules83 Questions
Exam 9: Fundamentals of Capital Budgeting94 Questions
Exam 10: Capital Markets and the Pricing of Risk98 Questions
Exam 11: Optimal Portfolio Choice and the Capital Asset Pricing Model108 Questions
Exam 12: Estimating the Cost of Capital108 Questions
Exam 13: Investor Behaviour and Capital Market Efficiency74 Questions
Exam 14: Financial Options56 Questions
Exam 15: Option Valuation42 Questions
Exam 16: Real Options57 Questions
Exam 17: Capital Structure in a Perfect Market86 Questions
Exam 18: Debt and Taxes84 Questions
Exam 19: Financial Distress, managerial Incentives, and Information99 Questions
Exam 20: Payout Policy92 Questions
Exam 21: Capital Budgeting and Valuation With Leverage94 Questions
Exam 22: Valuation and Financial Modelling: a Case Study47 Questions
Exam 23: The Mechanics of Raising Equity Capital49 Questions
Exam 24: Debt Financing49 Questions
Exam 25: Leasing58 Questions
Exam 26: Working Capital Management45 Questions
Exam 27: Short-Term Financial Planning49 Questions
Exam 28: Mergers and Acquisitions52 Questions
Exam 29: Corporate Governance49 Questions
Exam 30: Risk Management52 Questions
Exam 31: International Corporate Finance45 Questions
Select questions type


Use the information for the question(s) below.
The current price of Kinston Corporation stock is $10. In each of the next two years, this stock price can either go up by $3.00 or go down by $2.00. Kinston stock pays no dividends. The one year risk-free interest rate is 5% and will remain constant.
-Using risk-neutral probabilities,calculate the price of a two-year put option on Kinston stock with a strike price of $9.
(Essay)
4.8/5  (91)
(91) Risk-neutral probabilities are known by other names as well: ________.
(Multiple Choice)
4.9/5 (89)
(89) Construct a binomial tree detailing the option information and payoffs for a call option on KD stock with a $20 strike price that expires in one year.
(Essay)
5.0/5 (71)
(71) Luther Industries does not pay dividend and is currently trading at $25 per share.The current risk-free rate of interest is 5%.Calculate the price of a call option on Luther Industries with a strike price of $30 that expires in 75 days when N(d1)= .639 and N(d2)= .454.
(Essay)
4.9/5 (69)
(69) Consider the following equation: C = S × N 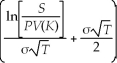 - PV(K)× N
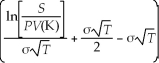 In this equation,the term σ represents
- PV(K)× N In this equation,the term σ represents (Multiple Choice)
4.9/5 (93)
(93) Consider the following equation: C = S × N 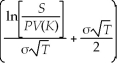 - PV(K)× N
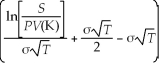 In this equation,the term S represents
- PV(K)× N In this equation,the term S represents (Multiple Choice)
4.7/5 (77)
(77) Consider the following equation: bE = D  bU = D
 bU
The term D refers to
bU = D bU
The term D refers to (Multiple Choice)
4.9/5 (71)
(71) Consider the following equation: bE = D  bU = D
 bU
The term bU refers to
bU = D bU
The term bU refers to (Multiple Choice)
4.9/5 (80)
(80) Consider the following equation: B =  In this equation,the term B represents
 (Multiple Choice)
4.9/5 (83)
(83) Risk-neutral probabilities are also known as all of the following EXCEPT
(Multiple Choice)
4.7/5 (73)
(73) Consider the following equation: boption =  bS +
 bB
The term
 bB is
bS + bB
The term bB is (Multiple Choice)
4.8/5 (81)
(81) ________ have the highest expected returns and ________ have the lowest expected returns.
(Multiple Choice)
4.9/5 (89)
(89) Use the information for the question(s) below.
The current price of KD Industries' stock is $20. In the next year the stock price will either go up by 20% or go down by 20%. KD pays no dividends. The one year risk-free rate is 5% and will remain constant.
-Using the binomial pricing model,the calculated price of a one-year put option on KD stock with a strike price of $20 is closest to:
(Multiple Choice)
4.8/5 (68)
(68) You would like to know the beta of debt for KT Industries.The value of KT's outstanding equity is $50 million,and you have estimated its beta to be 1.62.You cannot,however,find enough market data to estimate the beta of its debt,so you decide to use the Black-Scholes formula to find an approximate value for the debt.KT has a five year zero coupon bond outstanding with a market value of $80 million.If the estimated D from the Black-Scholes model is .60,then the beta for KT's debt is closest to:
(Multiple Choice)
5.0/5 (72)
(72) Use the information for the question(s) below.
The current price of Kinston Corporation stock is $10. In each of the next two years, this stock price can either go up by $3.00 or go down by $2.00. Kinston stock pays no dividends. The one year risk-free interest rate is 5% and will remain constant.
-Using the binomial pricing model,calculate the price of a two-year call option on Kinston stock with a strike price of $9.
(Essay)
4.9/5 (85)
(85) Use the information for the question(s) below.
The current price of KD Industries' stock is $20. In the next year the stock price will either go up by 20% or go down by 20%. KD pays no dividends. The one year risk-free rate is 5% and will remain constant.
-Using the binomial pricing model,the calculated price of a one-year call option on KD stock with a strike price of $20 is closest to:
(Multiple Choice)
4.8/5 (64)
(64) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)