



 Chat with AI
Exam 11: Optimal Portfolio Choice and the Capital Asset Pricing Model

Exam 1: The Corporation42 Questions
Exam 2: Introduction to Financial Statement Analysis74 Questions
Exam 3: Arbitrage and Financial Decision Making79 Questions
Exam 4: The Time Value of Money84 Questions
Exam 5: Interest Rates69 Questions
Exam 6: Valuing Bonds104 Questions
Exam 7: Valuing Stocks88 Questions
Exam 8: Investment Decision Rules83 Questions
Exam 9: Fundamentals of Capital Budgeting94 Questions
Exam 10: Capital Markets and the Pricing of Risk98 Questions
Exam 11: Optimal Portfolio Choice and the Capital Asset Pricing Model108 Questions
Exam 12: Estimating the Cost of Capital108 Questions
Exam 13: Investor Behaviour and Capital Market Efficiency74 Questions
Exam 14: Financial Options56 Questions
Exam 15: Option Valuation42 Questions
Exam 16: Real Options57 Questions
Exam 17: Capital Structure in a Perfect Market86 Questions
Exam 18: Debt and Taxes84 Questions
Exam 19: Financial Distress, managerial Incentives, and Information99 Questions
Exam 20: Payout Policy92 Questions
Exam 21: Capital Budgeting and Valuation With Leverage94 Questions
Exam 22: Valuation and Financial Modelling: a Case Study47 Questions
Exam 23: The Mechanics of Raising Equity Capital49 Questions
Exam 24: Debt Financing49 Questions
Exam 25: Leasing58 Questions
Exam 26: Working Capital Management45 Questions
Exam 27: Short-Term Financial Planning49 Questions
Exam 28: Mergers and Acquisitions52 Questions
Exam 29: Corporate Governance49 Questions
Exam 30: Risk Management52 Questions
Exam 31: International Corporate Finance45 Questions
Select questions type


Use the table for the question(s) below.
Consider the following covariances between securities:
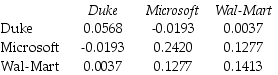 -What is the variance on a portfolio that has $2,000 invested in Duke Energy,$3,000 invested in Microsoft,and $5,000 invested in Wal-Mart stock?
 (Essay)
4.9/5  (78)
(78) Suppose over the next year Ball has a return of 12.5%,Lowes has a return of 20%,and Abbott Labs has a return of -10%.The return on your portfolio over the year is:
(Multiple Choice)
4.7/5 (80)
(80) The efficient portfolio provides the benchmark that identifies ________ present in the economy.
(Multiple Choice)
4.9/5 (83)
(83) The risk of a portfolio depends on how each stock's ________ moves in relation to it.
(Multiple Choice)
4.9/5 (94)
(94) Suppose over the next year Ball has a return of 12.5%,Lowes has a return of 20%,and Abbott Labs has a return of -10%.The weight of Lowes in your portfolio after one year is closest to:
(Multiple Choice)
4.8/5 (78)
(78) Use the table for the question(s) below.
Consider the following returns:
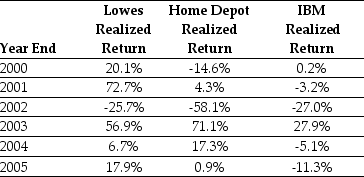 -The covariance between Lowes' and Home Depot's returns is closest to:
 (Multiple Choice)
4.8/5 (69)
(69) Use the information for the question(s) below.
You are presently invested in the Luther Fund, a broad-based mutual fund that invests in stocks and other securities. The Luther Fund has an expected return of 14% and a volatility of 20%. Risk-free Treasury Bills are currently offering returns of 4%. You are considering adding a precious metals fund to your current portfolio. The metals fund has an expected return of 10%, a volatility of 30%, and a correlation of -.20 with the Luther Fund.
-The beta of the precious metals fund with the Luther Fund  is closest to:
 (Multiple Choice)
4.9/5 (89)
(89) Use the table for the question(s) below.
Consider the following expected returns, volatilities, and correlations:
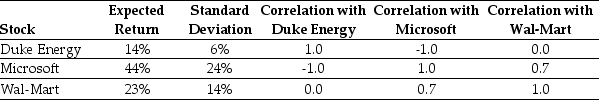 -Consider a portfolio consisting of only Duke Energy and Microsoft. The percentage of your investment (portfolio weight)that you would place in Duke Energy stock to achieve a risk-free investment would be closest to:
 (Multiple Choice)
4.7/5 (68)
(68) CAPM states that the investment's expected return should match the expected return of the ________ portfolio with the same level of market risk.
(Multiple Choice)
4.7/5 (88)
(88) Suppose over the next year Ball has a return of 12.5%,Lowes has a return of 20%,and Abbott Labs has a return of -10%.The weight of Ball Corporation in your portfolio after one year is closest to:
(Multiple Choice)
4.8/5 (76)
(76) Use the table for the question(s) below.
Consider the following returns:
-The variance on a portfolio that is made up of equal investments in Lowes and IBM stock is closest to:
-The variance on a portfolio that is made up of equal investments in Lowes and IBM stock is closest to: (Multiple Choice)
4.8/5 (79)
(79) Use the table for the question(s) below.
Consider the following covariances between securities:
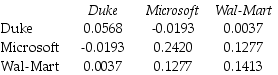 -The variance on a portfolio that is made up of a $6,000 investment in Duke Energy stock and a $4,000 investment in Wal-Mart stock is closest to:
 (Multiple Choice)
4.9/5 (85)
(85) Use the information for the question(s) below.
Suppose that you currently have $250,000 invested in a portfolio with an expected return of 12% and a volatility of 10%. The efficient (tangent) portfolio has an expected return of 17% and a volatility of 12%. The risk-free rate of interest is 5%.
-The Sharpe ratio for the efficient portfolio is closest to:
(Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)