



 Chat with AI
Exam 6: Valuing Bonds

Exam 1: The Corporation42 Questions
Exam 2: Introduction to Financial Statement Analysis74 Questions
Exam 3: Arbitrage and Financial Decision Making79 Questions
Exam 4: The Time Value of Money84 Questions
Exam 5: Interest Rates69 Questions
Exam 6: Valuing Bonds104 Questions
Exam 7: Valuing Stocks88 Questions
Exam 8: Investment Decision Rules83 Questions
Exam 9: Fundamentals of Capital Budgeting94 Questions
Exam 10: Capital Markets and the Pricing of Risk98 Questions
Exam 11: Optimal Portfolio Choice and the Capital Asset Pricing Model108 Questions
Exam 12: Estimating the Cost of Capital108 Questions
Exam 13: Investor Behaviour and Capital Market Efficiency74 Questions
Exam 14: Financial Options56 Questions
Exam 15: Option Valuation42 Questions
Exam 16: Real Options57 Questions
Exam 17: Capital Structure in a Perfect Market86 Questions
Exam 18: Debt and Taxes84 Questions
Exam 19: Financial Distress, managerial Incentives, and Information99 Questions
Exam 20: Payout Policy92 Questions
Exam 21: Capital Budgeting and Valuation With Leverage94 Questions
Exam 22: Valuation and Financial Modelling: a Case Study47 Questions
Exam 23: The Mechanics of Raising Equity Capital49 Questions
Exam 24: Debt Financing49 Questions
Exam 25: Leasing58 Questions
Exam 26: Working Capital Management45 Questions
Exam 27: Short-Term Financial Planning49 Questions
Exam 28: Mergers and Acquisitions52 Questions
Exam 29: Corporate Governance49 Questions
Exam 30: Risk Management52 Questions
Exam 31: International Corporate Finance45 Questions
Select questions type


Use the information for the question(s) below.
The Sisyphean Company has a bond outstanding with a face value of $1,000 that reaches maturity in 15 years. The bond certificate indicates that the stated coupon rate for this bond is 8% and that the coupon payments are to be made semi-annually.
-Assuming the appropriate YTM on the Sisyphean bond is 7.5%,then the price that this bond trades for will be closest to:
(Multiple Choice)
4.9/5  (86)
(86) What is the price today of a two-year,default-free security with a face value of $1,000 and an annual coupon rate of 5.75%? Does this bond trade at a discount,premium,or at par?
(Essay)
4.8/5 (62)
(62) The discount rate that sets the present value of the promised bond payments equal to the current market price of the bond is called
(Multiple Choice)
4.7/5 (80)
(80) Consider a bond that pays annually an 8% coupon with 20 years to maturity.The percentage change in the price of the bond if its yield to maturity increases from 5% to 7% is closest to:
(Multiple Choice)
4.9/5 (62)
(62) Use the table for the question(s) below.
Consider the following four bonds that pay annual coupons:
 -The amount that the price of bond "B" will change if its yield to maturity increases from 7% to 8% is closest to:
 (Multiple Choice)
4.9/5 (68)
(68) Use the table for the question(s) below.
Consider the following zero-coupon yields on default-free securities:
 -The forward rate for year 2 (the forward rate quoted today for an investment that begins in one year and matures in two years)is closest to:
 (Multiple Choice)
4.7/5 (69)
(69) Use the table for the question(s) below.
Consider the following four bonds that pay annual coupons:
-The amount that the price of bond "D" will change if its yield to maturity increases from 8% to 9% is closest to:
-The amount that the price of bond "D" will change if its yield to maturity increases from 8% to 9% is closest to: (Multiple Choice)
4.8/5 (75)
(75) Which of the four bonds is the least sensitive to a one percent increase in the YTM?
(Multiple Choice)
4.9/5 (80)
(80) Use the table for the question(s) below.
Consider the following four bonds that pay annual coupons:
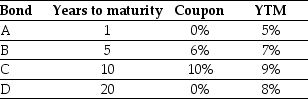 -Assume that the YTM increases by 1% for each of the four bonds listed.Rank the bonds based upon the sensitivity of their prices from least to most sensitive.
 (Essay)
4.7/5 (92)
(92) Use the table for the question(s) below.
Consider the following zero-coupon yields on default-free securities:
 -The price today of a 3-year default-free security with a face value of $1,000 and an annual coupon rate of 6% is closest to:
 (Multiple Choice)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)