



 Chat with AI
Exam 22: Options and Corporate Finance

Exam 1: Introduction to Corporate Finance71 Questions
Exam 2: Financial Statements and Cash Flow106 Questions
Exam 3: Financial Statements and Cash Flow108 Questions
Exam 4: Discounted Cash Flow Valuation116 Questions
Exam 5: Net Present Value and Other Investment Rules98 Questions
Exam 6: Making Capital Investment Decisions98 Questions
Exam 7: Risk Analysis, real Options, and Capital Budgeting94 Questions
Exam 8: Interest Rates and Bond Valuation87 Questions
Exam 9: Stock Valuation87 Questions
Exam 10: Lessons From Market History77 Questions
Exam 11: Return, risk, and the Capital Asset Pricing Model Capm109 Questions
Exam 12: An Alternative View of Risk and Return: the Arbitrage Pricing Theory52 Questions
Exam 13: Risk, cost of Capital, and Valuation72 Questions
Exam 14: Efficient Capital Markets and Behavioral Challenges59 Questions
Exam 15: Long-Term Financing57 Questions
Exam 16: Capital Structure: Basic Concepts74 Questions
Exam 17: Capital Structure: Limits to the Use of Debt60 Questions
Exam 18: Valuation and Capital Budgeting for the Levered Firm54 Questions
Exam 19: Dividends and Other Payouts88 Questions
Exam 20: Raising Capital77 Questions
Exam 21: Leasing53 Questions
Exam 22: Options and Corporate Finance105 Questions
Exam 23: Options and Corporate Finance: Extensions and Applications43 Questions
Exam 24: Warrants and Convertibles63 Questions
Exam 25: Derivatives and Hedging Risk64 Questions
Exam 26: Short-Term Finance and Planning98 Questions
Exam 27: Cash Management63 Questions
Exam 28: Credit and Inventory Management66 Questions
Exam 29: Mergers,acquisitions,and Divestitures93 Questions
Exam 30: Financial Distress41 Questions
Exam 31: International Corporate Finance90 Questions
Select questions type


Suppose your wealthy Aunt Minnie has asked you to manage her large stock portfolio.You would like to use options to increase her total return and also reduce her risks.Describe the types of options you would buy or sell,as well as your rationale,given the following circumstances:
∙ Aunt Minnie owns 10,000 shares of a large oil company common stock.You believe the stock is overpriced,but she won't let you sell any shares because her late husband told her to never,ever sell any.How do you protect her from what you believe is an impending price decline?
∙ Your analysis suggests that a technology stock is poised for a large price increase within the next year.Aunt Minnie won't agree to spend the dollars required to obtain shares but has consented to allow you to spend some money on options but only because she trusts you.You don't want to disappoint her.What should you do?
(Essay)
4.8/5  (67)
(67) You own a call option on Jasper Co.stock that expires in one year.The exercise price is $35.The current price of the stock is $48 and the risk-free rate of return is 4.5 percent.Assume the option will finish in the money.What is the current value of the call option per share?
(Multiple Choice)
4.8/5 (79)
(79) Which one of the following statements concerning call option writers is true?
(Multiple Choice)
4.8/5 (85)
(85) If you consider stockholders to be the owners of a firm,then those stockholders:
(Multiple Choice)
4.9/5 (82)
(82) Tru-U stock is selling for $41 a share.A 6-month call on Tru-U stock with a strike price of $45 is priced at $1.60.Risk-free assets are currently returning .29 percent per month.What is the price of a 6-month put on Tru-U stock with a strike price of $45?
(Multiple Choice)
4.9/5 (87)
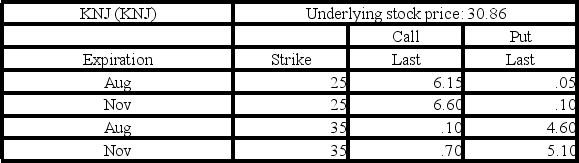
(87) 
A put option on ABC stock with an exercise price of $35 expires today.The current price of ABC stock is $36.The put is:
(Multiple Choice)
4.8/5 (81)
(81) On the expiration day,the maximum price of a put option on a stock is the greater of the:
(Multiple Choice)
4.9/5 (71)
(71) You sold a put contract on EDF stock at an option price of $.25 and an exercise price of $22.50.The option expires today when EDF stock is selling for $21.70 a share.Ignoring transaction costs and taxes,what is your total profit on this investment?
(Multiple Choice)
4.8/5 (61)
(61) Which one of the following statements is correct concerning in-the-money option values?
(Multiple Choice)
4.8/5 (70)
(70) In the Black-Scholes option pricing formula,N(d1)is the probability that a standardized,normally distributed random variable is:
(Multiple Choice)
4.9/5 (78)
(78) The value of an option if it were to immediately expire,that is,its lower pricing bound,is called an option's ________ value.
(Multiple Choice)
4.8/5 (87)
(87) All else held constant,the value of a call decreases when the:
(Multiple Choice)
4.7/5 (87)
(87) How do options apply to capital budgeting? Explain and provide an example.
(Essay)
4.8/5 (67)
(67) Suppose you look in the newspaper and see ABC trading at $50 per share.Calls on ABC with one month to expiration and an exercise price of $45 are trading at $6.50 each.Puts on ABC with one month to expiration and an exercise price of $55 are trading at $3.50 each.Are these prices reasonable? Explain.(Ignore transactions costs.)
(Essay)
4.7/5 (79)
(79) Given an exercise price,time to maturity,and European put-call parity,the present value of the strike price plus the price of the call option is equal to the:
(Multiple Choice)
4.8/5 (84)
(84) Assume you are reviewing a table that lists the current stock option contracts and quotes.Which one of these statements would correctly apply to that table?
(Multiple Choice)
4.8/5 (83)
(83) GSX stock is selling for $32.40 a share.A 4-month call on GSX stock with a strike price of $35 is priced at $.55.Risk-free assets are currently returning .3 percent per month.What is the price of a 4-month put on GSX stock with a strike price of $35?
(Multiple Choice)
4.7/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)