



 Chat with AI
Exam 10: Special Partnership Issues

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


What are the advantages of a firm being formed as a limited liability company (LLC)instead of as a limited partnership?
(Essay)
4.9/5  (86)
(86) Under the check-the-box rules,an LLC with more than one member is taxed as a partnership unless it elects to be taxed as a corporation.
(True/False)
4.8/5 (72)
(72) On December 31,Kate receives a $28,000 liquidating distribution from the KLM Partnership.On that date,Kate's basis in her limited partnership interest is $18,000 (which,of course,includes her share of partnership liabilities).The other partners assume her $6,000 share of liabilities.Just prior to the distribution,the partnership has the following balance sheet.Kate is leaving the partnership but the partnership is continuing.
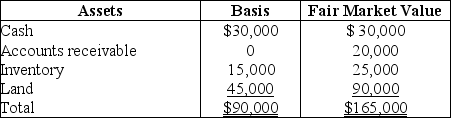
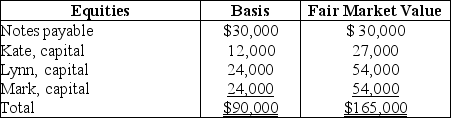 What is the amount and character of the gain that Kate must recognize on the liquidating distribution?
 (Essay)
4.8/5 (76)
(76) Becky has a $24,000 basis in her partnership interest.She receives a current distribution of $4,000 cash,unrealized receivables with a basis of $12,000 and an FMV of $16,000,and land held as an investment with a basis of $3,000 and an FMV of $8,000.The partners' relative interests in the Sec.751 assets do not change as a result of the current distribution.The basis of her partnership interest following the distribution is
(Multiple Choice)
5.0/5 (84)
(84) For Sec.751 purposes,"substantially appreciated inventory" means property held for sale to customers whose market value exceeds its adjusted basis.
(True/False)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)