



 Chat with AI
Exam 11: S Corporations

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


Tax-exempt interest earned by an S corporation is not reported to its shareholders because it is excluded from the shareholders' gross income.
(True/False)
4.9/5  (87)
(87) April Corporation's Subchapter S election was voluntarily terminated for 2010.The first year that April would be eligible to reelect S corporation status is
(Multiple Choice)
4.9/5 (85)
(85) Krause Corporation makes an S election,believing that it has no current or accumulated E&P.However,after an IRS audit,Krause is found to have failed the passive investment income test for three consecutive years and also to have a Subchapter C E&P balance from its three pre-election tax years.The IRS will
(Multiple Choice)
4.8/5 (79)
(79) The accumulated adjustments account is the cumulative total of ordinary income or loss and separately stated items (excluding tax-exempt income and expenses)for the most recent continuous period during which the corporation has been an S corporation.
(True/False)
4.8/5 (87)
(87) An S corporation reports ordinary income of $120,000 after deducting $20,000 for Fred's salary.Fred and his three children own the S corporation equally.The IRS determines Fred's stock transfer to his three children is not bona fide.Reasonable compensation for Fred is $40,000.How much of the S corporation's $140,000 pre-salary income must be reported by Fred?
(Multiple Choice)
4.7/5 (93)
(93) Connie's Restaurant has been an S corporation since it was formed in 2006.Its results for the previous year are as follows:
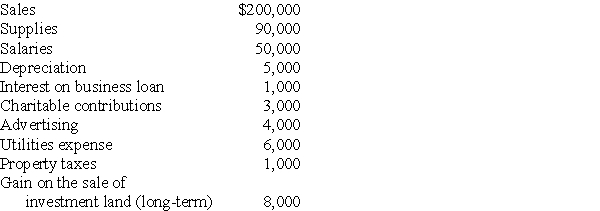 What are Connie's separately stated items? What is the S corporation's ordinary income?
 (Essay)
4.9/5 (78)
(78) List and discuss five advantages and five disadvantages of electing to be taxed as an S corporation over a C corporation or a partnership.
(Essay)
4.9/5 (73)
(73) The passive income test relating to an S corporation election is applied
(Multiple Choice)
4.8/5 (87)
(87) Eagle Corporation has always been an S corporation.Eagle is 100% owned by Katy.Katy's adjusted basis in the Eagle stock is $100,000 on January 1 of the current year.During the current year,Eagle distributes XYZ stock (a capital asset)to Katy.The XYZ stock has a $50,000 FMV and a $40,000 adjusted basis on Eagle's books.The XYZ stock has been held as an investment for four years by Eagle.Eagle Corporation reports $40,000 of ordinary income in the current year.What is Katy's basis in the Eagle stock at the beginning of the next year?
(Essay)
4.7/5 (78)
(78) Corporations and partnerships can be S corporation shareholders.
(True/False)
4.7/5 (77)
(77) Potter Corporation reports the following results for the current year:
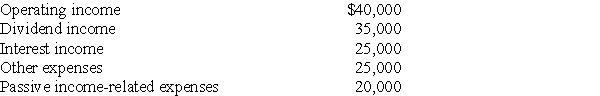 At the end of the year,Potter's Subchapter C E&P is $50,000.What is the amount of Potter's excess net passive income?
 (Essay)
4.7/5 (89)
(89) Gofer Corporation,an S corporation,is owned equally by Mahmoud and Kwame.The corporation had long-term capital gains of $100,000 and ordinary income of $90,000 for the current year and made no distributions.What is the amount of ordinary income from S corporation activities that Mahmoud must report?
(Short Answer)
4.7/5 (74)
(74) Martha,a U.S.citizen,owns 40% of the stock of George Corporation,an electing S corporation.At the time of her death this year,the George stock passes to her estate.The stock is subsequently transferred to a trust provided for in Martha's will.Can the testamentary trust hold the George stock for a two-year period before the S election is terminated?
(Essay)
4.8/5 (77)
(77) Dilley Corporation is an electing S corporation that uses a calendar year as its tax year.On October 31,Dilley's S election is terminated because of the acquisition of stock by an ineligible stockholder.Dilley Corporation shareholder Alan is allocated an S corporation loss for the year,which cannot be used because of the basis limitation.Alan will lose the unused loss if not used by
(Multiple Choice)
4.8/5 (68)
(68) On June 30 of the current year,the S election of Great Corporation is terminated,thus creating a six-month S short year and a six-month C short year.Great Corporation is a calendar-year taxpayer.The S short-year return is due
(Multiple Choice)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)