



 Chat with AI
Exam 28: Property Transactions: Nontaxable Exchanges

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


Jenna,who is single,sold her principal residence on December 1,2016,and excluded the $150,000 gain because she met the ownership and usage requirements under Sec.121.Jenna purchased another residence in Pensacola on January 1,2017,that she occupied until July 1,2017,when she received a new job offer from an employer in Miami.She sells the Pensacola residence on October 1,2017,and realizes a gain of $40,000.Jenna may exclude what amount of the gain from the sale on October 1,2017?
(Multiple Choice)
4.9/5  (84)
(84) Discuss the rules regarding the holding period for like-kind property received in a nontaxable exchange.
(Essay)
5.0/5 (91)
(91) Replacing a building with land qualifies as replacement property under the involuntary conversion rules relevant to a casualty.
(True/False)
4.8/5 (83)
(83) If a taxpayer owns more than one home,she can designate the home that will be considered her principal residence for purposes of the Sec.121 exclusion.
(True/False)
4.8/5 (71)
(71) A sale of property and subsequent purchase of like-kind property may be treated as a like-kind exchange if the two transactions are interdependent.
(True/False)
4.9/5 (66)
(66) Each of the following is true of deferral of gain attributable to the involuntary conversion of personal property with the exception of
(Multiple Choice)
4.8/5 (89)
(89) Landry exchanged land with an adjusted basis of $50,000 for another parcel of land worth $35,000 plus $10,000 of cash.Landry held the original land for investment purposes and will do the same with the new parcel.Due to the exchange,Landry will recognize
(Multiple Choice)
4.9/5 (74)
(74) Frank,a single person,sold his home this year.He had owned and lived in the house for 10 years.Frank signed a contract on March 4 to sell his home and closed the sale on May 3. 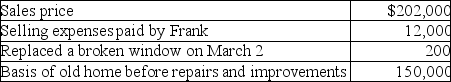 Based on these facts,what is the amount of his recognized gain?
 (Multiple Choice)
4.9/5 (84)
(84) If real property used in a trade or business or held for investment is condemned,it must be replaced with property having a similar functional use.
(True/False)
4.9/5 (84)
(84) Kuda owns a parcel of land she acquired on June 1,2012,as an investment.She exchanges the land on July 5,2017,for a storage building to be used in her business and marketable securities to be held as an investment.The marketable securities' holding period begins on
(Multiple Choice)
4.7/5 (75)
(75) The basis of non-like-kind property received is the basis in the hands of the transferor at the date of the exchange.
(True/False)
4.7/5 (78)
(78) Real property exchanged for personal property,both held for productive use in a business,qualifies as a like-kind exchange.
(True/False)
4.9/5 (89)
(89) Kuda owns a parcel of land she acquired on June 1,2012,as an investment.She exchanges the land on July 5,2017,for a storage building to be used in her business and marketable securities to be held as an investment.On what date does the storage building's holding period begin?
(Multiple Choice)
4.7/5 (81)
(81) May a taxpayer elect under Sec.1033 to defer recognition of loss resulting from an involuntary conversion?
(Essay)
4.9/5 (76)
(76) Summer exchanges an office building used in her business for another office building.Summer's office building has a FMV of $250,000 (basis of $180,000).The FMV of the new building is $300,000,and it is subject to a mortgage of $60,000,which is assumed by Summer.Summer also pays the other party $40,000 cash.
a.What is the amount of gain realized by Summer?
b.What is the amount of gain recognized by Summer?
c.What is the basis of the new building to Summer?
(Essay)
5.0/5 (96)
(96) The holding period for boot property received begins on the day after the date of the exchange.
(True/False)
4.9/5 (68)
(68) Pierce sold his home this year.He had owned and lived in the house for 10 years.Pierce signed a contract on March 4 to sell his home. 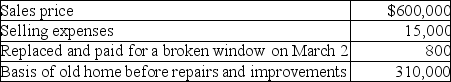 Based on these facts,what is the amount of his recognized gain?
 (Multiple Choice)
4.8/5 (77)
(77) An investor in artwork holds a Picasso painting which has appreciated substantially since she purchased it.The art investor exchanges the Picasso for a Van Gogh painting of similar value.The transaction qualifies as a like-kind exchange and the gain will not be recognized.
(True/False)
4.9/5 (76)
(76) William and Kate married in 2017 and purchased a new home together.Each had owned and lived in separate residences for the past 5 years.William's adjusted basis in his old residence was $200,000; Kate's adjusted basis in her old residence was $120,000.In late 2017,William sells his residence for $500,000 while Kate sells her residence for $190,000.What is the total gain to be excluded from these transactions in 2017?
(Multiple Choice)
4.7/5 (83)
(83) Lana owned a house used as a rental property for three years.During this rental period,she took $60,000 of depreciation deductions.Lana moved into the house and has used it as her principal residence for the past two years.Lana has just sold the house and realized a $200,000 gain.She will recognize gain of
(Multiple Choice)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)