



 Chat with AI
Exam 24: Losses and Bad Debts

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: the Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions107 Questions
Exam 7: Corporate Acquisitions and Reorganizations108 Questions
Exam 8: Consolidated Tax Returns104 Questions
Exam 9: Partnership Formation and Operation116 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Ustaxation of Foreign-Related Transactions97 Questions
Exam 17: An Introduction to Taxation109 Questions
Exam 18: Determination of Tax152 Questions
Exam 19: Gross Income: Inclusions144 Questions
Exam 20: Gross Income: Exclusions116 Questions
Exam 21: Property Transactions: Capital Gains and Losses147 Questions
Exam 22: Deductions and Losses146 Questions
Exam 23: Itemized Deductions130 Questions
Exam 24: Losses and Bad Debts125 Questions
Exam 25: Employee Expenses and Deferred Compensation151 Questions
Exam 26: Depreciation, cost Recovery, amortization, and Depletion106 Questions
Exam 27: Accounting Periods and Methods124 Questions
Exam 28: Property Transactions: Nontaxable Exchanges125 Questions
Exam 29: Property Transactions: Sec1231 and Recapture115 Questions
Exam 30: Special Tax Computation Methods, tax Credits, and Payment of Tax147 Questions
Exam 31: Tax Research133 Questions
Exam 32: Corporations149 Questions
Exam 33: Partnerships and S Corporations150 Questions
Exam 34: Taxes and Investment Planning84 Questions
Select questions type


A theft loss is deducted in the year in which the theft is discovered.
(True/False)
4.8/5  (78)
(78) A taxpayer guarantees another person's obligation and is forced to pay the debt under the terms of the guarantee.The original debtor does not repay the taxpayer.The taxpayer/guarantor may deduct the loss.
(True/False)
4.9/5 (84)
(84) During the year,Mark reports $90,000 of active business income from his law practice.He also owns two passive activities.From Activity A,he earns $20,000 of income,and from Activity B,he incurs a $30,000 loss.As a result,Mark
(Multiple Choice)
4.9/5 (70)
(70) In October 2017,Jonathon Remodeling Co. ,an accrual-method taxpayer,remodels and renovates an office building for Dale and bills him $30,000.Dale signs a note for the debt.Dale keeps delaying payment and files bankruptcy in 2018.Creditors are informed that no assets are available for payment.Jonathon Remodeling Co.will report
(Multiple Choice)
4.9/5 (90)
(90) A taxpayer may deduct suspended losses of a passive activity when the taxpayer completely terminates his or her ownership of the activity.
(True/False)
4.9/5 (78)
(78) In order to be recognized and deducted on a tax return,a loss must first be realized.
(True/False)
4.9/5 (81)
(81) No deduction is allowed for a partially worthless nonbusiness debt.
(True/False)
4.8/5 (84)
(84) Joy reports the following income and loss: 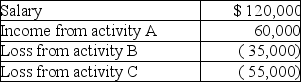 Activities A,B,and C are all passive activities.
Based on this information,Joy has the following suspended losses:
Activities A,B,and C are all passive activities.
Based on this information,Joy has the following suspended losses: (Multiple Choice)
4.9/5 (87)
(87) In the case of casualty losses of personal-use property,the losses sustained in each separate casualty are reduced by both $100 and 10 percent of the taxpayer's AGI for the year.
(True/False)
4.8/5 (70)
(70) When the taxpayer anticipates a full recovery on a casualty loss of personal-use property but receives less than full recovery in a subsequent year,the unrecovered portion may be deducted.
(True/False)
4.8/5 (72)
(72) For purposes of the application of the passive loss limitations,a closely held C corporation is a C corporation in which more than 50 percent of the stock is owned by five or fewer individuals at any time during the last half of the taxable year.
(True/False)
4.8/5 (72)
(72) Lisa loans her friend,Grace,$10,000 to finance a new business.If Grace defaults on the loan,Lisa may take a deduction for a business bad debt in the year of total worthlessness.
(True/False)
4.8/5 (91)
(91) A taxpayer suffers a casualty loss on personal-use property for which he has insurance coverage.However,to avoid a premium increase,the taxpayer fails to make a timely claim.In this situation is the full deduction for the casualty,after the normal floors,available to the taxpayer? Why or why not?
(Essay)
4.8/5 (73)
(73) A closely held C corporation's passive losses may offset its portfolio income.
(True/False)
4.8/5 (86)
(86) Constance,who is single,is in an automobile accident in 2017,and her car sustains $6,200 in damages.Constance does not expect to recover any of the loss from her insurance company.Constance's 2017 AGI is $31,000.Her casualty loss is $3,000; she has other itemized deductions of $1,200.In 2018,Constance's insurance company reimburses her $2,800.Constance's 2018 AGI is $28,000.As a result,Constance must
(Multiple Choice)
4.8/5 (78)
(78) The amount realized by Matt on the sale of property to Caitlin includes all of the following with the exception of
(Multiple Choice)
4.9/5 (73)
(73) Nicole has a weekend home on Pecan Island that she purchased in 2013 for $250,000.Recently,the home was appraised at $260,000.After the appraisal,a hurricane hit Pecan Island,severely damaging Nicole's home.An appraisal placed the value of the home at $140,000 after the hurricane.Because of its prohibitive cost,Nicole had no hurricane insurance.Before any reductions or limitations,Nicole's casualty loss amount is
(Multiple Choice)
4.8/5 (83)
(83) Why did Congress enact restrictions and limitations on losses from passive activities?
(Essay)
4.9/5 (83)
(83) A business bad debt gives rise to an ordinary deduction while a nonbusiness bad debt is treated as a short-term capital loss.
(True/False)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)