



 Chat with AI
Exam 13: Jurisdictional Issues in Business Taxation

Exam 1: Taxes and Taxing Jurisdictions85 Questions
Exam 2: Policy Standards for a Good Tax85 Questions
Exam 3: Taxes As Transaction Costs82 Questions
Exam 4: Maxims of Income Tax Planning92 Questions
Exam 5: Tax Research75 Questions
Exam 6: Taxable Income From Business Operations116 Questions
Exam 7: Property Acquisitions and Cost Recovery Deductions106 Questions
Exam 8: Property Dispositions110 Questions
Exam 9: Nontaxable Exchanges97 Questions
Exam 10: Sole Proprietorships, Partnerships, Llcs, and S Corporations72 Questions
Exam 11: The Corporate Taxpayer97 Questions
Exam 12: The Choice of Business Entity97 Questions
Exam 13: Jurisdictional Issues in Business Taxation102 Questions
Exam 14: The Individual Tax Formula113 Questions
Exam 15: Compensation and Retirement Planning107 Questions
Exam 16: Investment and Personal Financial Planning109 Questions
Exam 17: Tax Consequences of Personal Activities93 Questions
Exam 18: The Tax Compliance Process a Present Value of $1 B Present Value of Annuity of $1 C 2013 Income Tax Rates86 Questions
Select questions type


The payroll factor in the UDITPA state income tax apportionment formula always includes executive compensation.
(True/False)
4.8/5  (89)
(89) Section 482 of the Internal Revenue Code gives the IRS the authority to apportion or allocate gross income, deductions, or credits between/among related parties to correct any distortion resulting from unrealistic prices charged by members of the group to each other for goods or services.
(True/False)
4.8/5 (72)
(72) Transfer prices cannot be used by U.S. corporations and their foreign affiliates to shift income between taxing jurisdictions.
(True/False)
4.8/5 (75)
(75) The sales factor in the UDITPA state income tax apportionment formula equals out-of-state sales divided by total sales.
(True/False)
4.9/5 (76)
(76) Under most tax treaties, income attributable to a permanent establishment through which a foreign taxpayer conducts business can be taxed only by the taxpayer's country of residence.
(True/False)
4.8/5 (79)
(79) Tri-State's, Inc. operates in Arkansas, Oklahoma, and Kansas. Assume that each state has adopted the UDITPA formula. During the corporation's tax year ended December 31, the apportionment data indicated:  Tri-State's income for the current year is $250,000. Approximately how much will be taxed by Kansas?
 (Multiple Choice)
4.8/5 (89)
(89) Under the U.S. tax system, a domestic corporation pays U.S. tax only on the portion of its business income earned in the United States.
(True/False)
4.8/5 (64)
(64) Albany, Inc. does business in states C andD. State C uses an apportionment formula that double-weights the sales factor; state D apportions income using an equally-weighted three-factor formula. Albany's before tax income is $3,000,000, and its sales, payroll, and property factors are as follows.
(Multiple Choice)
4.8/5 (81)
(81) Many Mountains, Inc. is a U.S. multinational corporation. This year, it had the following income.  Many Mountains paid $15,000 income tax to Country X and $28,500 income tax to Country Y. Compute Many Mountains' allowable foreign tax credit.
 (Multiple Choice)
5.0/5 (75)
(75) The foreign tax credit can reduce a corporation's alternative minimum tax.
(True/False)
4.7/5 (67)
(67) Lincoln Corporation, which has a 34% marginal tax rate, owns 50% of the stock of a controlled foreign corporation (CFC). At the beginning of the year, Lincoln's basis in its CFC stock was $100,000. The CFC's current year income was $1 million, $600,000 of which was subpart F income. The CFC paid no foreign income tax and distributed no dividends. What is Lincoln's tax basis in its CFC stock at the end of the taxable year?
(Multiple Choice)
4.8/5 (82)
(82) BiState Inc. conducts business in North Carolina and South Carolina. If BiState's apportionment percentage in North Carolina is 63%, its apportionment percentage in South Carolina can be no more than 37%.
(True/False)
4.9/5 (83)
(83) A foreign branch operation of a U.S. corporation is not a separate legal entity.
(True/False)
4.8/5 (74)
(74) In which of the following cases are the U.S. shareholders in a controlled foreign corporation (CFC) deferring U.S. tax on the CFC's income?
(Multiple Choice)
4.9/5 (83)
(83) Albany, Inc. does business in states C and D. State C apportions income using an equally-weighted three-factor formula; state D uses an apportionment formula that double-weights the sales factor. Albany's before tax income is $3,000,000, and its sales, payroll, and property factors are as follows.
(Multiple Choice)
4.9/5 (77)
(77) Koscil Inc. had the following taxable income. 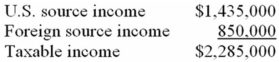 Koscil paid $315,000 foreign income tax. Compute its U.S. income tax liability.
 (Essay)
4.9/5 (81)
(81) Excess foreign tax credits can only be carried to future tax years.
(True/False)
4.9/5 (80)
(80) Pennworth Corporation operates in the United States and foreign country M. Its domestic subsidiary Delco, Inc. operates in foreign country N. This year, the two corporations report the following.  If Pennworth and Delco file a consolidated U.S. tax return, compute consolidated income tax liability.
 (Multiple Choice)
4.9/5 (81)
(81) Luttrix Inc. does business in Nebraska (6% tax rate) and Colorado (3% tax rate). All other factors being equal, Luttrix will reduce state taxes if it constructs a new manufacturing plant in Colorado.
(True/False)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)