



 Chat with AI
Exam 13: Jurisdictional Issues in Business Taxation

Exam 1: Taxes and Taxing Jurisdictions85 Questions
Exam 2: Policy Standards for a Good Tax85 Questions
Exam 3: Taxes As Transaction Costs82 Questions
Exam 4: Maxims of Income Tax Planning92 Questions
Exam 5: Tax Research75 Questions
Exam 6: Taxable Income From Business Operations116 Questions
Exam 7: Property Acquisitions and Cost Recovery Deductions106 Questions
Exam 8: Property Dispositions110 Questions
Exam 9: Nontaxable Exchanges97 Questions
Exam 10: Sole Proprietorships, Partnerships, Llcs, and S Corporations72 Questions
Exam 11: The Corporate Taxpayer97 Questions
Exam 12: The Choice of Business Entity97 Questions
Exam 13: Jurisdictional Issues in Business Taxation102 Questions
Exam 14: The Individual Tax Formula113 Questions
Exam 15: Compensation and Retirement Planning107 Questions
Exam 16: Investment and Personal Financial Planning109 Questions
Exam 17: Tax Consequences of Personal Activities93 Questions
Exam 18: The Tax Compliance Process a Present Value of $1 B Present Value of Annuity of $1 C 2013 Income Tax Rates86 Questions
Select questions type


Tradewinds is a Bermuda corporation that is 100% owned by Larkin, a U.S. corporation. Which of the following transactions generates subpart F income for U.S. tax purposes?

Free
(Multiple Choice)
4.9/5  (79)
(79) Correct Answer: Verified
B
The United States taxes its citizens on their worldwide incomes.
Free
(True/False)
4.8/5 (86)
(86) Correct Answer:Verified
VerifiedTrue
The sales factor in the UDITPA state income tax apportionment formula equals in-state sales divided by total sales.
Free
(True/False)
4.8/5 (86)
(86) Correct Answer:Verified
VerifiedTrue
The income earned by a foreign branch operation of a U.S. corporation is taxable by the United States only when repatriated.
(True/False)
4.8/5 (75)
(75) If a U.S. multinational corporation incurs start-up losses from foreign operations, which of the following organizational forms provide immediate U.S. tax savings from the deduction of the losses?
(Multiple Choice)
4.9/5 (68)
(68) A U.S. taxpayer can make an annual election to take a credit or a deduction for foreign income taxes paid.
(True/False)
4.9/5 (71)
(71) Verdi Inc. has before-tax income of $500,000. Verdi operates entirely in state Q, which has a 10% corporate income tax. Compute Verdi's combined federal and state tax burden as a percentage of its before-tax income.
(Multiple Choice)
4.8/5 (79)
(79) Chester, Inc., a U.S. multinational, earns income in three foreign countries. Country A has a 25% income tax, Country B has a 35% income tax, and Country C has a 45% income tax. In which of these countries could Chester lower its world-wide tax liability by operating through a foreign subsidiary rather than a domestic subsidiary? Assume the foreign subsidiary will reinvest all after-tax earnings rather than paying dividends.
(Multiple Choice)
5.0/5 (93)
(93) The United States has jurisdiction to tax income earned by any foreign corporation that is a controlled subsidiary of a U.S. parent corporation.
(True/False)
4.8/5 (91)
(91) Which of the following statements about the Uniform Division of Income for Tax Purposes Act (UDITPA) is false?
(Multiple Choice)
4.9/5 (89)
(89) Cross-crediting allows multinational corporations to use excess credits generated in low- tax jurisdictions to offset excess limitations generated in high-tax jurisdictions.
(True/False)
4.9/5 (73)
(73) Origami does business in states X and Y. State X uses an equally-weighted three-factor apportionment formula and has a 4 percent state tax rate. State Y uses an apportionment formula that double-weights the sales factor and has a 6 percent tax rate. Cromwell's taxable income, before apportionment, is $3 million. Its sales, payroll, and property information are as follows. 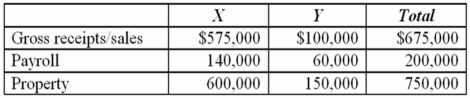 a. Calculate Origami's apportionment factors, income apportioned to each state, and state tax liability.
b. State Y is considering changing its apportionment formula to a single sales factor. Given its current level of activity, would such a change increase or decrease Origami's state income tax burden? Provide calculations to support your conclusion.
a. Calculate Origami's apportionment factors, income apportioned to each state, and state tax liability.
b. State Y is considering changing its apportionment formula to a single sales factor. Given its current level of activity, would such a change increase or decrease Origami's state income tax burden? Provide calculations to support your conclusion. (Essay)
4.8/5 (81)
(81) Which of the following statements regarding Internal Revenue Code Section 482 is false?
(Multiple Choice)
4.8/5 (90)
(90) Which of the following statements about subpart F income is false?
(Multiple Choice)
4.7/5 (71)
(71) The UDITPA formula for apportioning income among states is based on four equally weighted factors.
(True/False)
4.9/5 (86)
(86) A U.S. parent corporation that receives a dividend from a wholly-owned foreign subsidiary that pays a 45% income tax to its home country does not owe any U.S. tax on the dividend.
(True/False)
4.9/5 (76)
(76) Which of the following taxes is eligible for the foreign tax credit?
(Multiple Choice)
4.9/5 (85)
(85) Tri-State's, Inc. operates in Arkansas, Oklahoma, and Kansas. Assume that each state has adopted the UDITPA formula. During the corporation's tax year ended December 31, the apportionment data indicated:  Tri-State's income for the current year is $250,000. Approximately how much income will be taxed by Oklahoma?
 (Multiple Choice)
4.8/5 (82)
(82) Wilmington, Inc., a Pennsylvania corporation, manufactures computer components that it sells to Seine Corporation, a French company, for assembly into finished products. Wilmington owns 90% of Seine's stock. Wilmington's cost per component is $5, its selling price per component is $16, and it sold 110,000 components to Seine this year. Wilmington's taxable income as reported on its Form 1120 was $2,400,000, and Seine's taxable income as reported on its French corporate income tax return was $1,750,000. Determine the effect on the taxable incomes of both corporations if the IRS determines that an arm's length transfer price per component is $23.
(Multiple Choice)
5.0/5 (91)
(91) Which of the following statements concerning the nexus required for a state to tax income is false?
(Multiple Choice)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)