



 Chat with AI
Exam 8: Property Dispositions

Exam 1: Taxes and Taxing Jurisdictions85 Questions
Exam 2: Policy Standards for a Good Tax85 Questions
Exam 3: Taxes As Transaction Costs82 Questions
Exam 4: Maxims of Income Tax Planning92 Questions
Exam 5: Tax Research75 Questions
Exam 6: Taxable Income From Business Operations116 Questions
Exam 7: Property Acquisitions and Cost Recovery Deductions106 Questions
Exam 8: Property Dispositions110 Questions
Exam 9: Nontaxable Exchanges97 Questions
Exam 10: Sole Proprietorships, Partnerships, Llcs, and S Corporations72 Questions
Exam 11: The Corporate Taxpayer97 Questions
Exam 12: The Choice of Business Entity97 Questions
Exam 13: Jurisdictional Issues in Business Taxation102 Questions
Exam 14: The Individual Tax Formula113 Questions
Exam 15: Compensation and Retirement Planning107 Questions
Exam 16: Investment and Personal Financial Planning109 Questions
Exam 17: Tax Consequences of Personal Activities93 Questions
Exam 18: The Tax Compliance Process a Present Value of $1 B Present Value of Annuity of $1 C 2013 Income Tax Rates86 Questions
Select questions type


Mr. and Mrs. Churchill operate a small business. This year, the Churchills sold a commercial office building used in their business for $1.5 million. They purchased the building in 1997 for a cost of $1.4 million and had deducted $538,000 MACRS depreciation through date of sale. The Churchills should characterize the $638,000 gain recognized on sale as:
(Multiple Choice)
4.8/5  (78)
(78) McOwen Inc. reported $6,029,400 net income before tax on this year's financial statements prepared in accordance with GAAP. The corporation's records reveal the following information.
• A tornado destroyed an office building and its contents. McOwen's book basis in the building and contents was $4,100,000 and its tax basis in the building and contents was $1,539,000. McOwen's reimbursement from its insurance company was $1 million.
• Four years ago, McOwen realized a $90,000 gain on the sale of investment property and elected the installment sale method to report the gain for tax purposes. Its gross profit percentage is 37.45%, and it received a $40,000 principal payment on its installment note this year.
• Net income per books includes a $13,670 net capital gain. McOwen has a $63,000 capital loss carryforward into the current year.
• Depreciation expense per books was $111,400, and MACRS depreciation was $398,100.
Compute McOwen's taxable income.
(Essay)
4.9/5 (62)
(62) The gain or loss recognized on any disposition of a capital asset is characterized as capital gain or loss.
(True/False)
4.7/5 (83)
(83) In its current tax year, PRS Corporation generated $300,000 ordinary income from the performance of consulting services for its clients. PRS sold two assets, recognizing a $20,000 gain on the first sale and a $31,000 loss on the second sale. Which of the following statements is false?
(Multiple Choice)
4.8/5 (76)
(76) Mr. and Mrs. Marley operate a small business. This year, the Marleys sold a commercial office building used in their business for $1.1 million. They purchased the building in 1999 for a cost of $900,000 and have deducted $300,000 MACRS depreciation through date of sale. The Marleys should characterize the $500,000 gain recognized on sale as:
(Multiple Choice)
4.8/5 (73)
(73) Noble Inc. paid $310,000 for equipment three years ago. This year, it sold the equipment for $200,000. Through date of sale, accumulated book depreciation was $93,840 and accumulated tax depreciation was $147,327. Assuming a 35% tax rate, what is the effect of the sale on Noble's deferred tax accounts?
(Multiple Choice)
4.9/5 (77)
(77) R&T Inc. made the following sales of capital assets this year. 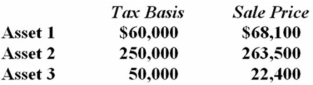 What is the effect of the three sales on R&T's taxable income this year?
 (Multiple Choice)
4.8/5 (84)
(84) Twelve years ago, Mr. and Mrs. Bathgate purchased a business. This year, they sold the business for $750,000 lump-sum payment. The business had the following balance sheet assets. 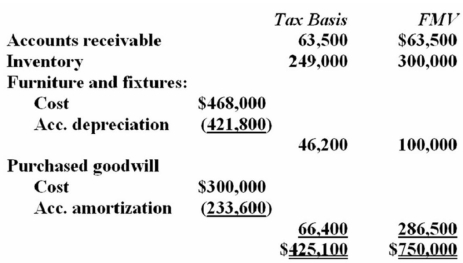 As a result of the sale, the Bathgates should recognize:
 (Multiple Choice)
4.9/5 (73)
(73) A tornado demolished several delivery vans owned for three years by Wadham Company. Wadham's adjusted basis in the vans was $28,400, and Wadham paid $90,000 to purchase new vans. Wadham received a $25,000 settlement from its casualty insurance company. Consequently, Wadham recognizes:
(Multiple Choice)
4.9/5 (72)
(72) Zeron Inc. generated $1,349,600 ordinary income from operations this year. It also recognized $29,200 recaptured ordinary income, $21,000 net Section 1231 gain, and $14,900 net capital loss on the sale of assets. Compute Zeron's taxable income.
(Multiple Choice)
4.8/5 (77)
(77) Several years ago, Y&S Inc. purchased a patent on a production process for $250,000 and has amortized $91,000 of the cost. Y&S has learned that a rival company recently developed a new process that renders the patent worthless. Consequently, Y&S made a public announcement that it would no longer enforce the patent. What is the tax consequence to Y&S of this unfortunate situation?
(Multiple Choice)
4.9/5 (87)
(87) Hugo Inc., a calendar year taxpayer, sold two operating assets this year. The first sale generated a $38,700 Section 1231 gain, and the second sale generated a $59,400 Section 1231 loss. As a result of these sales, Hugo should recognize:
(Multiple Choice)
4.9/5 (87)
(87) Netelli Inc. owned a tract of land with a $175,000 basis that was subject to a $228,500 nonrecourse mortgage. Netelli defaulted on the mortgage, and the creditor foreclosed on the land. Netelli must recognize a $53,500 gain on the disposition of the land.
(True/False)
4.8/5 (64)
(64) The use of the installment sale method can result in an unfavorable difference between book income and taxable income in the year of sale.
(True/False)
4.9/5 (84)
(84) Milton Inc. recognized a $1,300 net Section 1231 loss in 2012. If Milton recognizes a $5,000 net Section 1231 gain in 2013, it must characterize $1,300 as ordinary income.
(True/False)
4.9/5 (80)
(80) Blitza Inc. owned real property used for 12 years in its business that was subject to a $294,500 nonrecourse mortgage. Blitza failed to make timely mortgage payments, so the creditor foreclosed. At date of foreclosure, Blitza's basis in the property was $300,000, and the property's appraised FMV was $260,000. Which of the following statements is true?
(Multiple Choice)
4.9/5 (52)
(52) According to the realization principle, an increase in the value of an asset is not accounted for as income unless the amount of the increase can be accurately measured.
(True/False)
4.7/5 (90)
(90) A taxpayer that is using the installment sale method to recognize gain must recompute the gross profit percentage every year during the term of the installment note.
(True/False)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)