



 Chat with AI
Exam 9: Interest Rate Risk II

Exam 1: Why Are Financial Institutions Special97 Questions
Exam 2: Financial Services: Depository Institutions116 Questions
Exam 3: Financial Services: Finance Companies75 Questions
Exam 4: Financial Services: Securities Brokerage and Investment Banking111 Questions
Exam 5: Financial Services: Mutual Funds and Hedge Funds112 Questions
Exam 6: Financial Services: Insurance100 Questions
Exam 7: Risks of Financial Institutions111 Questions
Exam 8: Interest Rate Risk I110 Questions
Exam 9: Interest Rate Risk II98 Questions
Exam 10: Credit Risk: Individual Loan Risk112 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk59 Questions
Exam 12: Liquidity Risk100 Questions
Exam 13: Foreign Exchange Risk100 Questions
Exam 14: Sovereign Risk90 Questions
Exam 15: Market Risk97 Questions
Exam 16: Off-Balance-Sheet Risk107 Questions
Exam 17: Technology and Other Operational Risks108 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees105 Questions
Exam 20: Capital Adequacy148 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards127 Questions
Exam 23: Options, Caps, Floors, and Collars114 Questions
Exam 24: Swaps97 Questions
Exam 25: Loan Sales92 Questions
Exam 26: Securitization114 Questions
Select questions type


Macaulay's Duration
The duration of a zero coupon bond is equal to its maturity.
-Calculating modified duration involves
(Multiple Choice)
4.9/5  (73)
(73) First Duration Bank has the following assets and liabilities on its balance sheet Assets Par Amount Rate Liabilities Par Amount Rate 2-year commercial loans, annual fixed rate, at par \ 400 million 10\% 1-year CDs, annual fixed rate, at par \ 450 million 7\% 1-year Treasury bills \ 100 million Net Worth \ 50 million
-What is the duration of the commercial loans?
(Multiple Choice)
4.9/5 (79)
(79) Which of the following is indicated by high numerical value of the duration of an asset?
(Multiple Choice)
4.8/5 (77)
(77) Setting the duration of the assets higher than the duration of the liabilities will exactly immunize the net worth of an FI from interest rate shocks.
(True/False)
4.9/5 (82)
(82) Duration increases with the maturity of a fixed-income asset at a decreasing rate.
(True/False)
4.9/5 (95)
(95) What is the effect of a 100 basis point increase in interest rates on the market value of equity of the FI? Use the duration approximation relationship. Assume r = 4 percent.
(Multiple Choice)
4.7/5 (88)
(88) Perfect matching of the maturities of the assets and liabilities will always achieve perfect immunization for the equity holders of an FI against interest rate risk.
(True/False)
5.0/5 (82)
(82) For a given maturity fixed-income asset, duration decreases as the market yield increases.
(True/False)
4.9/5 (69)
(69) 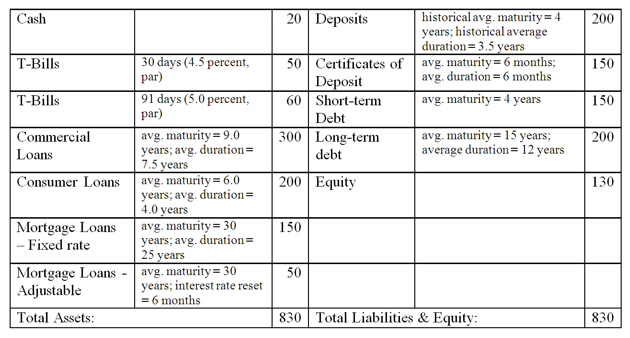 -What is this bank's interest rate risk exposure, if any?
-If interest rates increase by 20 basis points, what is the approximate change in the market price using the duration approximation?
(Multiple Choice)
4.9/5 (84)
(84) The economic meaning of duration is the interest elasticity of a financial assets price.
(True/False)
4.9/5 (83)
(83) Managers can achieve the results of duration matching by using these to hedge interest rate risk.
(Multiple Choice)
4.9/5 (75)
(75) Assets Amount Rate Duration Cash \ 75 million Loans \ 750 million 12 percent 1.75 years Treasuries \ 175 million 9 percent 7.00 years Liabilities and Equity Time Deposits \ 350 million 7 percent 1.75 years CDs \ 575 million 8 percent 2.50 years Equity \ 75 million
-Calculate the duration of the assets to four decimal places.
(Multiple Choice)
4.7/5 (66)
(66) Larger coupon payments on a fixed-income asset cause the present value weights of the cash flows to be lower in the duration calculation.
(True/False)
4.8/5 (85)
(85) Fully amortizing loan cash flows:
=30,000,000 =0 =6 =2 = Macaulay's Duration
-Calculate the modified duration of a two-year corporate loan paying 6 percent interest annually. The $40,000,000 loan is 100 percent amortizing, and the current yield is 9 percent annually.
(Multiple Choice)
4.9/5 (77)
(77) 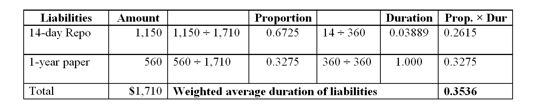 -What is the leverage-adjusted duration gap?

Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)