



 Chat with AI
Exam 9: Interest Rate Risk II

Exam 1: Why Are Financial Institutions Special97 Questions
Exam 2: Financial Services: Depository Institutions116 Questions
Exam 3: Financial Services: Finance Companies75 Questions
Exam 4: Financial Services: Securities Brokerage and Investment Banking111 Questions
Exam 5: Financial Services: Mutual Funds and Hedge Funds112 Questions
Exam 6: Financial Services: Insurance100 Questions
Exam 7: Risks of Financial Institutions111 Questions
Exam 8: Interest Rate Risk I110 Questions
Exam 9: Interest Rate Risk II98 Questions
Exam 10: Credit Risk: Individual Loan Risk112 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk59 Questions
Exam 12: Liquidity Risk100 Questions
Exam 13: Foreign Exchange Risk100 Questions
Exam 14: Sovereign Risk90 Questions
Exam 15: Market Risk97 Questions
Exam 16: Off-Balance-Sheet Risk107 Questions
Exam 17: Technology and Other Operational Risks108 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees105 Questions
Exam 20: Capital Adequacy148 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards127 Questions
Exam 23: Options, Caps, Floors, and Collars114 Questions
Exam 24: Swaps97 Questions
Exam 25: Loan Sales92 Questions
Exam 26: Securitization114 Questions
Select questions type


When does "duration" become a less accurate predictor of expected change in security prices?
(Multiple Choice)
4.8/5  (82)
(82) An FI can immunize its portfolio by matching the maturity of its asset with its liabilities.
(True/False)
4.7/5 (72)
(72) Duration of commercial loans
-What is the FI's leverage-adjusted duration gap?
(Multiple Choice)
4.9/5 (73)
(73) For a given change in required yields, short-duration securities suffer a smaller capital loss or receive a smaller capital gain than do long-duration securities.
(True/False)
5.0/5 (90)
(90) Investing in a zero-coupon asset with a maturity equal to the desired investment horizon removes interest rate risk from the investment management process.
(True/False)
4.9/5 (83)
(83) The larger the interest rate shock, the smaller the interest rate risk exposure of an FI.
(True/False)
4.9/5 (85)
(85) Calculate the duration of a two-year corporate loan paying 6 percent interest annually, selling at par. The $30,000,000 loan is 100 percent amortizing with annual payments.
(Multiple Choice)
4.9/5 (72)
(72) $1,000 face value, 9% annual coupon, 5 year maturity, 10% rate =962.09 =1,000 =10 =5 PMT =90
-Calculate the percentage change in this bond's price if interest rates on comparable risk securities decline to 7 percent. Use the duration valuation equation.
(Multiple Choice)
4.8/5 (70)
(70) Assets Amount Rate Duration Cash \ 75 million Loans \ 750 million 12 percent 1.75 years Treasuries \ 175 million 9 percent 7.00 years Liabilities and Equity Time Deposits \ 350 million 7 percent 1.75 years CDs \ 575 million 8 percent 2.50 years Equity \ 75 million
-Calculate the leverage-adjusted duration gap to four decimal places and state the FI's interest rate risk exposure of this institution.
(Multiple Choice)
4.8/5 (79)
(79) The error from using duration to estimate the new price of a fixed-income security will be less as the amount of convexity increases.
(True/False)
4.8/5 (82)
(82) A key assumption of Macaulay duration is that the yield curve is flat so that all cash flows are discounted at the same discount rate.
(True/False)
4.8/5 (90)
(90) Buying a fixed-rate asset whose duration is exactly equal to the desired investment horizon immunizes against interest rate risk.
(True/False)
4.9/5 (77)
(77) A risk manager could restructure assets and liabilities to reduce interest rate exposure for this example by
(Multiple Choice)
4.8/5 (77)
(77) As interest rates rise, the duration of a consol bond decreases.
(True/False)
4.9/5 (72)
(72) For small change in interest rates, market prices of bonds move in an inversely proportional manner according to the size of the
(Multiple Choice)
4.8/5 (67)
(67) An FI has financial assets of $800 and equity of $50. If the duration of assets is 1.21 years and the duration of all liabilities is 0.25 years, what is the leverage-adjusted duration gap?
(Multiple Choice)
4.9/5 (89)
(89) The larger the size of an FI, the larger the _________ from any given interest rate shock.
(Multiple Choice)
4.9/5 (88)
(88) 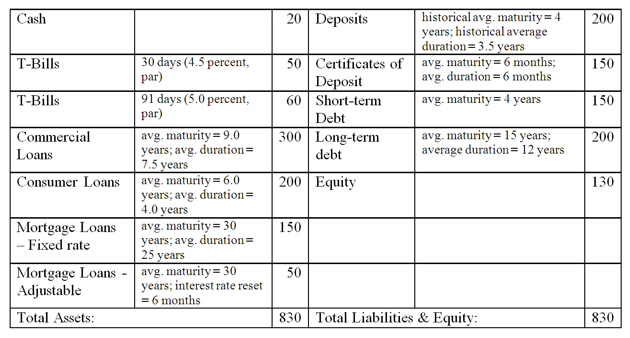 -What is the duration of the municipal notes (the value of x)?
 (Multiple Choice)
4.7/5 (92)
(92) Leverage-adjusted duration gap
-Calculate the duration of a two-year corporate bond paying 6 percent interest annually, selling at par. Principal of $20,000,000 is due at the end of two years.
(Multiple Choice)
4.9/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)