



 Chat with AI
Exam 9: Interest Rate Risk II

Exam 1: Why Are Financial Institutions Special97 Questions
Exam 2: Financial Services: Depository Institutions116 Questions
Exam 3: Financial Services: Finance Companies75 Questions
Exam 4: Financial Services: Securities Brokerage and Investment Banking111 Questions
Exam 5: Financial Services: Mutual Funds and Hedge Funds112 Questions
Exam 6: Financial Services: Insurance100 Questions
Exam 7: Risks of Financial Institutions111 Questions
Exam 8: Interest Rate Risk I110 Questions
Exam 9: Interest Rate Risk II98 Questions
Exam 10: Credit Risk: Individual Loan Risk112 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk59 Questions
Exam 12: Liquidity Risk100 Questions
Exam 13: Foreign Exchange Risk100 Questions
Exam 14: Sovereign Risk90 Questions
Exam 15: Market Risk97 Questions
Exam 16: Off-Balance-Sheet Risk107 Questions
Exam 17: Technology and Other Operational Risks108 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees105 Questions
Exam 20: Capital Adequacy148 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards127 Questions
Exam 23: Options, Caps, Floors, and Collars114 Questions
Exam 24: Swaps97 Questions
Exam 25: Loan Sales92 Questions
Exam 26: Securitization114 Questions
Select questions type


The duration of a portfolio of assets can be found by calculating the book value weighted average of the durations of the individual assets.
(True/False)
4.9/5  (85)
(85) Duration is related to maturity in a nonlinear manner through the current yield to maturity of the asset.
(True/False)
4.8/5 (79)
(79) Immunizing the net worth ratio requires that the duration of the assets be set equal to the duration of the liabilities.
(True/False)
4.8/5 (80)
(80) Modified Duration, semi-annual
Dollar Duration
Change in Price
New Price
-What is the duration of an 8 percent annual payment two-year note that currently sells at par?
(Multiple Choice)
4.8/5 (84)
(84) Marking-to-market accounting is a market value accounting method that reflects the purchase prices of assets and liabilities.
(True/False)
4.7/5 (75)
(75) In duration analysis, the times at which cash flows are received are weighted by the relative importance in present value terms of the cash flows arriving at each point in time.
(True/False)
4.7/5 (88)
(88) The leverage adjusted duration of a typical depository institution is positive.
(True/False)
4.8/5 (81)
(81) Immunizing net worth from interest rate risk using duration matching requires that the duration match must be realigned periodically as the maturity horizon approaches.
(True/False)
4.9/5 (75)
(75) First Duration, a securities dealer, has a leverage-adjusted duration gap of 1.21 years, $60 million in assets, 7 percent equity to assets ratio, and market rates are 8 percent.
-What is the impact on the dealer's market value of equity per $100 of assets if the change in all interest rates is an increase of 0.5 percent [i.e., ΔR = 0.5 percent]
(Multiple Choice)
4.9/5 (85)
(85) Rate Maturity Ask Change Ask yield 7.1250 Oct 15,2005 102:08 -1 5.9156
-If yields increase by 10 basis points, what is the approximate price change on the $100,000 Treasury note? Use the duration approximation relationship.
(Multiple Choice)
4.9/5 (81)
(81) Assets Amount Rate Duration Cash \ 75 million Loans \ 750 million 12 percent 1.75 years Treasuries \ 175 million 9 percent 7.00 years Liabilities and Equity Time Deposits \ 350 million 7 percent 1.75 years CDs \ 575 million 8 percent 2.50 years Equity \ 75 million
-Calculate the duration of the liabilities to four decimal places.
(Multiple Choice)
4.7/5 (84)
(84) Duration is related to maturity in a linear manner through the interest rate of the asset.
(True/False)
4.8/5 (79)
(79) Immunization of an FIs net worth requires the duration of the liabilities to be adjusted for the amount of leverage on the balance sheet.
(True/False)
4.8/5 (80)
(80) 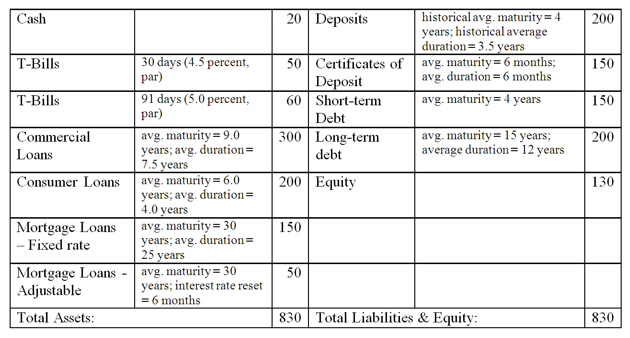 -What will be the impact, if any, on the market value of the bank's equity if all interest rates increase by 75 basis points?
 (Multiple Choice)
4.8/5 (69)
(69) The use of duration to predict changes in bond prices for given changes in interest rate changes will always underestimate the amount of the true price change.
(True/False)
4.8/5 (71)
(71) The immunization of a portfolio against interest rate risk means that the portfolio will neither gain nor lose value when interest rates change.
(True/False)
5.0/5 (73)
(73) In most countries FIs report their balance sheet using market value accounting.
(True/False)
4.8/5 (68)
(68) Investing in a zero-coupon asset with a maturity equal to the desired investment horizon is one method of immunizing against changes in interest rates.
(True/False)
4.9/5 (84)
(84) Consider a five-year, 8 percent annual coupon bond selling at par of $1,000.
-What is the duration of this bond?
(Multiple Choice)
4.9/5 (96)
(96)  -What is the leverage-adjusted duration gap of the FI?

Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)