



 Chat with AI
Exam 13: Foreign Exchange Risk

Exam 1: Why Are Financial Institutions Special97 Questions
Exam 2: Financial Services: Depository Institutions116 Questions
Exam 3: Financial Services: Finance Companies75 Questions
Exam 4: Financial Services: Securities Brokerage and Investment Banking111 Questions
Exam 5: Financial Services: Mutual Funds and Hedge Funds112 Questions
Exam 6: Financial Services: Insurance100 Questions
Exam 7: Risks of Financial Institutions111 Questions
Exam 8: Interest Rate Risk I110 Questions
Exam 9: Interest Rate Risk II98 Questions
Exam 10: Credit Risk: Individual Loan Risk112 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk59 Questions
Exam 12: Liquidity Risk100 Questions
Exam 13: Foreign Exchange Risk100 Questions
Exam 14: Sovereign Risk90 Questions
Exam 15: Market Risk97 Questions
Exam 16: Off-Balance-Sheet Risk107 Questions
Exam 17: Technology and Other Operational Risks108 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees105 Questions
Exam 20: Capital Adequacy148 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards127 Questions
Exam 23: Options, Caps, Floors, and Collars114 Questions
Exam 24: Swaps97 Questions
Exam 25: Loan Sales92 Questions
Exam 26: Securitization114 Questions
Select questions type


Your U.S. bank issues a one-year U.S. CD at 5 percent annual interest to finance a C $1.274 million (Canadian dollar) investment in two-year, fixed rate Canadian bonds selling at par and paying 7 percent annually. You expect to liquidate your position in one year. Currently, spot exchange rates are US $0.78493 per Canadian dollar.
-If you wanted to hedge your bank's risk exposure, what hedge position would you take?
(Multiple Choice)
4.9/5  (73)
(73) Violation of the interest rate parity theorem would allow arbitrage profits.
(True/False)
4.9/5 (88)
(88) On-balance-sheet hedging involves making changes in the on-balance-sheet assets and liabilities to protect FI profits from FX risk without the use of derivative securities.
(True/False)
4.9/5 (90)
(90) An FI can eliminate its currency risk exposure by matching its foreign currency assets to its foreign currency liabilities.
(True/False)
4.8/5 (79)
(79) What is the portfolio weight of the Euro in this FI's portfolio of foreign currency?
(Multiple Choice)
4.9/5 (80)
(80) The spot foreign exchange market is where forward and futures contracts and swap agreements are transacted.
(True/False)
4.8/5 (80)
(80) An FI has purchased (borrowed) a one-year $10 million Eurodollar deposit at an annual interest rate of 6 percent. It has invested these proceeds in one-year Euro (€) bonds at an annual rate of 6.5 percent after converting them at the current spot rate of €1.75/$. Both interest and principal are paid at the end of the year.
-What is the spread earned by the bank at the end of the year if the exchange rate remains at €1.75/$?
(Multiple Choice)
4.9/5 (85)
(85) During 2012, the top four banks that operate in foreign currency trading comprised almost half of the market.
(True/False)
4.9/5 (87)
(87) A positive net exposure position in FX implies the FI is net short in a currency.
(True/False)
4.9/5 (79)
(79) An FI can control its FX risk exposure by on-balance-sheet and off-balance-sheet hedging.
(True/False)
4.9/5 (77)
(77) What is the end of year profit or loss on the bank's cash position if in one year both Canadian bond rates increase to 7.538 percent and the exchange rate falls to US $0.765 per Canadian dollar? (Assume no change in U.S. interest rates.)
(Multiple Choice)
4.7/5 (79)
(79) A positive net exposure position in FX implies an FI has purchased more foreign currency than it has sold.
(True/False)
4.7/5 (73)
(73) When purchasing and selling foreign currencies to allow customers to take positions in foreign real and financial investments, the FI
(Multiple Choice)
4.9/5 (74)
(74) What is the portfolio weight of the Japanese yen in this FI's portfolio of foreign currency?
(Multiple Choice)
4.8/5 (77)
(77) The FX markets of the world have become one of the largest of all financial markets.
(True/False)
4.8/5 (81)
(81) During the late 2000's financial crisis, global stock market return correlations decreased relative to the decade before the crisis.
(True/False)
4.7/5 (84)
(84) A U.S. FI is raising all of its $20 million liabilities in dollars (one-year CDs) but investing 50 percent in U.S. dollar assets (one-year maturity loans) and 50 percent in U.K. pound sterling assets (one-year maturity loans). Suppose the promised one-year U.S. CD rate is 9 percent, to be paid in dollars at the end of the year, and that one-year, credit risk-free loans in the United States are yielding only 10 percent. Credit risk-free one-year loans are yielding 16 percent in the United Kingdom. 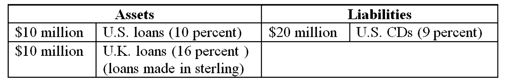 -If the exchange rate had fallen from $1.60/≤1 at the beginning of the year to $1.50/≤1 at the end of the year when the FI needed to repatriate the principal and interest on the loan. What would be the dollar loan amount repatriated at the end of the year?
 (Multiple Choice)
4.8/5 (73)
(73) Assume that instead of investing in Euro bonds at a fixed rate of 6.5 percent, it invests them in variable rates of LIBOR + 1.5 percent, reset every six months. The current LIBOR rate is 5 percent. What is the annual spread earned by the bank if LIBOR at the end of six months is 5.5 percent? Assume both interest and principal will be reinvested in six months. Assume the exchange rate remains at €1.75/$ at the end of the year.
(Multiple Choice)
4.9/5 (82)
(82) In which of the following FX trading activities does the FI not assume FX risk?
(Multiple Choice)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)