



 Chat with AI
Exam 13: Foreign Exchange Risk

Exam 1: Why Are Financial Institutions Special97 Questions
Exam 2: Financial Services: Depository Institutions116 Questions
Exam 3: Financial Services: Finance Companies75 Questions
Exam 4: Financial Services: Securities Brokerage and Investment Banking111 Questions
Exam 5: Financial Services: Mutual Funds and Hedge Funds112 Questions
Exam 6: Financial Services: Insurance100 Questions
Exam 7: Risks of Financial Institutions111 Questions
Exam 8: Interest Rate Risk I110 Questions
Exam 9: Interest Rate Risk II98 Questions
Exam 10: Credit Risk: Individual Loan Risk112 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk59 Questions
Exam 12: Liquidity Risk100 Questions
Exam 13: Foreign Exchange Risk100 Questions
Exam 14: Sovereign Risk90 Questions
Exam 15: Market Risk97 Questions
Exam 16: Off-Balance-Sheet Risk107 Questions
Exam 17: Technology and Other Operational Risks108 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees105 Questions
Exam 20: Capital Adequacy148 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards127 Questions
Exam 23: Options, Caps, Floors, and Collars114 Questions
Exam 24: Swaps97 Questions
Exam 25: Loan Sales92 Questions
Exam 26: Securitization114 Questions
Select questions type


The reasons nondepository FIs have less FX risk than major money center banks include
(Multiple Choice)
4.8/5  (82)
(82) Which of the following FX trading activities is used for purposes of speculation?
(Multiple Choice)
4.9/5 (86)
(86) The foreign exchange market in Tokyo is the largest FX trading market.
(True/False)
4.7/5 (79)
(79) The one-year CD rates for financial institutions with AA ratings are 5 percent in the U.S. and 8 percent in France. An AA-rated U.S. financial institution can borrow by issuing CDs or lend by purchasing CDs at these rates in either market. The current spot rate is $0.20/Euro.
-What should be the spot rate in order for no arbitrage to take place, assuming the one-year forward rate is $0.1975/€?
(Multiple Choice)
4.9/5 (86)
(86) FX trading income is derived only from profit (or loss) on the FI's speculative currency positions.
(True/False)
4.9/5 (78)
(78) A U.S. FI is raising all of its $20 million liabilities in dollars (one-year CDs) but investing 50 percent in U.S. dollar assets (one-year maturity loans) and 50 percent in U.K. pound sterling assets (one-year maturity loans). Suppose the promised one-year U.S. CD rate is 9 percent, to be paid in dollars at the end of the year, and that one-year, credit risk-free loans in the United States are yielding only 10 percent. Credit risk-free one-year loans are yielding 16 percent in the United Kingdom. 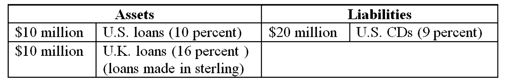 -If the exchange rate had fallen from $1.60/≤1 at the beginning of the year to $1.50/≤1 at the end of the year, the weighted return on the FI's asset portfolio would be
 (Multiple Choice)
4.8/5 (77)
(77) The FI is acting as a FX market agent for its customers when it
(Multiple Choice)
4.9/5 (64)
(64) Most nonbank FIs have foreign exchange risk exposure that is smaller than the exposure of the large U.S. money-center banks.
(True/False)
4.8/5 (79)
(79) Off-balance-sheet hedging involves taking a position in FX forward or other derivative securities even though no FX assets or liabilities are on the balance sheet.
(True/False)
4.9/5 (88)
(88) As the U.S. dollar appreciates against the Japanese yen, U.S. goods become less expensive to Japanese consumers.
(True/False)
5.0/5 (74)
(74) FX risk exposure of an FI essentially relates to which of the following activities?
(Multiple Choice)
4.7/5 (67)
(67) FX trading risk exposure continues into the night until all FI operations are closed.
(True/False)
4.7/5 (82)
(82) The market in which foreign currency is traded for immediate delivery is the
(Multiple Choice)
4.8/5 (94)
(94) Most profits or losses on foreign trading for FIs come from
(Multiple Choice)
4.9/5 (91)
(91) How would you characterize the FI's risk exposure to fluctuations in the yen/dollar exchange rate?
(Multiple Choice)
4.8/5 (90)
(90) A U.S. FI is raising all of its $20 million liabilities in dollars (one-year CDs) but investing 50 percent in U.S. dollar assets (one-year maturity loans) and 50 percent in U.K. pound sterling assets (one-year maturity loans). Suppose the promised one-year U.S. CD rate is 9 percent, to be paid in dollars at the end of the year, and that one-year, credit risk-free loans in the United States are yielding only 10 percent. Credit risk-free one-year loans are yielding 16 percent in the United Kingdom.
-What amount, in sterling, will the FI have to repatriate back to the U.S. after one year if the exchange rate remains constant at $1.60 to ≤1.
-What amount, in sterling, will the FI have to repatriate back to the U.S. after one year if the exchange rate remains constant at $1.60 to ≤1. (Multiple Choice)
4.7/5 (87)
(87) Purchasing power parity is based on the difference in productive output (GDP) that exists between two countries.
(True/False)
4.9/5 (80)
(80) Deviations from the international currency parity relationships may occur because of
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)