



 Chat with AI
Exam 13: Foreign Exchange Risk

Exam 1: Why Are Financial Institutions Special97 Questions
Exam 2: Financial Services: Depository Institutions116 Questions
Exam 3: Financial Services: Finance Companies75 Questions
Exam 4: Financial Services: Securities Brokerage and Investment Banking111 Questions
Exam 5: Financial Services: Mutual Funds and Hedge Funds112 Questions
Exam 6: Financial Services: Insurance100 Questions
Exam 7: Risks of Financial Institutions111 Questions
Exam 8: Interest Rate Risk I110 Questions
Exam 9: Interest Rate Risk II98 Questions
Exam 10: Credit Risk: Individual Loan Risk112 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk59 Questions
Exam 12: Liquidity Risk100 Questions
Exam 13: Foreign Exchange Risk100 Questions
Exam 14: Sovereign Risk90 Questions
Exam 15: Market Risk97 Questions
Exam 16: Off-Balance-Sheet Risk107 Questions
Exam 17: Technology and Other Operational Risks108 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees105 Questions
Exam 20: Capital Adequacy148 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards127 Questions
Exam 23: Options, Caps, Floors, and Collars114 Questions
Exam 24: Swaps97 Questions
Exam 25: Loan Sales92 Questions
Exam 26: Securitization114 Questions
Select questions type


An FI has purchased (borrowed) a one-year $10 million Eurodollar deposit at an annual interest rate of 6 percent. It has invested these proceeds in one-year Euro (€) bonds at an annual rate of 6.5 percent after converting them at the current spot rate of €1.75/$. Both interest and principal are paid at the end of the year.
-What is the spread earned by the bank if the end-of-year exchange rate is €1.77/$?
(Multiple Choice)
4.9/5  (64)
(64) An FI has purchased (borrowed) a one-year $10 million Eurodollar deposit at an annual interest rate of 6 percent. It has invested these proceeds in one-year Euro (€) bonds at an annual rate of 6.5 percent after converting them at the current spot rate of €1.75/$. Both interest and principal are paid at the end of the year.
-What is the spread earned if the bank can sell one-year forward Euros at €1.755/$?
(Multiple Choice)
4.8/5 (83)
(83) As the U.S. dollar appreciates against the Japanese yen, Japanese goods sold in the U.S. become less expensive to the U.S. consumer.
(True/False)
4.8/5 (74)
(74) The following are the net currency positions of a U.S. FI (stated in U.S. dollars).
Note: Net currency positions are foreign exchange bought minus foreign exchange sold restated in U.S. dollar terms. Currency Net Position Canadian Dollar +US \1 ,200 Euro -US \2 45,900 Japanese Yen +US \5 05,000 Swiss Franc -US \3 6,700 British Pound +US \4 47,900
-What is the FI's total FX investment?
(Multiple Choice)
4.9/5 (72)
(72) The one-year CD rates for financial institutions with AA ratings are 5 percent in the U.S. and 8 percent in France. An AA-rated U.S. financial institution can borrow by issuing CDs or lend by purchasing CDs at these rates in either market. The current spot rate is $0.20/Euro.
-If the bank receives a quote of $0.1975/€ for one-year forward rates for the Euro (to buy and to sell), what is the arbitrage profit for the bank if it uses $1,000,000 as the notional amount?
(Multiple Choice)
4.8/5 (78)
(78) Yen Bank wishes to invest in Yen loans at a rate of 10 percent. The bank will fund the loans in the domestic CD market at a rate of 6.3 percent. This on-balance-sheet FX risk will be hedged in the spot market at a forward rate of $0.62/×. The spot rate on yen is $0.60/×.
-What must be the spot exchange rate to eliminate the preference for the yen loans if the forward rate remains $0.62/×?
(Multiple Choice)
4.8/5 (95)
(95) A U.S. FI is raising all of its $20 million liabilities in dollars (one-year CDs) but investing 50 percent in U.S. dollar assets (one-year maturity loans) and 50 percent in U.K. pound sterling assets (one-year maturity loans). Suppose the promised one-year U.S. CD rate is 9 percent, to be paid in dollars at the end of the year, and that one-year, credit risk-free loans in the United States are yielding only 10 percent. Credit risk-free one-year loans are yielding 16 percent in the United Kingdom. 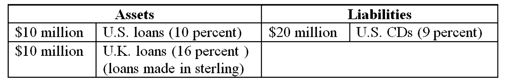 -If the spot foreign exchange rate remains constant at $1.60 to ≤1 throughout the year, the return from the U.K. investment will be
 (Multiple Choice)
4.8/5 (76)
(76) To a U.S. trader of foreign currencies, a direct quote indicates U.S. dollars received for each one unit of the foreign currency.
(True/False)
4.8/5 (87)
(87) Average daily turnover in the FX market has recently been over $4 trillion.
(True/False)
4.8/5 (62)
(62) Which of the following is an example of interest rate parity?
(Multiple Choice)
4.8/5 (90)
(90) Assume that instead of investing in Euro bonds at a fixed rate of 6.5 percent, the FI invests them in variable rates of LIBOR + 1.5 percent, reset every six months. The current LIBOR rate is 5 percent. LIBOR at the end of six months is 5.5 percent. Assume both interest and principal will be reinvested in six months. Assume the spot exchange rate is €1.75/$. What should be the one-year forward rate in order for the bank to earn a spread of 1 percent?
(Multiple Choice)
4.8/5 (70)
(70) A negative net exposure position in FX implies that the FI is
(Multiple Choice)
4.9/5 (79)
(79) The decline in European FX volatility during the last decade has been offset in part by
(Multiple Choice)
4.8/5 (95)
(95) The reason an FI receives a fee when purchasing foreign currencies to allow customers to complete international transactions is because the FI assumes some FX risk.
(True/False)
4.9/5 (81)
(81) If foreign currency exchange rates are highly positively correlated, how can a FI reduce its exchange rate risk exposure?
(Multiple Choice)
5.0/5 (81)
(81) A U.S. FI is raising all of its $20 million liabilities in dollars (one-year CDs) but investing 50 percent in U.S. dollar assets (one-year maturity loans) and 50 percent in U.K. pound sterling assets (one-year maturity loans). Suppose the promised one-year U.S. CD rate is 9 percent, to be paid in dollars at the end of the year, and that one-year, credit risk-free loans in the United States are yielding only 10 percent. Credit risk-free one-year loans are yielding 16 percent in the United Kingdom.
-If the exchange rate had fallen from $1.60/≤1 at the beginning of the year to $1.50/≤1 at the end of the year when the FI needed to repatriate the principal and interest on the loan. What would the dollar loan revenues at the end of the year be as a return on the original dollar investment?
-If the exchange rate had fallen from $1.60/≤1 at the beginning of the year to $1.50/≤1 at the end of the year when the FI needed to repatriate the principal and interest on the loan. What would the dollar loan revenues at the end of the year be as a return on the original dollar investment? (Multiple Choice)
4.8/5 (90)
(90) The total FX risk for a domestic bank that is making a one-year loan in a foreign currency is that the interest income expected on the loan is exposed to a depreciation of the foreign currency.
(True/False)
4.8/5 (91)
(91) The following are the net currency positions of a U.S. FI (stated in U.S. dollars). Currency Assets Liabilities FX Bought FX Sold British pound 24,600 70,000 170,400 321,000 Yen 31,000 20,400 250,000 220,000 Swiss franc 10,200 9,800 8,000 10,800
-What is the FI's net exposure in British pounds?
(Multiple Choice)
4.9/5 (70)
(70) The decrease in European FX volatility during the last decade has occurred because of
(Multiple Choice)
4.9/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)