



 Chat with AI
Exam 7: Futures and Options on Foreign Exchange

Exam 1: Globalization and the Multinational Firm99 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange100 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure100 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market101 Questions
Exam 12: International Bond Market99 Questions
Exam 13: International Equity Markets99 Questions
Exam 14: Interest Rate and Currency Swaps95 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital99 Questions
Exam 18: International Capital Budgeting101 Questions
Exam 19: Multinational Cash Management98 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing100 Questions
Select questions type


Assume that the dollar-euro spot rate is $1.28 and the six-month forward rate is
.The six-month U.S.dollar rate is 5% and the Eurodollar rate is 4%.The minimum price that a six-month American call option with a striking price of $1.25 should sell for in a rational market is
(Multiple Choice)
4.8/5  (76)
(76) Yesterday,you entered into a futures contract to sell €62,500 at $1.50 per €.Your initial performance bond is $1,500 and your maintenance level is $500.At what settle price will you get a demand for additional funds to be posted?
(Multiple Choice)
4.8/5 (83)
(83) A currency futures option amounts to a derivative on a derivative.Why would something like that exist?
(Multiple Choice)
4.9/5 (77)
(77) If the call finishes out-of-the-money what is your portfolio cash flow?
(Essay)
5.0/5 (77)
(77) Empirical tests of the Black-Scholes option pricing formula
(Multiple Choice)
4.8/5 (63)
(63) Find the dollar value today of a 1-period at-the-money call option on €10,000.The spot exchange rate is €1.00 = $1.25.In the next period,the euro can increase in dollar value to $2.00 or fall to $1.00.The interest rate in dollars is i$ = 27.50%; the interest rate in euro is i€ = 2%.
(Multiple Choice)
4.9/5 (75)
(75) Consider an option to buy €12,500 for £10,000. In the next period, the euro can strengthen against the pound by 25% (i.e. each euro will buy 25% more pounds) or weaken by 20%.
Big hint: don't round, keep exchange rates out to at least 4 decimal places. 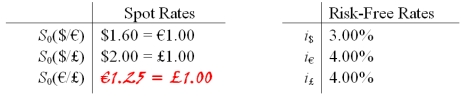 -Find the risk neutral probability of an "up" move.
 (Essay)
4.8/5 (89)
(89) For European currency options written on euro with a strike price in dollars,what of the effect of an increase in r$?
(Multiple Choice)
4.8/5 (77)
(77) Yesterday,you entered into a futures contract to buy €62,500 at $1.50 per €.Suppose the futures price closes today at $1.46.How much have you made/lost?
(Multiple Choice)
4.8/5 (74)
(74) Find the hedge ratio for a put option on $15,000 with a strike price of €10,000.In one period the exchange rate (currently S($/€)= $1.50/€)can increase by 60% or decrease by 37.5% .
(Multiple Choice)
4.8/5 (84)
(84) Find the risk-neutral probability of an "up" move FOR YOUR TREE.Hint: you can't recycle your risk neutral probability from the call option.
(Essay)
4.9/5 (83)
(83) You have written a call option on £10,000 with a strike price of $20,000.The current exchange rate is $2.00/£1.00 and in the next period the exchange rate can increase to $4.00/£1.00 or decrease to $1.00/€1.00 .The current interest rates are i$ = 3% and are i£ = 2%.Find the hedge ratio and use it to create a position in the underlying asset that will hedge your option position.
(Multiple Choice)
4.8/5 (72)
(72) A European option is different from an American option in that
(Multiple Choice)
4.9/5 (73)
(73) Using your results from parts a)and b)find the value of this put option (in €).
Your answer is worth zero points if it does not include currency symbols (€)!
(Essay)
4.9/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)