



 Chat with AI
Exam 8: Management of Transaction Exposure

Exam 1: Globalization and the Multinational Firm99 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange100 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure100 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market101 Questions
Exam 12: International Bond Market99 Questions
Exam 13: International Equity Markets99 Questions
Exam 14: Interest Rate and Currency Swaps95 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital99 Questions
Exam 18: International Capital Budgeting101 Questions
Exam 19: Multinational Cash Management98 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing100 Questions
Select questions type


If you owe a foreign currency denominated debt,you can hedge with
(Multiple Choice)
4.8/5  (93)
(93) A Japanese EXPORTER has a €1,000,000 receivable due in one year.Detail a strategy using a money market hedge that will eliminate any exchange rate risk. 1 -year rates of interest Borrowing lending Dollar 4.5\% 4.00\% Euro 6.00\% 5.25\% yen 1.00\% 0.75\% Spot exchange rates 1 -year Forward Rates \ 1.25=1.00 \ 1.2262=1.00 \ 1.00=\pm100 \ 1.03=\pm100
(Multiple Choice)
4.7/5 (71)
(71) Your firm is a Swiss exporter of bicycles.You have sold an order to a British firm for £1,000,000 worth of bicycles.Payment from the British firm (in pounds sterling)is due in 12 months.Use a money market hedge to redenominate this one-year receivable into a euro-denominated receivable with a one-year maturity. 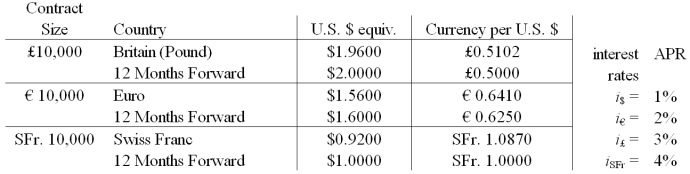 The following were computed without rounding.Select the answer closest to yours.
 (Multiple Choice)
4.8/5 (90)
(90) A call option to buy £10,000 at a strike price of $1.80 = £1.00 is equivalent to
(Multiple Choice)
4.7/5 (67)
(67) Your firm has a British customer that is willing to place a $1 million order (with payment due in 6 months),but insists upon paying in pounds instead of dollars.
(Multiple Choice)
4.8/5 (80)
(80) Suppose that $2 = £1,$1.60 = €1,and the cross exchange rate is €1.25 = £1.00.If you own a call option on £10,000 with a strike price of $1.50,you would exercise this option at maturity if
(Multiple Choice)
4.9/5 (70)
(70) The most direct and popular way of hedging transaction exposure is by
(Multiple Choice)
4.8/5 (65)
(65) Your firm is an Italian exporter of bicycles.You have sold an order to a Swiss firm for SFr.2,000,000 worth of bicycles.Payment from the customer (in Swiss francs)is due in 12 months.Detail a strategy using futures contracts that will hedge your exchange rate risk.Have an estimate of how many contracts of what type and maturity. 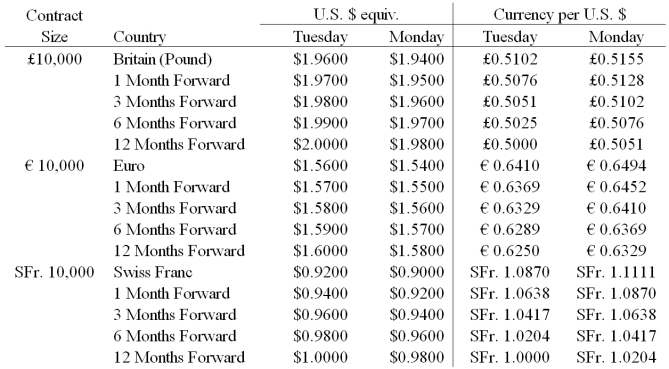
(Multiple Choice)
4.9/5 (83)
(83) Your firm is a U.K.-based importer of bicycles.You have placed an order with an Italian firm for €1,000,000 worth of bicycles.Payment (in euro)is due in 12 months.Use a money market hedge to redenominate this one-year receivable into a pound-denominated receivable with a one-year maturity. 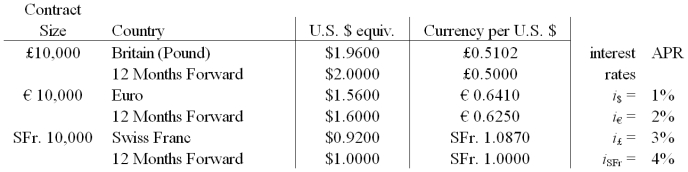 The following were computed without rounding.Select the answer closest to yours.
 (Multiple Choice)
4.8/5 (74)
(74) A call option on £1,000 with a strike price of €1,250 is equivalent to
(Multiple Choice)
4.8/5 (83)
(83) Your firm is a Swiss exporter of bicycles.You have sold an order to a French firm for €1,000,000 worth of bicycles.Payment from the French firm (in euro)is due in 12 months.Use a money market hedge to redenominate this one-year receivable into a Swiss franc -denominated receivable with a one-year maturity. 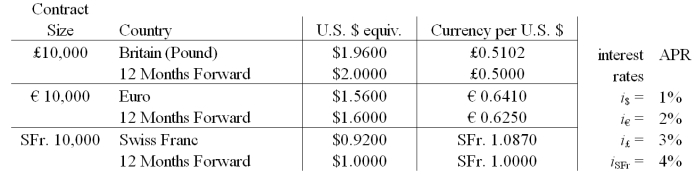 The following were computed without rounding.Select the answer closest to yours.
 (Multiple Choice)
4.9/5 (59)
(59) Your U.S.firm has a £100,000 payable with a 3-month maturity.Which of the following will hedge your liability?
(Multiple Choice)
4.8/5 (80)
(80) Suppose that the exchange rate is €1.25 = £1.00. Options (calls and puts)are available on the London exchange in units of €10,000 with strike prices of £0.80 = €1.00.Options (calls and puts)are available on the Frankfurt exchange in units of £10,000 with strike prices of €1.25 = £1.00.For a French firm to hedge a £100,000 receivable,
(Multiple Choice)
4.9/5 (64)
(64) If you own a foreign currency denominated bond,you can hedge with
(Multiple Choice)
4.8/5 (80)
(80) Suppose that the exchange rate is €1.25 = £1.00. Options (calls and puts)are available on the London exchange in units of €10,000 with strike prices of £0.80 = €1.00.Options (calls and puts)are available on the Frankfurt exchange in units of £10,000 with strike prices of €1.25 = £1.00.For a U.K.firm to hedge a €100,000 receivable,
(Multiple Choice)
4.8/5 (72)
(72) Your firm is a Swiss importer of bicycles.You have placed an order with an Italian firm for €1,000,000 worth of bicycles.Payment (in euro)is due in 12 months.Detail a strategy using futures contracts that will hedge your exchange rate risk.Have an estimate of how many contracts of what type and maturity. 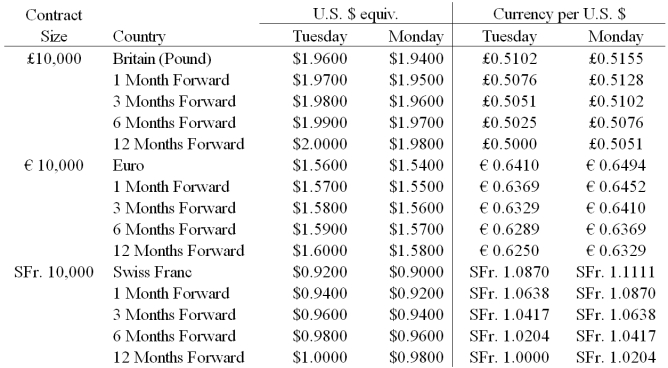
(Multiple Choice)
4.9/5 (83)
(83) Since a corporation can hedge exchange rate exposure at low cost
(Multiple Choice)
4.8/5 (70)
(70) XYZ Corporation,located in the United States,has an accounts payable obligation of ¥750 million payable in one year to a bank in Tokyo.Which of the following is NOT part of a money market hedge?
(Multiple Choice)
4.8/5 (89)
(89) Your firm is a U.K.-based exporter of bicycles.You have sold an order to a Swiss firm for SFr.1,000,000 worth of bicycles.Payment from the Swiss firm (in Swiss francs)is due in 12 months.Use a money market hedge to redenominate this one-year receivable into a euro-denominated receivable with a one-year maturity. 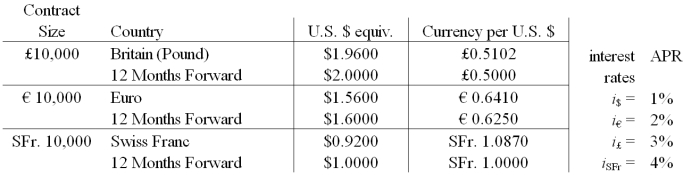 The following were computed without rounding.Select the answer closest to yours.
 (Multiple Choice)
4.9/5 (81)
(81) An exporter faced with exposure to an appreciating currency can reduce transaction exposure with a strategy of
(Multiple Choice)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)