



 Chat with AI
Exam 9: Management of Economic Exposure

Exam 1: Globalization and the Multinational Firm98 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange100 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure100 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market101 Questions
Exam 12: International Bond Market100 Questions
Exam 13: International Equity Markets99 Questions
Exam 14: Interest Rate and Currency Swaps100 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital99 Questions
Exam 18: International Capital Budgeting101 Questions
Exam 19: Multinational Cash Management100 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing100 Questions
Select questions type


A U.S. firm holds an asset in Great Britain and faces the following scenario: 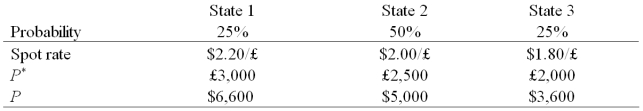 where,
P* = Pound sterling price of the asset held by the U.S. firm
P = Dollar price of the same asset
-The expected value of the investment in U.S.dollars is:
where,
P* = Pound sterling price of the asset held by the U.S. firm
P = Dollar price of the same asset
-The expected value of the investment in U.S.dollars is: (Multiple Choice)
4.8/5  (77)
(77) Discuss how you can hedge your exchange risk exposure and also examine the consequences of hedging.
(Essay)
4.8/5 (78)
(78) When the Mexican peso collapsed in 1994,declining by 37 percent,
(Multiple Choice)
4.8/5 (75)
(75) Which of the following are identified by your text as a strategy for managing operating exposure? 1)Selecting low-cost production sites.
2)Flexible sourcing policy.
3)Diversification of the market.
4)Product differentiation and R&D efforts.
5)Financial Hedging.
(Multiple Choice)
4.8/5 (85)
(85) Suppose the U.S.dollar substantially depreciates against the Japanese yen.The change in exchange rate
(Multiple Choice)
4.9/5 (68)
(68) On the basis of regression Equation 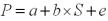 we can decompose the variability of the dollar value of the asset,Var(P),into two separate components Var(P)= b2 *Var(S)+ Var(e) The second term in the right-hand side of the equation,Var(e)represents
 (Multiple Choice)
4.8/5 (64)
(64) The firm may not be able to pass through changes in the exchange rate
(Multiple Choice)
4.8/5 (91)
(91) Consider a U.S.-based MNC with a wholly-owned French subsidiary.Following a depreciation of the dollar against the euro,which of the following best describes the mechanism of any effect of the depreciation?
(Multiple Choice)
4.7/5 (69)
(69) Investment in R&D activities can allow the firm to maintain and strengthen its competitive position in the face of adverse exchange rate movements.The mechanism for this includes
(Multiple Choice)
4.9/5 (80)
(80) The "exposure" (i.e.the regression coefficient beta)is: Hint: Calculate the expression 
(Multiple Choice)
5.0/5 (93)
(93) Generally speaking,when both a firm's costs and its price is sensitive to exchange rate changes
(Multiple Choice)
4.9/5 (102)
(102) A U.S. firm holds an asset in Great Britain and faces the following scenario: 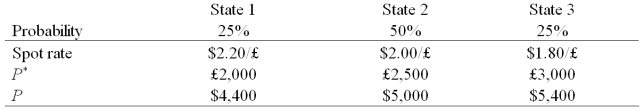 where,
P* = Pound sterling price of the asset held by the U.S. firm
P = Dollar price of the same asset
-The expected value of the investment in U.S.dollars is
where,
P* = Pound sterling price of the asset held by the U.S. firm
P = Dollar price of the same asset
-The expected value of the investment in U.S.dollars is (Multiple Choice)
4.7/5 (84)
(84) Generally speaking,a firm is subject to high degrees of operating exposure when
(Multiple Choice)
4.9/5 (81)
(81) Suppose a U.S.-based MNC maintains a vacation home for employees in the British countryside and the local price of this property is always moving together with the pound price of the U.S.dollar.As a result,
(Multiple Choice)
4.7/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)