



 Chat with AI
Exam 21: International Corporate Finance

Exam 1: Introduction to Corporate Finance71 Questions
Exam 2: Financial Statements, Taxes, and Cash Flow81 Questions
Exam 3: Working With Financial Statements96 Questions
Exam 4: Long-Term Financial Planning and Growth80 Questions
Exam 5: Introduction to Valuation: The Time Value of Money68 Questions
Exam 6: Discounted Cash Flow Valuation132 Questions
Exam 7: Interest Rates and Bond Valuation129 Questions
Exam 8: Stock Valuation119 Questions
Exam 9: Net Present Value and Other Investment Criteria115 Questions
Exam 10: Making Capital Investment Decisions108 Questions
Exam 11: Project Analysis and Evaluation106 Questions
Exam 12: Some Lessons From Capital Market History98 Questions
Exam 13: Return, Risk, and the Security Market Line109 Questions
Exam 14: Cost of Capital100 Questions
Exam 15: Raising Capital93 Questions
Exam 16: Financial Leverage and Capital Structure Policy98 Questions
Exam 17: Dividends and Payout Policy103 Questions
Exam 18: Short-Term Finance and Planning109 Questions
Exam 19: Cash and Liquidity Management101 Questions
Exam 20: Credit and Inventory Management97 Questions
Exam 21: International Corporate Finance99 Questions
Exam 22: Behavioral Finance: Implications for Financial Management45 Questions
Exam 23: Enterprise Risk Management68 Questions
Exam 24: Options and Corporate Finance106 Questions
Exam 25: Option Valuation79 Questions
Exam 26: Mergers and Acquisitions89 Questions
Exam 27: Leasing72 Questions
Select questions type


Mr.Black has agreed to a currency exchange with Mr.White.The parties have agreed to exchange C$12,500 for $10,000 with the exchange occurring 4 months from now.This agreed-upon exchange rate is called the:
(Multiple Choice)
4.8/5  (72)
(72) Assume the spot rate on the Canadian dollar is C$0.9872.The risk-free nominal rate in the U.S.is 5.4 percent while it is only 4.2 percent in Canada.Which one of the following four-year forward rates best establishes the approximate interest rate parity condition?
(Multiple Choice)
4.7/5 (70)
(70) Suppose your company imports computer motherboards from Singapore.The exchange rate is currently 1.5803S$/US$.You have just placed an order for 30,000 motherboards at a cost to you of 170.90 Singapore dollars each.You will pay for the shipment when it arrives in 120 days.You can sell the motherboards for $148 each.What will your profit be if the exchange rate goes up by 8 percent over the next 120 days?
(Multiple Choice)
4.9/5 (74)
(74) In the spot market,$1 is currently equal to £0.6211.Assume the expected inflation rate in the U.K.is 4.2 percent while it is 3.1 percent in the U.S.What is the expected exchange rate one year from now if relative purchasing power parity exists?
(Multiple Choice)
4.8/5 (71)
(71) The price of one Euro expressed in U.S.dollars is referred to as a(n):
(Multiple Choice)
4.9/5 (77)
(77) Which one of the following types of operations would be subject to the most political risk if the operation were conducted outside of a firm's home country?
(Multiple Choice)
4.9/5 (97)
(97) Trader A has agreed to give 100,000 U.S.dollars to Trader B in exchange for British pounds based on today's exchange rate of $1 = £0.62.The traders agree to settle this trade within two business day.What is this exchange called?
(Multiple Choice)
4.7/5 (74)
(74) Suppose the exchange rates are as follows: 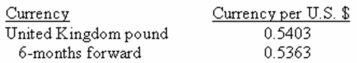 Assume interest rate parity holds and the current six-month risk-free rate in the United States is 3.1 percent.What must the six-month risk-free rate be in Great Britain?
 (Multiple Choice)
4.9/5 (79)
(79) Suppose the spot and three-month forward rates for the yen are ¥128.79 and ¥135.22,respectively.What is the approximate annual percent difference between the inflation rate in the U.S.and in Japan?
(Multiple Choice)
4.8/5 (84)
(84) You are considering a project in Poland which has an initial cost of 275,000PLN.The project is expected to return a one-time payment of 390,000PLN four years from now.The risk-free rate of return is 4.5 percent in the U.S.and 3 percent in Poland.The inflation rate is 4 percent in the U.S.and 2 percent in Poland.Currently,you can buy 277PLN for 100USD.How much will the payment of 390,000PLN be worth in U.S.dollars four years from now?
(Multiple Choice)
4.7/5 (80)
(80) Today,you can exchange $1 for £0.6522.Last week,£1 was worth $1.6104.How much profit or loss would you now have if you had converted £100 into dollars last week?
(Multiple Choice)
4.8/5 (94)
(94) Which one of the following formulas correctly describes the relative purchasing power parity relationship?
(Multiple Choice)
4.8/5 (83)
(83) Assume the spot exchange rate for the Hungarian forint is HUF 215.Also assume the inflation rate in the United States is 4 percent per year while it is 9.5 percent in Hungary.What is the expected exchange rate 5 years from now?
(Multiple Choice)
4.8/5 (78)
(78) In the spot market,$1 is currently equal to £0.6211.Assume the expected inflation rate in the U.K.is 2.6 percent while it is 4.3 percent in the U.S.What is the expected exchange rate four years from now if relative purchasing power parity exists?
(Multiple Choice)
4.9/5 (69)
(69) You are analyzing a project with an initial cost of £130,000.The project is expected to return £20,000 the first year,£50,000 the second year and £90,000 the third and final year.There is no salvage value.The current spot rate is £0.6211.The nominal risk-free return is 5.5 percent in the U.K.and 6 percent in the U.S.The return relevant to the project is 14 percent in the U.S.Assume that uncovered interest rate parity exists.What is the net present value of this project in U.S.dollars?
(Multiple Choice)
4.8/5 (70)
(70) Which of the following variables used in the covered interest arbitrage formula are correctly defined?
I.RFC:
Foreign country nominal risk-free interest rate
II.RUS:
U.S.real risk-free interest rate
III.F1:
360-day forward rate
IV.S0:
Current spot rate expressed in units of foreign currency per one U.S.dollar
(Multiple Choice)
5.0/5 (74)
(74) Which one of the following statements is correct given the following exchange rates? 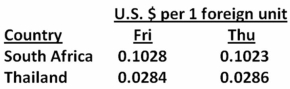
(Multiple Choice)
4.8/5 (69)
(69) Which one of the following statements is correct concerning the foreign exchange market?
(Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)